On a recent flight from Jakarta to Hong Kong, one of our colleagues picked a film more or less at random: Contagion, Steven Soderbergh’s 2011 thriller about a virus that jumps from a bat to a pig to a person. Watched in 2026, it plays like a home video of 2020. What stays with you isn’t the virus but the panic: the queues, the stripped shelves, the people who have never seen anything like it and have no playbook.
Source: Warner Brothers

It took her straight back to that spring, when the whole world seemed to reach for the same word. Google searches for “unprecedented” hit a record in April 2020, nearly six times their 2019 average. Even Oxford gave up on a single word of the year and called its 2020 report Words of an Unprecedented Year.
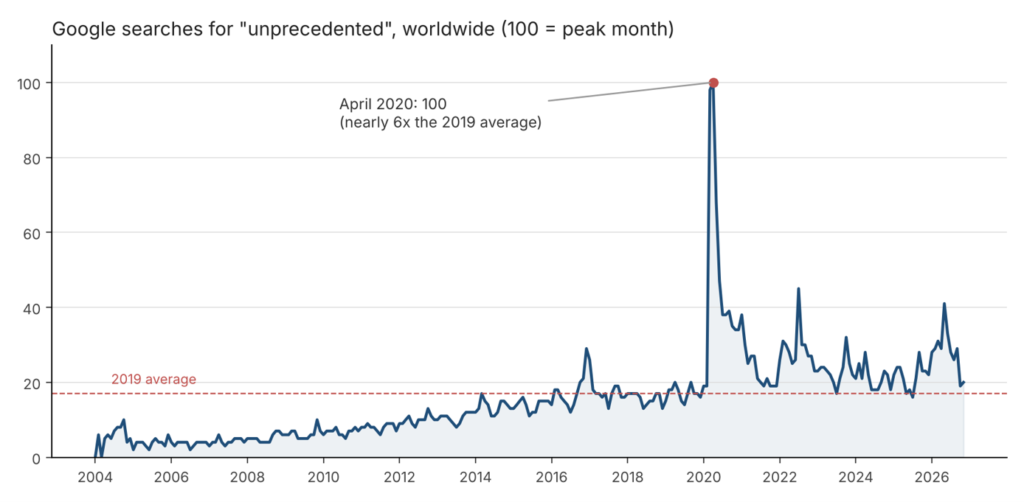
Source: Google Trends, monthly worldwide web-search interest in “unprecedented”, January 2004 to November 2026 (November partial), downloaded 5 November 2026. 100 = the peak month; the index is relative, not a count of searches.

And the word never quite went away. Every year since has averaged above 2019, and this year searches are running at about 1.7 times that level.

By the time the plane landed, though, the thing on our colleague’s mind wasn’t a virus. It was debt, which has been hard to avoid in the headlines this year. In August the U.S. national debt passed $40 trillion, a figure the Associated Press called “unprecedented”. In April the IMF warned that global government debt is on track to reach 100% of GDP by 2029, “a level previously reached only in the aftermath of World War II”. And in late October, new projections from the Congressional Budget Office had America paying around $20 trillion in interest over the next decade.

Which left her with a question for the rest of the trip. Will we look back on this year and call this debt unprecedented? Or is “unprecedented” simply what we say when we’ve forgotten the precedents?

A word that tells you how it feels

It’s an odd word to lean on so hard. Strictly, “unprecedented” is a claim about history: this has never happened before. In practice we use it to describe a feeling: we have never seen this before. Those are two very different statements, and the gap between them is where a lot of bad forecasts live.

Economists Carmen Reinhart and Kenneth Rogoff spent years mapping that gap. Their 2009 history of financial crises, spanning eight centuries of defaults, bank runs and inflations, carries a title that reads like a warning label: This Time Is Different. Their point, roughly, is that the phrase tends to be said loudest just before it turns out not to be true.

So let’s do the thing the word skips. Let’s check.

On paper, we’ve been here before

Start with America. U.S. federal debt held by the public was about 97% of GDP in the second quarter of this year. In 1946, at the end of the Second World War, it was 106%. By that yardstick America is close to its own record, but not past it.

Britain makes today’s numbers look almost modest. According to the UK’s Office for Budget Responsibility, British government debt was close to 180% of GDP at Waterloo in 1815, and hit 249% at the end of the Second World War, an all-time high. Today Britain’s public sector net debt stands at about 94% of GDP, a level the Office for National Statistics says was last seen in the early 1960s. Japan, meanwhile, carries gross government debt of about 200% of GDP this year, roughly double the G7 average, according to IMF estimates.
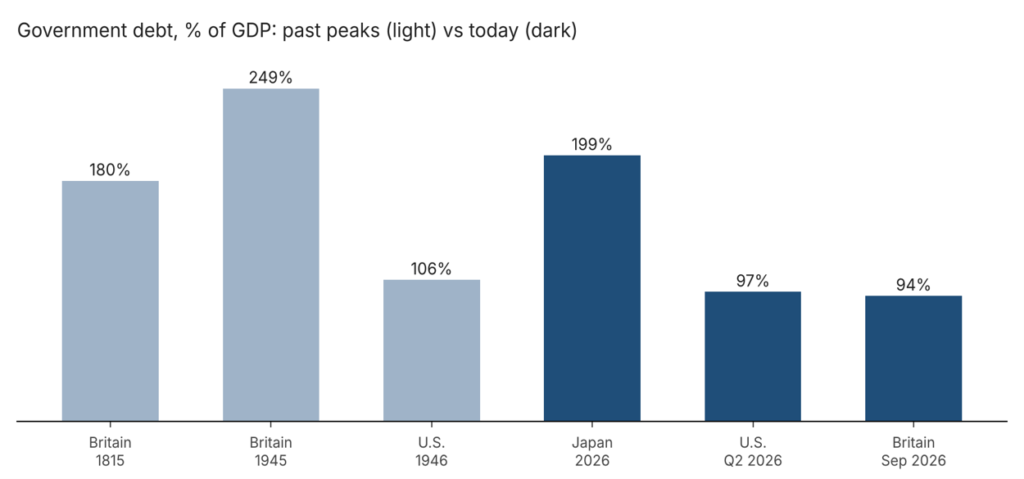
Sources: UK Office for Budget Responsibility (Britain, 1815 and 1945); Office for National Statistics, public sector net debt, end-September 2026 (Britain today); U.S. Office of Management and Budget via FRED, series FYPUGDA188S (U.S. 1946) and FYGFGDQ188S (U.S., second quarter of 2026), debt held by the public; IMF World Economic Outlook, October 2026 (Japan, 2026 estimate of gross general government debt). Definitions differ across countries; figures are approximate.

High debt hasn’t always meant disaster, either. A St. Louis Fed analysis points out that Britain’s debt stayed above 120% of GDP from the 1780s until the 1850s, decades that overlap with its Industrial Revolution, and concludes that “it cannot be asserted” that the debt held back growth. At both of its great peaks, the British government “did not need to offer abnormally large yields to attract lenders”.

On the level alone, then, the honest answer is no. Not unprecedented. Which raises a better question: if this has happened before, how did it end, and who paid?

Who paid last time

Often, nobody you could point to. After 1815, Britain didn’t so much repay its debt as outgrow it. With no major wars and a booming economy, debt fell to 29% of GDP by 1913, the OBR notes. It took almost a century, but a bigger economy simply made the old debt look smaller.

Post-war America shrank its debt much faster, from 106% of GDP in 1946 to about 22% by 1974. Growth did a lot of the work, but not all of it. Between 1945 and 1980, real interest rates in advanced economies were negative “roughly half of the time”, according to Reinhart and M. Belen Sbrancia. Savers who held government bonds earned less than inflation, year after year, and the difference whittled the debt down by 3% to 4% of GDP a year in the U.S. and Britain, they estimate.

Economists call this financial repression. It needs no vote and makes no headlines, which is either its genius or its problem, depending on whether you are the government or the saver.
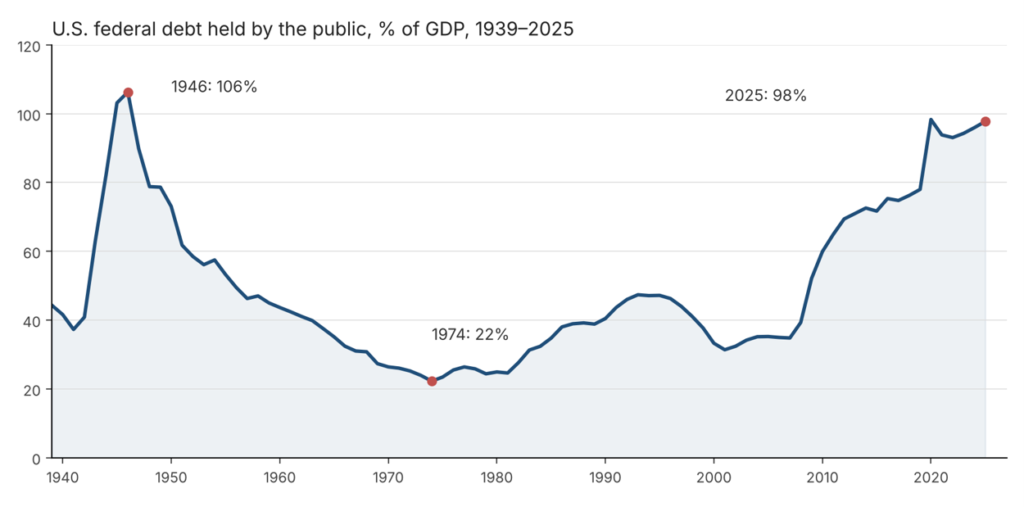
Source: U.S. Office of Management and Budget, via Federal Reserve Bank of St. Louis (FRED series FYPUGDA188S), retrieved 5 November 2026.

Others paid in plain sight. Greece cut spending and raised taxes under its bailout programmes in the 2010s, and by 2013 its economy had shrunk for 20 quarters in a row. Then there is default, which Reinhart and Rogoff’s book is crowded with, and which every government insists it will never need. History has a habit of filing “never” under “not yet”.

So what’s actually new?

This is where the word starts to earn its keep. Almost every great debt peak in the history books was a war debt. Wars end. The spending stops, the soldiers come home and go to work, and the economy grows into the bill.

Today’s debt wasn’t built by a war, so there is no peace deal coming to switch the spending off. Read the IMF’s line again: 100% of GDP is a level “previously reached only in the aftermath of World War II”. This time there is no aftermath to grow out of. Much of the borrowing goes to pensions and healthcare for ageing populations, commitments that tend to grow rather than end, and more and more of it goes to interest on the borrowing itself.

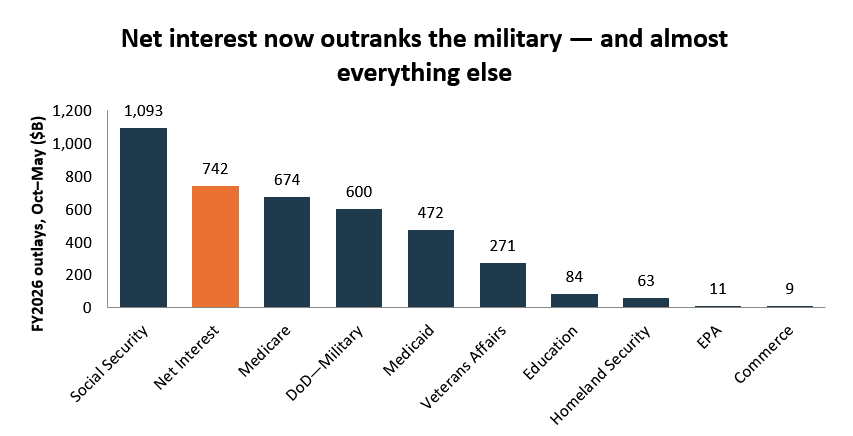
In the fiscal year that ended in September, the U.S. government spent $1.14 trillion on net interest, more than the $916 billion the Defense Department spent on the military, while running a deficit of about $2 trillion, according to the Congressional Budget Office.
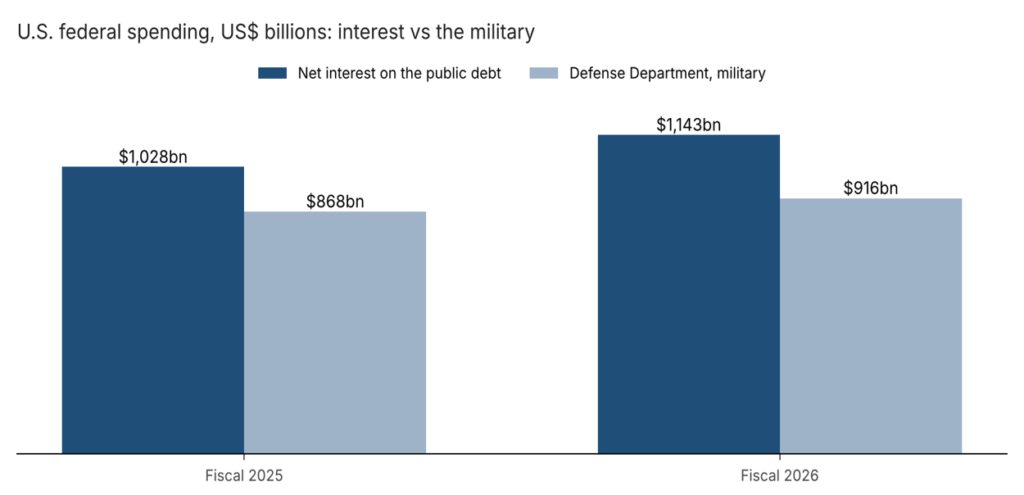
Source: Congressional Budget Office, Monthly Budget Review: September 2026 (8 October 2026), Table 3.
Fiscal years end 30 September.

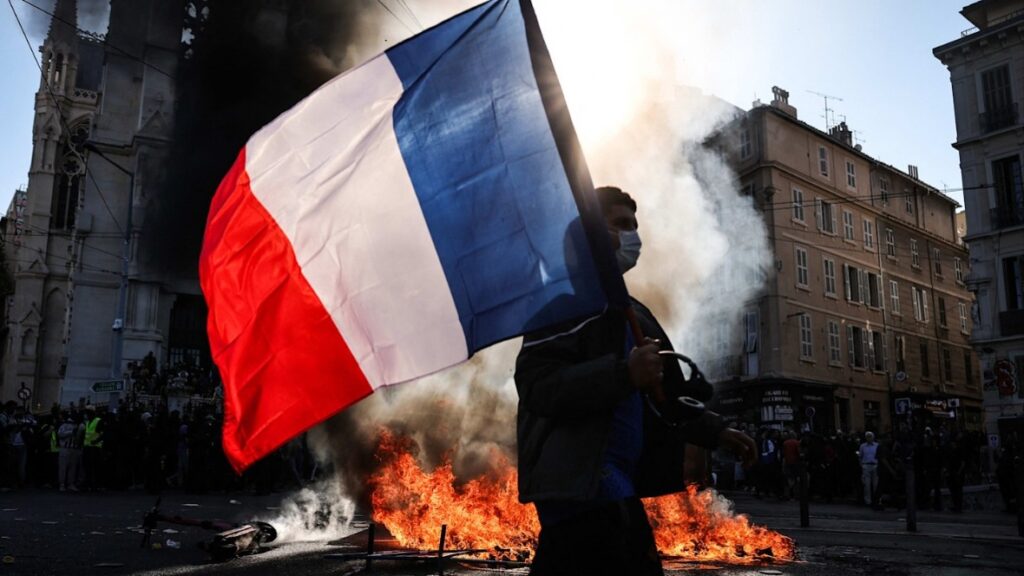
France is where these strands have knotted together. Students began protesting in mid-September at a high school in Créteil, outside Paris, over teacher shortages, overcrowded classrooms and dilapidated buildings, just as the government was preparing a 2027 budget built on spending restraint and tax measures, including a public-sector pay freeze and limits on pension increases.
Source: Financial Times

After nationwide demonstrations on 17 October, with shops looted in Paris, Marseille, Lyon and Bordeaux, police arrested at least 1,800 people across the country. Four days later, France’s 10-year borrowing cost crossed 5%, its highest since 2002. Finance minister Roland Lescure had already summed up the budget in September: “Nous n’avons plus de gras.” We have no fat left.

The bond market had been saying something similar for a while. For most of the past decade France borrowed far more cheaply than Italy or Greece. On monthly averages, it has paid more than Greece every month since June, and by the summer it had edged above Italy too.
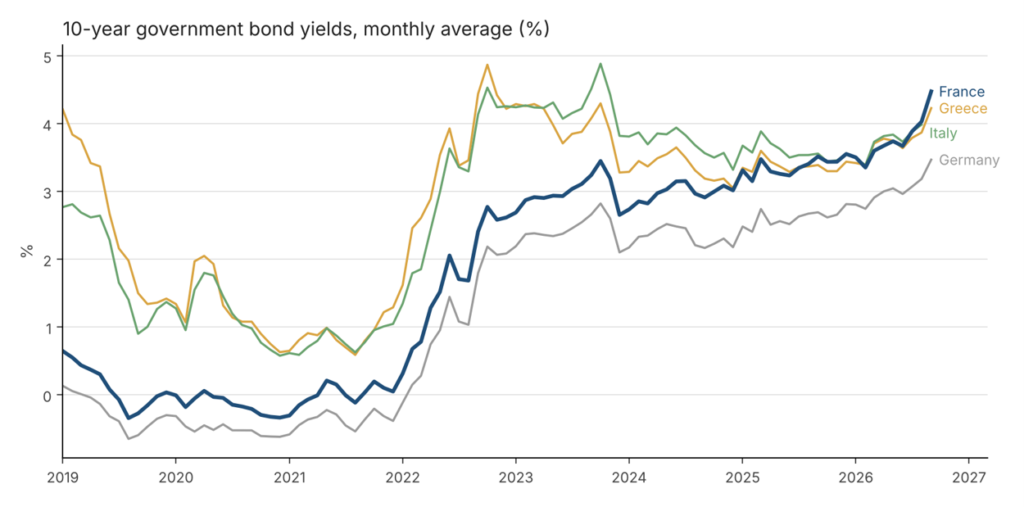
Source: OECD long-term interest rates, via Federal Reserve Bank of St. Louis (FRED series IRLTLT01FRM156N, IRLTLT01ITM156N, IRLTLT01GRM156N, IRLTLT01DEM156N), retrieved 5 November 2026. Latest data: September 2026 (Italy: August 2026).

It is tempting to draw a straight line from there to the second half of Contagion: a squeeze, a promise that can’t be kept, a street on fire. It is tempting, too, to call it a generational bargain in which the old vote, the young pay and the bill has finally arrived. Is that fair? Partly, perhaps. But money flows both ways between generations, through parents’ help with housing, education and inheritance, and pensioners can fairly say they paid in for decades on the terms they were offered. The generational ledger is murkier than the slogan.

The case for keeping calm

The most influential argument against alarm came from Olivier Blanchard, a former chief economist of the IMF, in his 2019 presidential lecture to the American Economic Association. When the interest rate a government pays stays below the economy’s growth rate, debt can shrink relative to GDP more or less by itself, and Blanchard argued that this situation “is more the historical norm than the exception”. His bluntest line: “public debt may have no fiscal cost.”

Japan is the living example the calm camp points to. Its debt is the highest in the advanced world, yet last year the effective interest rate on it was “only 0.7 percent” while the economy expanded by 4.5%, the IMF economists note. Long maturities, debt held mostly at home in its own currency, and sizeable public assets on the other side of the ledger all help explain why the crisis keeps not arriving.

Then there is the optimists’ wildcard: technology. If AI makes workers markedly more productive, it would grow the economy, the bottom half of the debt-to-GDP ratio, rather than shrink the debt itself. Researchers at Yale’s Budget Lab modelled scenarios this year in which exactly that trims America’s debt, while stressing that they are illustrations, not forecasts, and that generous support for the workers AI displaces could cancel out the gain. The early data are intriguing: U.S. labour productivity grew at a 3.6% annualised pace in the third quarter, though nobody can yet say how much of that is down to AI.

Could AI be the Hail Mary? Markets have just grown less sure. After the Democrats won control of both houses of Congress in this month’s U.S. midterms, AI-linked shares slid sharply on fears of tougher rules on data centres, the very infrastructure the bet rests on. Others point out that a divided Washington tends to pass fewer sweeping laws, not more. Is this a real speed bump for AI, or a market getting ahead of itself?
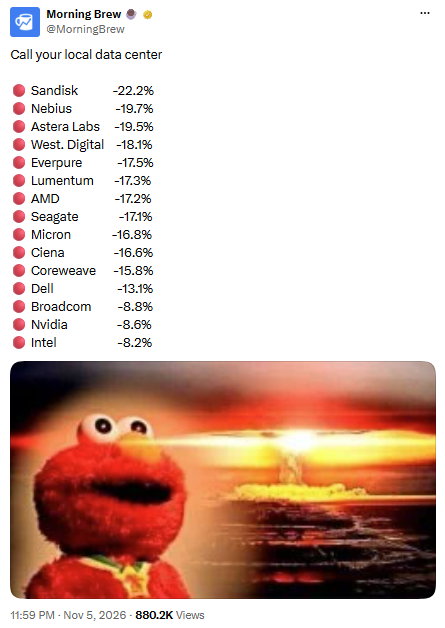
Source: Morning Brew

The case for worry

Every one of those arguments comes with fine print, often written by the same people. Blanchard was careful to say he was not arguing for more public debt, and he flagged the risk that investors can suddenly start demanding a premium on debt they view as risky, a shift that can become self-fulfilling. That is not a bad description of what France’s bond market did this autumn.

The IMF’s Japan economists end on a warning of their own: “Japan’s debt remains exceptionally high, and long-term pressures from aging and higher interest rates are real.” Interest payments there are “poised to roughly double from 2025 to 2031”.

And the cushion of cheap money has been thinning. U.S. interest spending rose 11% in the latest fiscal year, which the CBO put down to a larger debt and higher long-term interest rates. The IMF’s own stress test suggests global debt could reach about 117% of GDP within three years in a bad scenario. If the interest rate starts to outrun growth, Blanchard’s comforting arithmetic runs in reverse. Will it? The honest answer is that nobody can say how long the gap stays open.

Not the number, the situation

Our read is this: the number isn’t unprecedented. The situation might be.

The level has been seen before, by Britain twice and by America once. What hasn’t been seen is this level reached in peacetime, across most of the rich world at once, with populations ageing and no war ending to give the economy room. In the past, the bill always landed somewhere: on taxpayers through austerity, on savers through inflation, on lenders through default, or, in the lucky cases, on nobody at all, because growth made it shrink.

So perhaps the useful question isn’t “is this unprecedented?” but “who pays this time?” The student in Créteil? The retiree in Lyon? The saver whose bank deposit earns less than inflation? Nobody has announced the answer, and perhaps nobody will, which is precisely what makes the quiet option so tempting.

What would change our minds? A rich democracy reforming its pension and healthcare promises without the street catching fire. Growth that outruns interest rates for years, not quarters. Or AI turning out to be the productivity miracle its boosters promise. Any of those would turn “unprecedented” into a word for good news, and that really would be a first.

Contagion ends with a flashback. After two hours of chaos, the last scene jumps back to “Day 1” to show how it all began: a bulldozer, a bat, a pig, a handshake. Nobody noticed at the time, because nothing about it looked unprecedented. Which of today’s small, ordinary decisions will turn out to be our Day 1?


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


On a recent flight from Jakarta to Hong Kong, one of our colleagues picked a film more or less at random: Contagion, Steven Soderbergh’s 2011 thriller about a virus that jumps from a bat to a pig to a person. Watched in 2026, it plays like a home video of 2020. What stays with you isn’t the virus but the panic: the queues, the stripped shelves, the people who have never seen anything like it and have no playbook.

Source: Warner Brothers

It took her straight back to that spring, when the whole world seemed to reach for the same word. Google searches for “unprecedented” hit a record in April 2020, nearly six times their 2019 average. Even Oxford gave up on a single word of the year and called its 2020 report Words of an Unprecedented Year.

Source: Google Trends, monthly worldwide web-search interest in “unprecedented”, January 2004 to November 2026 (November partial), downloaded 5 November 2026. 100 = the peak month; the index is relative, not a count of searches.

And the word never quite went away. Every year since has averaged above 2019, and this year searches are running at about 1.7 times that level.

By the time the plane landed, though, the thing on our colleague’s mind wasn’t a virus. It was debt, which has been hard to avoid in the headlines this year. In August the U.S. national debt passed $40 trillion, a figure the Associated Press called “unprecedented”. In April the IMF warned that global government debt is on track to reach 100% of GDP by 2029, “a level previously reached only in the aftermath of World War II”. And in late October, new projections from the Congressional Budget Office had America paying around $20 trillion in interest over the next decade.

Which left her with a question for the rest of the trip. Will we look back on this year and call this debt unprecedented? Or is “unprecedented” simply what we say when we’ve forgotten the precedents?

A word that tells you how it feels

It’s an odd word to lean on so hard. Strictly, “unprecedented” is a claim about history: this has never happened before. In practice we use it to describe a feeling: we have never seen this before. Those are two very different statements, and the gap between them is where a lot of bad forecasts live.

Economists Carmen Reinhart and Kenneth Rogoff spent years mapping that gap. Their 2009 history of financial crises, spanning eight centuries of defaults, bank runs and inflations, carries a title that reads like a warning label: This Time Is Different. Their point, roughly, is that the phrase tends to be said loudest just before it turns out not to be true.

So let’s do the thing the word skips. Let’s check.

On paper, we’ve been here before

Start with America. U.S. federal debt held by the public was about 97% of GDP in the second quarter of this year. In 1946, at the end of the Second World War, it was 106%. By that yardstick America is close to its own record, but not past it.

Britain makes today’s numbers look almost modest. According to the UK’s Office for Budget Responsibility, British government debt was close to 180% of GDP at Waterloo in 1815, and hit 249% at the end of the Second World War, an all-time high. Today Britain’s public sector net debt stands at about 94% of GDP, a level the Office for National Statistics says was last seen in the early 1960s. Japan, meanwhile, carries gross government debt of about 200% of GDP this year, roughly double the G7 average, according to IMF estimates.

Sources: UK Office for Budget Responsibility (Britain, 1815 and 1945); Office for National Statistics, public sector net debt, end-September 2026 (Britain today); U.S. Office of Management and Budget via FRED, series FYPUGDA188S (U.S. 1946) and FYGFGDQ188S (U.S., second quarter of 2026), debt held by the public; IMF World Economic Outlook, October 2026 (Japan, 2026 estimate of gross general government debt). Definitions differ across countries; figures are approximate.

High debt hasn’t always meant disaster, either. A St. Louis Fed analysis points out that Britain’s debt stayed above 120% of GDP from the 1780s until the 1850s, decades that overlap with its Industrial Revolution, and concludes that “it cannot be asserted” that the debt held back growth. At both of its great peaks, the British government “did not need to offer abnormally large yields to attract lenders”.

On the level alone, then, the honest answer is no. Not unprecedented. Which raises a better question: if this has happened before, how did it end, and who paid?

Who paid last time

Often, nobody you could point to. After 1815, Britain didn’t so much repay its debt as outgrow it. With no major wars and a booming economy, debt fell to 29% of GDP by 1913, the OBR notes. It took almost a century, but a bigger economy simply made the old debt look smaller.

Post-war America shrank its debt much faster, from 106% of GDP in 1946 to about 22% by 1974. Growth did a lot of the work, but not all of it. Between 1945 and 1980, real interest rates in advanced economies were negative “roughly half of the time”, according to Reinhart and M. Belen Sbrancia. Savers who held government bonds earned less than inflation, year after year, and the difference whittled the debt down by 3% to 4% of GDP a year in the U.S. and Britain, they estimate.

Economists call this financial repression. It needs no vote and makes no headlines, which is either its genius or its problem, depending on whether you are the government or the saver.

Source: U.S. Office of Management and Budget, via Federal Reserve Bank of St. Louis (FRED series FYPUGDA188S), retrieved 5 November 2026.

Others paid in plain sight. Greece cut spending and raised taxes under its bailout programmes in the 2010s, and by 2013 its economy had shrunk for 20 quarters in a row. Then there is default, which Reinhart and Rogoff’s book is crowded with, and which every government insists it will never need. History has a habit of filing “never” under “not yet”.

So what’s actually new?

This is where the word starts to earn its keep. Almost every great debt peak in the history books was a war debt. Wars end. The spending stops, the soldiers come home and go to work, and the economy grows into the bill.

Today’s debt wasn’t built by a war, so there is no peace deal coming to switch the spending off. Read the IMF’s line again: 100% of GDP is a level “previously reached only in the aftermath of World War II”. This time there is no aftermath to grow out of. Much of the borrowing goes to pensions and healthcare for ageing populations, commitments that tend to grow rather than end, and more and more of it goes to interest on the borrowing itself.

In the fiscal year that ended in September, the U.S. government spent $1.14 trillion on net interest, more than the $916 billion the Defense Department spent on the military, while running a deficit of about $2 trillion, according to the Congressional Budget Office.

Source: Congressional Budget Office, Monthly Budget Review: September 2026 (8 October 2026), Table 3.
Fiscal years end 30 September.

France is where these strands have knotted together. Students began protesting in mid-September at a high school in Créteil, outside Paris, over teacher shortages, overcrowded classrooms and dilapidated buildings, just as the government was preparing a 2027 budget built on spending restraint and tax measures, including a public-sector pay freeze and limits on pension increases.

Source: Financial Times

After nationwide demonstrations on 17 October, with shops looted in Paris, Marseille, Lyon and Bordeaux, police arrested at least 1,800 people across the country. Four days later, France’s 10-year borrowing cost crossed 5%, its highest since 2002. Finance minister Roland Lescure had already summed up the budget in September: “Nous n’avons plus de gras.” We have no fat left.

The bond market had been saying something similar for a while. For most of the past decade France borrowed far more cheaply than Italy or Greece. On monthly averages, it has paid more than Greece every month since June, and by the summer it had edged above Italy too.

Source: OECD long-term interest rates, via Federal Reserve Bank of St. Louis (FRED series IRLTLT01FRM156N, IRLTLT01ITM156N, IRLTLT01GRM156N, IRLTLT01DEM156N), retrieved 5 November 2026. Latest data: September 2026 (Italy: August 2026).

It is tempting to draw a straight line from there to the second half of Contagion: a squeeze, a promise that can’t be kept, a street on fire. It is tempting, too, to call it a generational bargain in which the old vote, the young pay and the bill has finally arrived. Is that fair? Partly, perhaps. But money flows both ways between generations, through parents’ help with housing, education and inheritance, and pensioners can fairly say they paid in for decades on the terms they were offered. The generational ledger is murkier than the slogan.

The case for keeping calm

The most influential argument against alarm came from Olivier Blanchard, a former chief economist of the IMF, in his 2019 presidential lecture to the American Economic Association. When the interest rate a government pays stays below the economy’s growth rate, debt can shrink relative to GDP more or less by itself, and Blanchard argued that this situation “is more the historical norm than the exception”. His bluntest line: “public debt may have no fiscal cost.”

Japan is the living example the calm camp points to. Its debt is the highest in the advanced world, yet last year the effective interest rate on it was “only 0.7 percent” while the economy expanded by 4.5%, the IMF economists note. Long maturities, debt held mostly at home in its own currency, and sizeable public assets on the other side of the ledger all help explain why the crisis keeps not arriving.

Then there is the optimists’ wildcard: technology. If AI makes workers markedly more productive, it would grow the economy, the bottom half of the debt-to-GDP ratio, rather than shrink the debt itself. Researchers at Yale’s Budget Lab modelled scenarios this year in which exactly that trims America’s debt, while stressing that they are illustrations, not forecasts, and that generous support for the workers AI displaces could cancel out the gain. The early data are intriguing: U.S. labour productivity grew at a 3.6% annualised pace in the third quarter, though nobody can yet say how much of that is down to AI.

Could AI be the Hail Mary? Markets have just grown less sure. After the Democrats won control of both houses of Congress in this month’s U.S. midterms, AI-linked shares slid sharply on fears of tougher rules on data centres, the very infrastructure the bet rests on. Others point out that a divided Washington tends to pass fewer sweeping laws, not more. Is this a real speed bump for AI, or a market getting ahead of itself?

Source: Morning Brew

The case for worry

Every one of those arguments comes with fine print, often written by the same people. Blanchard was careful to say he was not arguing for more public debt, and he flagged the risk that investors can suddenly start demanding a premium on debt they view as risky, a shift that can become self-fulfilling. That is not a bad description of what France’s bond market did this autumn.

The IMF’s Japan economists end on a warning of their own: “Japan’s debt remains exceptionally high, and long-term pressures from aging and higher interest rates are real.” Interest payments there are “poised to roughly double from 2025 to 2031”.

And the cushion of cheap money has been thinning. U.S. interest spending rose 11% in the latest fiscal year, which the CBO put down to a larger debt and higher long-term interest rates. The IMF’s own stress test suggests global debt could reach about 117% of GDP within three years in a bad scenario. If the interest rate starts to outrun growth, Blanchard’s comforting arithmetic runs in reverse. Will it? The honest answer is that nobody can say how long the gap stays open.

Not the number, the situation

Our read is this: the number isn’t unprecedented. The situation might be.

The level has been seen before, by Britain twice and by America once. What hasn’t been seen is this level reached in peacetime, across most of the rich world at once, with populations ageing and no war ending to give the economy room. In the past, the bill always landed somewhere: on taxpayers through austerity, on savers through inflation, on lenders through default, or, in the lucky cases, on nobody at all, because growth made it shrink.

So perhaps the useful question isn’t “is this unprecedented?” but “who pays this time?” The student in Créteil? The retiree in Lyon? The saver whose bank deposit earns less than inflation? Nobody has announced the answer, and perhaps nobody will, which is precisely what makes the quiet option so tempting.

What would change our minds? A rich democracy reforming its pension and healthcare promises without the street catching fire. Growth that outruns interest rates for years, not quarters. Or AI turning out to be the productivity miracle its boosters promise. Any of those would turn “unprecedented” into a word for good news, and that really would be a first.

Contagion ends with a flashback. After two hours of chaos, the last scene jumps back to “Day 1” to show how it all began: a bulldozer, a bat, a pig, a handshake. Nobody noticed at the time, because nothing about it looked unprecedented. Which of today’s small, ordinary decisions will turn out to be our Day 1?


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


Imagine your landlord tells you today that your rent will go up 10% next year. Nothing in your bank account has changed yet, but you’ve probably started cutting back already: fewer dinners out, the holiday pushed back a few months. A promise about tomorrow has changed what you do today.

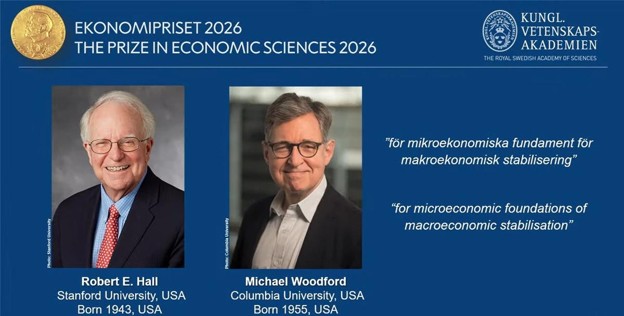
That, in one paragraph, is what this year’s Nobel Prize in economics is about. On October 12, the prize went to two American economists, Robert Hall of Stanford University and Michael Woodford of Columbia University.

They showed how our expectations about the future drive the economy in the present, and how governments and central banks can use that to soften booms and busts.

Source: The Hindu

The timing could hardly be more ironic. Woodford’s best-known idea is that central banks should explain how they think and what they plan to do. In the same year his work won the prize, U.S. Federal Reserve chair Kevin Warsh stopped doing exactly that. “I’m not in the forward guidance business,” he told reporters.

Is the Fed throwing away a Nobel-winning idea? Warsh has his reasons, and they deserve a hearing. But by the laureate’s own standard, the Fed hasn’t just gone quiet. It has yet to replace what it took away.

Start with people, not statistics

Before the 1970s, policymakers steered the economy with rules of thumb drawn from past data, such as the idea that a little more inflation buys a little less unemployment. Then the oil shocks of the 1970s delivered high inflation and high unemployment at the same time, and the rules stopped working. As a member of the prize committee put it at the announcement, the old recipe “worked well — until it didn’t.”

Hall and Woodford rebuilt the thinking from the ground up. Instead of asking how the statistics moved together, they asked what real households and businesses decide, and why.

Hall looked at households. People spend according to what they expect to earn over time, which is why a permanent pay rise gets spent far more readily than a one-off bonus. Hall showed the catch: if spending already reflects expectations, it only shifts when news surprises us, which makes it very hard to forecast.

Woodford looked at businesses.

Picture a café owner who reprints her menu once a year. If she expects milk, rent and her rivals’ prices to rise next year, she raises her prices now, before those costs arrive. Multiply her by millions of businesses and expected inflation turns into real inflation.

Now flip it around. If she trusts that the central bank will keep inflation in check, she has no reason to raise prices early. That’s why, in the committee’s words, central banks should offer “clear and credible communication about how they reason and what they plan to do.”

How a promise moves your mortgage

This is where it reaches your wallet. Mortgages and business loans are largely priced on where people expect the Fed’s rate to be over the next few years. So when the Fed cut rates to near zero in 2008 and couldn’t go lower, it used words instead, promising in 2011 to keep rates low “at least through mid-2013.” That’s forward guidance, and from then on the Fed only got chattier.


Why the new Fed chair might want to say less

Warsh, who took office on May 22, doesn’t argue that words are unimportant. His complaint is that they became too important. When the Fed hints at everything, investors stop thinking for themselves and simply repeat the Fed’s view back to it. “When all the financial markets are doing is reflecting back what we’ve said,” he said in June, “then we’re taking the most important source of information and we’re being blind to it.”

He also has a recent example to point to. In March 2021 the Fed called rising prices “transitory” and signalled no rate rises until at least 2024. By June 2022, U.S. consumer prices were up 9.1% from a year earlier, the biggest jump in four decades, and the Fed was raising rates three-quarters of a point at a time. Warsh told the U.S. Senate in April that the Fed’s forecasts from that period “compounded” its mistakes.

His argument is that once a central bank has told the world rates will stay low, it becomes slow to change its mind, and then has to catch up fast.

So Warsh has gone quiet. At his first meeting in June, the Fed’s statement shrank from 341 words to 132. He dropped the forward guidance and declined to add his own dot to the forecast chart. In September the Fed raised rates by a quarter point, to 3.75–4%, and Warsh gave no hint of what comes next.

Why the irony cuts deeper

There are really two kinds of promise a central bank can make. One is an itinerary, like the 2011 promise to keep rates low until at least mid-2013. The other is a rulebook, like the one the Fed switched to in December 2012: rates would stay near zero at least as long as unemployment stayed above 6.5% and inflation stayed under control.

Woodford himself preferred the rulebook. In a 2014 interview with the Minneapolis Fed, he called date-based promises “a less satisfactory way to try to shape expectations about future policy.” Warsh, for his part, says he wants to “look outside the window” rather than follow a script.

Warsh has torn up the itinerary. His rulebook, so far, is one sentence: the Fed must “be confident that underlying inflation is moving to our objective, clearly and at sufficient speed.” That’s a rule, but a loose one.

And if markets are meant to predict the Fed by watching the economy, they need to know which numbers matter. Yet Warsh told reporters in September, “I’m not a data-point-dependent guy,” adding that trends matter more. So what, exactly, should investors be watching?

Source: The Hill

Woodford was no fan of date-stamped promises either. The problem is that the Fed has dropped them without yet offering the clear rulebook he argued should take their place.

Our read: a bet on expectations with this little to anchor them is exactly the kind of gamble the prize-winning work suggests is risky.

So far, markets are making their own calls

Without hints, markets do their own forecasting. The two-year U.S. Treasury yield, a good gauge of where investors think Fed rates are heading, rose from 4.05% on the eve of Warsh’s first decision to 4.77% by October 15, against a Fed that has hiked by just 0.25 percentage points. Investors are betting on more rate rises than the Fed has delivered.

Longer-term rates have climbed too: the 10-year yield, which most U.S. mortgage rates follow, is up about two-thirds of a point, and the 30-year about half a point. That is what critics of a quieter Fed warned about. Market strategist George Pearkes told the Associated Press that guidance had “served to suppress volatility and anchor market expectations,” and estimated that mortgage rates could end up about a quarter point higher without it.

But long-term rates also move with growth, inflation and government borrowing, and Warsh himself points to a stronger economy and more competition for capital.

Despite that, history suggests surprises are costly. When the Fed issued its very first post-meeting statement in February 1994, announcing a rate rise few expected, the Dow fell 2.4% that day. The real test, though, will be the next crisis, when rates may be near zero and words are the only tool left. Will a Fed that has trained everyone to expect silence be believed when it suddenly needs to speak?

The Fed’s communications review, due by year-end, will be the first clue to whether this is healthy independence or nervous guessing.

Back to your landlord, then. Would you rather he told you next year’s rent, or told you exactly how he decides it? The Fed has stopped doing the first. It hasn’t yet done the second, beyond a single sentence. Until it does, we’re all part of the experiment: will a quieter Fed teach us to think for ourselves, or just leave us guessing?


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


Imagine your landlord tells you today that your rent will go up 10% next year. Nothing in your bank account has changed yet, but you’ve probably started cutting back already: fewer dinners out, the holiday pushed back a few months. A promise about tomorrow has changed what you do today.

That, in one paragraph, is what this year’s Nobel Prize in economics is about. On October 12, the prize went to two American economists, Robert Hall of Stanford University and Michael Woodford of Columbia University.

They showed how our expectations about the future drive the economy in the present, and how governments and central banks can use that to soften booms and busts.

Source: The Hindu

The timing could hardly be more ironic. Woodford’s best-known idea is that central banks should explain how they think and what they plan to do. In the same year his work won the prize, U.S. Federal Reserve chair Kevin Warsh stopped doing exactly that. “I’m not in the forward guidance business,” he told reporters.

Is the Fed throwing away a Nobel-winning idea? Warsh has his reasons, and they deserve a hearing. But by the laureate’s own standard, the Fed hasn’t just gone quiet. It has yet to replace what it took away.

Start with people, not statistics

Before the 1970s, policymakers steered the economy with rules of thumb drawn from past data, such as the idea that a little more inflation buys a little less unemployment. Then the oil shocks of the 1970s delivered high inflation and high unemployment at the same time, and the rules stopped working. As a member of the prize committee put it at the announcement, the old recipe “worked well — until it didn’t.”

Hall and Woodford rebuilt the thinking from the ground up. Instead of asking how the statistics moved together, they asked what real households and businesses decide, and why.

Hall looked at households. People spend according to what they expect to earn over time, which is why a permanent pay rise gets spent far more readily than a one-off bonus. Hall showed the catch: if spending already reflects expectations, it only shifts when news surprises us, which makes it very hard to forecast.

Woodford looked at businesses.

Picture a café owner who reprints her menu once a year. If she expects milk, rent and her rivals’ prices to rise next year, she raises her prices now, before those costs arrive. Multiply her by millions of businesses and expected inflation turns into real inflation.

Now flip it around. If she trusts that the central bank will keep inflation in check, she has no reason to raise prices early. That’s why, in the committee’s words, central banks should offer “clear and credible communication about how they reason and what they plan to do.”

How a promise moves your mortgage

This is where it reaches your wallet. Mortgages and business loans are largely priced on where people expect the Fed’s rate to be over the next few years. So when the Fed cut rates to near zero in 2008 and couldn’t go lower, it used words instead, promising in 2011 to keep rates low “at least through mid-2013.” That’s forward guidance, and from then on the Fed only got chattier.


Why the new Fed chair might want to say less

Warsh, who took office on May 22, doesn’t argue that words are unimportant. His complaint is that they became too important. When the Fed hints at everything, investors stop thinking for themselves and simply repeat the Fed’s view back to it. “When all the financial markets are doing is reflecting back what we’ve said,” he said in June, “then we’re taking the most important source of information and we’re being blind to it.”

He also has a recent example to point to. In March 2021 the Fed called rising prices “transitory” and signalled no rate rises until at least 2024. By June 2022, U.S. consumer prices were up 9.1% from a year earlier, the biggest jump in four decades, and the Fed was raising rates three-quarters of a point at a time. Warsh told the U.S. Senate in April that the Fed’s forecasts from that period “compounded” its mistakes.

His argument is that once a central bank has told the world rates will stay low, it becomes slow to change its mind, and then has to catch up fast.

So Warsh has gone quiet. At his first meeting in June, the Fed’s statement shrank from 341 words to 132. He dropped the forward guidance and declined to add his own dot to the forecast chart. In September the Fed raised rates by a quarter point, to 3.75–4%, and Warsh gave no hint of what comes next.

Why the irony cuts deeper

There are really two kinds of promise a central bank can make. One is an itinerary, like the 2011 promise to keep rates low until at least mid-2013. The other is a rulebook, like the one the Fed switched to in December 2012: rates would stay near zero at least as long as unemployment stayed above 6.5% and inflation stayed under control.

Woodford himself preferred the rulebook. In a 2014 interview with the Minneapolis Fed, he called date-based promises “a less satisfactory way to try to shape expectations about future policy.” Warsh, for his part, says he wants to “look outside the window” rather than follow a script.

Warsh has torn up the itinerary. His rulebook, so far, is one sentence: the Fed must “be confident that underlying inflation is moving to our objective, clearly and at sufficient speed.” That’s a rule, but a loose one.

And if markets are meant to predict the Fed by watching the economy, they need to know which numbers matter. Yet Warsh told reporters in September, “I’m not a data-point-dependent guy,” adding that trends matter more. So what, exactly, should investors be watching?

Source: The Hill

Woodford was no fan of date-stamped promises either. The problem is that the Fed has dropped them without yet offering the clear rulebook he argued should take their place.

Our read: a bet on expectations with this little to anchor them is exactly the kind of gamble the prize-winning work suggests is risky.

So far, markets are making their own calls

Without hints, markets do their own forecasting. The two-year U.S. Treasury yield, a good gauge of where investors think Fed rates are heading, rose from 4.05% on the eve of Warsh’s first decision to 4.77% by October 15, against a Fed that has hiked by just 0.25 percentage points. Investors are betting on more rate rises than the Fed has delivered.

Longer-term rates have climbed too: the 10-year yield, which most U.S. mortgage rates follow, is up about two-thirds of a point, and the 30-year about half a point. That is what critics of a quieter Fed warned about. Market strategist George Pearkes told the Associated Press that guidance had “served to suppress volatility and anchor market expectations,” and estimated that mortgage rates could end up about a quarter point higher without it.

But long-term rates also move with growth, inflation and government borrowing, and Warsh himself points to a stronger economy and more competition for capital.

Despite that, history suggests surprises are costly. When the Fed issued its very first post-meeting statement in February 1994, announcing a rate rise few expected, the Dow fell 2.4% that day. The real test, though, will be the next crisis, when rates may be near zero and words are the only tool left. Will a Fed that has trained everyone to expect silence be believed when it suddenly needs to speak?

The Fed’s communications review, due by year-end, will be the first clue to whether this is healthy independence or nervous guessing.

Back to your landlord, then. Would you rather he told you next year’s rent, or told you exactly how he decides it? The Fed has stopped doing the first. It hasn’t yet done the second, beyond a single sentence. Until it does, we’re all part of the experiment: will a quieter Fed teach us to think for ourselves, or just leave us guessing?


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


This summer, some of the most sought-after dumplings in the world couldn’t be eaten. They come in little steamer baskets, they collapse under your thumb, and then, slowly, they puff themselves back into shape. The New Yorker counted fake-dumpling squishies among the defining children’s crazes of summer 2026. Plenty of adults are buying them too.

Source: TikTok Andrea Lopez

Squishy toys are having a moment, and not a small one. In Sioux Falls, South Dakota, the staff at Child’s Play Toys started keeping a tally behind the counter of calls from people hunting for them. One Friday evening this April, it reached 45; the owner promised everyone coffee if it hit 50. “I have never seen anything else like this in my 16 years of business,” she told SiouxFalls.Business in April.

A whole menu of squish

“Squishy” is less a product than a category, and it has more variations than a dim sum menu.

There are the original kawaii squishies from Japan: slow-rising foam shaped like buns, cakes and animals, which had their first global moment around 2017. There are gel-filled stress balls, led by the NeeDoh range from Massachusetts toymaker Schylling. There are mystery dumplings, sold blind in steamer-basket packaging so you don’t know which one you’ve got until you open it. There are squishy butter sticks (yes, really), and softer silicone “taba” squishies shaped like paws, capybaras and strawberries, many of them sold by small makers online.

They feel different, too, which is half the fun. Enthusiasts compare texture and “slow rise” the way coffee people compare roasts: how a squishy gives under your fingers, how long it takes to recover, whether it is jelly-bouncy, butter-soft, or even crunchy.

The rush

What they share this year is scarcity. Schylling’s chief executive said in April that the company had sold a full year of NeeDoh inventory in the first nine weeks of 2026, and it stopped taking on new stockists. In Sioux Falls, a sporting-goods store that hoped a shipment of mystery dumplings would last a month sold out in two days. A candy shop nearby sold more than 300 in a single weekend.

And where there is scarcity, there is a market. Shops ration purchases to two per customer. Parents trade with other parents: one Baltimore mother bought 15 squishies from other mums because they were all her daughter wanted for her 13th birthday. Collectors chase rare colours and glitter editions, and blind packaging means duplicates, which means swapping. Copies have followed close behind. In July, trading standards officers in one Welsh council area reported that traders had surrendered 224 unsafe squishy toys, from viral dumplings to butter sticks, many of which failed toy-safety rules.

How did a squeeze toy end up with a black market?

Source: Youtube Nisha Noelle

We’ve been here before

If this feels familiar, it should. Toy crazes tend to follow the same arc: cheap, tactile, made for the camera, briefly scarce, then everywhere.

Remember the great glue shortage? In late 2016, children discovered homemade slime: glue, water, borax and food colouring. Sales of Elmer’s school glue more than doubled that December, shops ran out, and kids started selling their creations at school.

Squishies themselves have been round the cycle once already. After the first foam-squishy wave, Denmark’s environmental protection agency tested 12 of them in 2018, found they gave off harmful chemicals and had them pulled from shelves (a European toy-industry body disputed the testing method). The year before, fidget spinners went from nowhere to all 20 of Amazon’s top-selling toys by May 2017; by July, Google searches had fallen to 15% of their peak.

And then there was Labubu, the grinning monster that sent fans queuing outside shops across Asia in 2025. Its blind boxes retailed for about CNY 99, yet the rarest figure in one popular series fetched more than CNY 4,500 on a resale platform in mid-June. After repeated restocks, it was going for about CNY 540 by the end of the year. As a Pop Mart executive put it during the cooldown, “It’s like concert tickets.”

So are squishies just the next Labubu? Perhaps. But that is the less interesting question.

The case for the squishy

Before we get too clever about it, the toy deserves to be taken seriously. Who hasn’t clicked a pen through a long meeting? Sensory and fidget toys have long been used to help children and adults focus and manage anxiety. Shop owners describe customers with arthritis buying them, professionals squeezing them on calls, and parents who say their children sit with a bucket of squishies in the evening instead of a phone.

There is a sting, too. In Sioux Falls, a volunteer at a mental-health nonprofit’s gift shop, which has stocked these toys for years, noticed that some customers with anxiety now worry about getting their squishy, and about breaking it. People who relied on them long before they were fashionable are struggling to find one. A calming object, once it becomes scarce, can turn into a small source of stress.

The $15 barometer

What struck us most, though, was the timing. Look at who is queuing, and in what kind of year.

By most measures, Americans have rarely felt worse. The University of Michigan’s consumer sentiment index fell to 44.8 in May, the lowest reading since its records began in 1952. In September, the Conference Board’s confidence index dropped to 81.9, its lowest since 2014. Euromonitor International’s Top Global Consumer Trends 2026 report, published last November, found that nearly 58% of people worldwide feel moderate to extreme stress every day.

Yet the toy aisle is having a record year. Sales at US hobby, toy and game stores reached $13.9 billion in the first seven months of 2026, up 23% on a year earlier and the highest for that stretch in data going back to 1992. And overall, inflation-adjusted consumer spending was still about 2.6% higher in August than a year before.

Why would the gloomiest consumers on record be emptying the toy shelves?

Our read is that the toy aisle is telling us something the surveys can’t. When the big things feel out of reach (a first home, a secure job, a quieter news cycle), people don’t stop spending. They shrink the size of their certainty. A $15 squishy is a small, sure thing in an unsure year: it costs little, it works every time, and nobody can raise its interest rate.

This is an old idea in a new shape. In 2001, Leonard Lauder of Estée Lauder noticed lipstick sales rising in the post-9/11 downturn and called it the “lipstick index”. The sociologist Juliet Schor had described the same pull towards small, compensating luxuries a few years earlier.

We should be honest about its limits. Economists have long found the evidence for the lipstick effect mixed; lipstick sales actually fell for several years after 2007. Toy crazes also happen in good times: fidget spinners swept the world in a year of steady growth. And the toy-store figures are not adjusted for inflation or tariffs, and include hobby and game shops as well as squishies. So treat this as a barometer, not a forecast.

For anyone in the queue, there is a smaller lesson inside the bigger one. The calm was never in the rare colour. The plain squishy in your drawer squeezes exactly the same.

The most honest economic indicator of 2026 might cost $15 and fit in your palm. The question is whether we are reading it, or just squeezing it.


Tara Mulia

For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


This summer, some of the most sought-after dumplings in the world couldn’t be eaten. They come in little steamer baskets, they collapse under your thumb, and then, slowly, they puff themselves back into shape. The New Yorker counted fake-dumpling squishies among the defining children’s crazes of summer 2026. Plenty of adults are buying them too.

Source: TikTok Andrea Lopez

Squishy toys are having a moment, and not a small one. In Sioux Falls, South Dakota, the staff at Child’s Play Toys started keeping a tally behind the counter of calls from people hunting for them. One Friday evening this April, it reached 45; the owner promised everyone coffee if it hit 50. “I have never seen anything else like this in my 16 years of business,” she told SiouxFalls.Business in April.

A whole menu of squish

“Squishy” is less a product than a category, and it has more variations than a dim sum menu.

There are the original kawaii squishies from Japan: slow-rising foam shaped like buns, cakes and animals, which had their first global moment around 2017. There are gel-filled stress balls, led by the NeeDoh range from Massachusetts toymaker Schylling. There are mystery dumplings, sold blind in steamer-basket packaging so you don’t know which one you’ve got until you open it. There are squishy butter sticks (yes, really), and softer silicone “taba” squishies shaped like paws, capybaras and strawberries, many of them sold by small makers online.

They feel different, too, which is half the fun. Enthusiasts compare texture and “slow rise” the way coffee people compare roasts: how a squishy gives under your fingers, how long it takes to recover, whether it is jelly-bouncy, butter-soft, or even crunchy.

The rush

What they share this year is scarcity. Schylling’s chief executive said in April that the company had sold a full year of NeeDoh inventory in the first nine weeks of 2026, and it stopped taking on new stockists. In Sioux Falls, a sporting-goods store that hoped a shipment of mystery dumplings would last a month sold out in two days. A candy shop nearby sold more than 300 in a single weekend.

And where there is scarcity, there is a market. Shops ration purchases to two per customer. Parents trade with other parents: one Baltimore mother bought 15 squishies from other mums because they were all her daughter wanted for her 13th birthday. Collectors chase rare colours and glitter editions, and blind packaging means duplicates, which means swapping. Copies have followed close behind. In July, trading standards officers in one Welsh council area reported that traders had surrendered 224 unsafe squishy toys, from viral dumplings to butter sticks, many of which failed toy-safety rules.

How did a squeeze toy end up with a black market?

Source: Youtube Nisha Noelle

We’ve been here before

If this feels familiar, it should. Toy crazes tend to follow the same arc: cheap, tactile, made for the camera, briefly scarce, then everywhere.

Remember the great glue shortage? In late 2016, children discovered homemade slime: glue, water, borax and food colouring. Sales of Elmer’s school glue more than doubled that December, shops ran out, and kids started selling their creations at school.

Squishies themselves have been round the cycle once already. After the first foam-squishy wave, Denmark’s environmental protection agency tested 12 of them in 2018, found they gave off harmful chemicals and had them pulled from shelves (a European toy-industry body disputed the testing method). The year before, fidget spinners went from nowhere to all 20 of Amazon’s top-selling toys by May 2017; by July, Google searches had fallen to 15% of their peak.

And then there was Labubu, the grinning monster that sent fans queuing outside shops across Asia in 2025. Its blind boxes retailed for about CNY 99, yet the rarest figure in one popular series fetched more than CNY 4,500 on a resale platform in mid-June. After repeated restocks, it was going for about CNY 540 by the end of the year. As a Pop Mart executive put it during the cooldown, “It’s like concert tickets.”

So are squishies just the next Labubu? Perhaps. But that is the less interesting question.

The case for the squishy

Before we get too clever about it, the toy deserves to be taken seriously. Who hasn’t clicked a pen through a long meeting? Sensory and fidget toys have long been used to help children and adults focus and manage anxiety. Shop owners describe customers with arthritis buying them, professionals squeezing them on calls, and parents who say their children sit with a bucket of squishies in the evening instead of a phone.

There is a sting, too. In Sioux Falls, a volunteer at a mental-health nonprofit’s gift shop, which has stocked these toys for years, noticed that some customers with anxiety now worry about getting their squishy, and about breaking it. People who relied on them long before they were fashionable are struggling to find one. A calming object, once it becomes scarce, can turn into a small source of stress.

The $15 barometer

What struck us most, though, was the timing. Look at who is queuing, and in what kind of year.

By most measures, Americans have rarely felt worse. The University of Michigan’s consumer sentiment index fell to 44.8 in May, the lowest reading since its records began in 1952. In September, the Conference Board’s confidence index dropped to 81.9, its lowest since 2014. Euromonitor International’s Top Global Consumer Trends 2026 report, published last November, found that nearly 58% of people worldwide feel moderate to extreme stress every day.

Yet the toy aisle is having a record year. Sales at US hobby, toy and game stores reached $13.9 billion in the first seven months of 2026, up 23% on a year earlier and the highest for that stretch in data going back to 1992. And overall, inflation-adjusted consumer spending was still about 2.6% higher in August than a year before.

Why would the gloomiest consumers on record be emptying the toy shelves?

Our read is that the toy aisle is telling us something the surveys can’t. When the big things feel out of reach (a first home, a secure job, a quieter news cycle), people don’t stop spending. They shrink the size of their certainty. A $15 squishy is a small, sure thing in an unsure year: it costs little, it works every time, and nobody can raise its interest rate.

This is an old idea in a new shape. In 2001, Leonard Lauder of Estée Lauder noticed lipstick sales rising in the post-9/11 downturn and called it the “lipstick index”. The sociologist Juliet Schor had described the same pull towards small, compensating luxuries a few years earlier.

We should be honest about its limits. Economists have long found the evidence for the lipstick effect mixed; lipstick sales actually fell for several years after 2007. Toy crazes also happen in good times: fidget spinners swept the world in a year of steady growth. And the toy-store figures are not adjusted for inflation or tariffs, and include hobby and game shops as well as squishies. So treat this as a barometer, not a forecast.

For anyone in the queue, there is a smaller lesson inside the bigger one. The calm was never in the rare colour. The plain squishy in your drawer squeezes exactly the same.

The most honest economic indicator of 2026 might cost $15 and fit in your palm. The question is whether we are reading it, or just squeezing it.


Tara Mulia

For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


Every senior banker, lawyer and engineer you know has a version of the same story. Their first job was mostly grunt work: formatting slides at midnight, checking footnotes, writing code nobody would ever read, summarising documents for someone more important. It was dull, and it was also how they learned. Someone hired them before they knew much and gave them time to get better.

Now picture that work being done in eight seconds by software. The slides are formatted, the footnotes are checked and the summary is decent. For someone looking for a first job, the worry is straightforward: if that work disappears, where do you get the experience employers keep asking for?

Researchers are now trying to measure what is happening. Is AI quietly closing the door on graduates? Or are we blaming a new technology for an old-fashioned hiring slump? Here’s the difficult part: the data points in two directions.

Before we get into the numbers, one thing is worth saying plainly. For the young people living through this, it isn’t a debate. It’s the fortieth application with no reply, the rent that’s due anyway, and the awkward dinner where you explain to your parents why the degree they helped pay for hasn’t turned into a job yet.

Most of them did exactly what they were told to do. The ladder moved anyway.

The Case That AI Is Pulling Up the Ladder

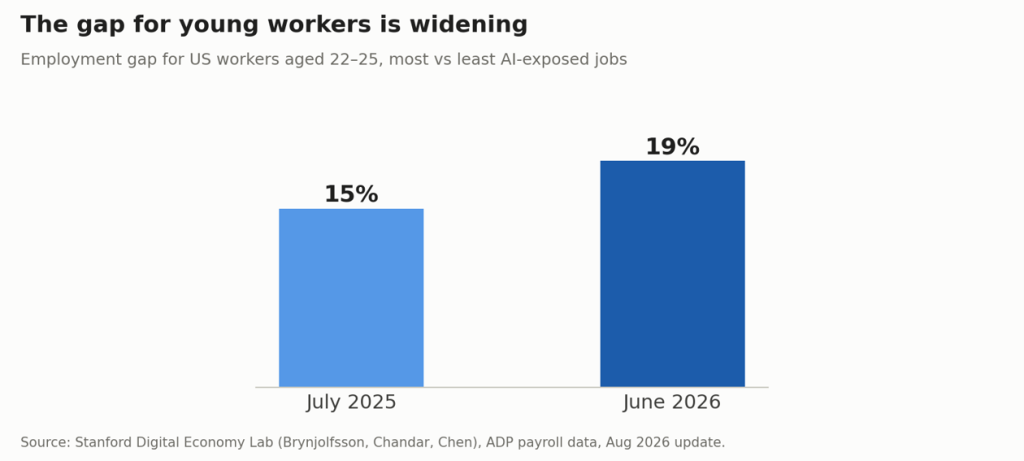
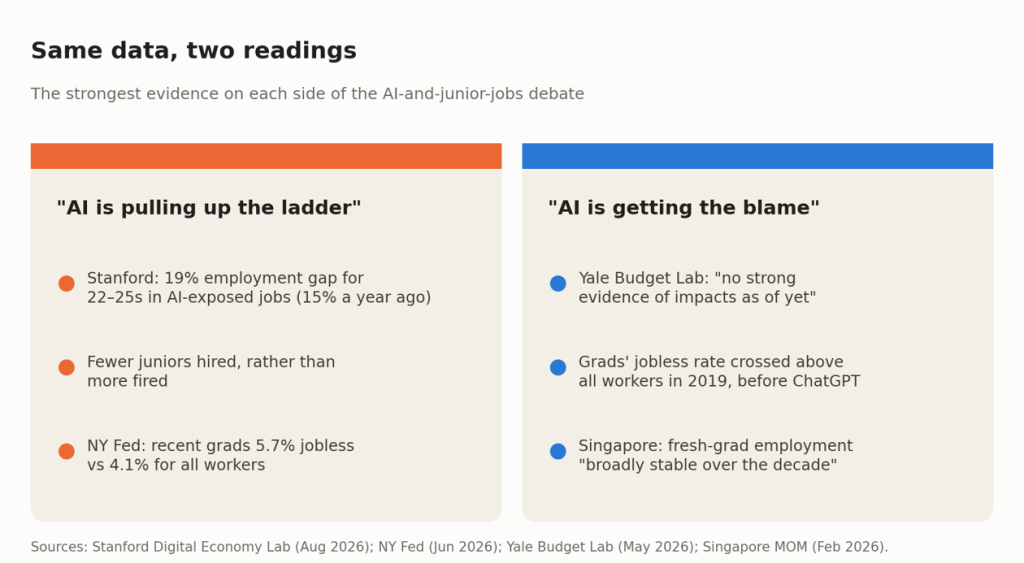
The most-cited evidence comes from Stanford. Economists Erik Brynjolfsson, Bharat Chandar and Ruyu Chen have been tracking payroll data from ADP, one of the biggest payroll processors in the US. In their August 2026 update, workers aged 22 to 25 in the jobs most exposed to AI had a 19% employment gap compared with young workers in less-exposed jobs. A year earlier the gap was 15%.

How it’s happening matters. Companies aren’t firing juniors en masse; they’re hiring fewer of them. The declines are concentrated in roles where AI can do the task outright, like customer service or routine coding, and in work built on “codified” knowledge, the kind you can write down in a manual. Experienced workers, whose value sits in judgment learned on the job, are doing fine or better.

There are louder voices too. In 2025, Anthropic’s chief executive Dario Amodei warned that AI could wipe out half of all entry-level white-collar jobs within five years. (We’ll note the obvious: a company selling AI has reasons to talk up its power. So do its critics have reasons to play it down.)

Why the Class of 2026 Is Worried

The anxiety was hard to miss at this year’s graduation ceremonies.

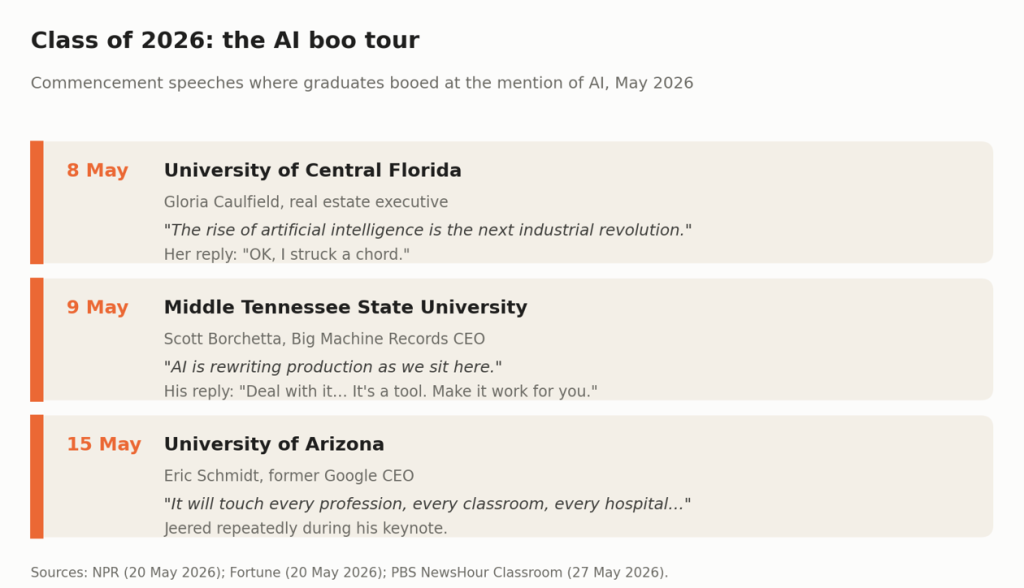
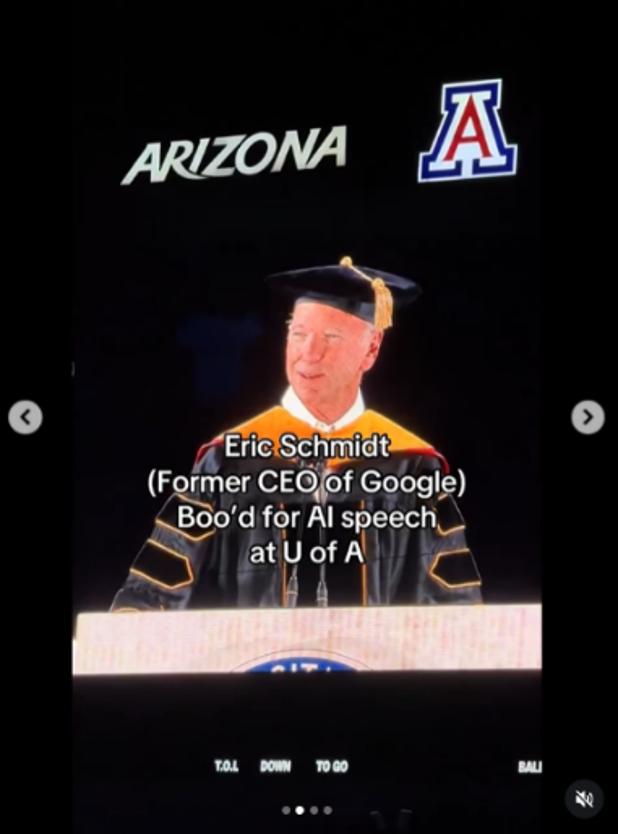
In May, commencement speakers across the US discovered that the fastest way to lose a room of graduates was to praise AI. At the University of Central Florida on 8 May, real estate executive Gloria Caulfield called AI “the next industrial revolution” and was met with boos. “OK, I struck a chord,” she said. The next day at Middle Tennessee State, music executive Scott Borchetta told graduates that “AI is rewriting production as we sit here.” When they booed, he pushed back: “Deal with it… It’s a tool. Make it work for you.” And on 15 May at the University of Arizona, former Google chief executive Eric Schmidt was jeered repeatedly as he told the class that AI “will touch every profession, every classroom, every hospital.”

You can watch a compilation here in PBS NewsHour Classroom, “Shorts: 2026 graduates boo commencement speeches on AI” (27 May 2026, 2m40s), which is embedded from YouTube on the PBS page: https://www.pbs.org/newshour/classroom/daily-news-lessons/2026/05/shorts-2026-graduates-boo-commencement-speeches-on-ai

The boos don’t tell us how many jobs AI has displaced. But we should take the worry seriously. These students have spent years working towards a qualification, often with considerable help and sacrifice from their families. Being told to embrace a technology that might reduce their chances of getting hired offers little reassurance.

Fortune reported a 2025 Harvard Kennedy School poll in which around seven in ten college students said AI threatened their job prospects. We still need to establish how much of the hiring slowdown AI explains. Graduates shouldn’t have to prove the cause before we take their difficulty finding work seriously.

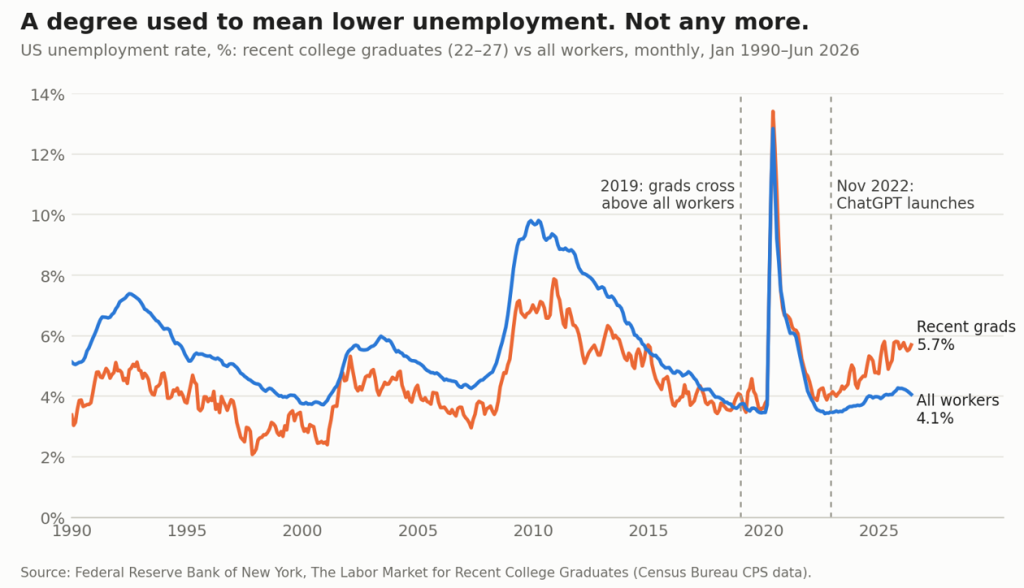
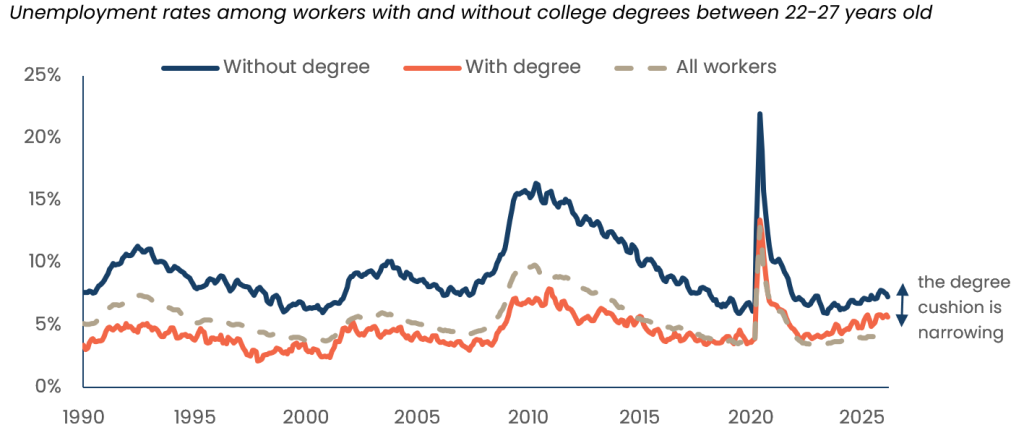
The broader graduate data points the same way. In the US, the New York Fed’s series on recent college graduates shows their unemployment rate at about 5.7% in June 2026, against about 4.1% for all workers. More than four in ten recent grads are underemployed, working in jobs that don’t need a degree.

Read that again: for most of the past 35 years, a fresh degree meant you were less likely to be unemployed than the average worker. That’s no longer true. For anyone who studied hard on the understanding that a degree would help them find work, that is a difficult change to accept.

The Case That AI Is Getting the Blame

Now look at the same chart again, because it also contains the best argument on the other side.

The line for recent grads crossed above the line for all workers in 2019. ChatGPT launched in November 2022. Whatever opened the gap, it started three years before generative AI was a household word.

Researchers at Yale’s Budget Lab have gone looking for AI’s fingerprints in the wider job market and so far haven’t found them. Comparing AI-exposed jobs with unexposed ones, economist Ryan Nunn wrote in May: “When we apply our preferred strategy, we find no strong evidence of impacts as of yet.”

There are plenty of other suspects. Interest rates rose sharply from 2022, and hiring slowed across the economy. US payroll growth averaged only around 20,000 jobs a month over the year to March, according to the Budget Lab, and unemployment crept up from 3.4% in 2023 to 4.3%. Many tech companies over-hired during the pandemic and have spent the years since trimming. When companies stop hiring, the people who feel it first are always the ones trying to get in the door. They’re also the ones with the least savings to wait it out.

The Stanford data itself isn’t all gloom, either. In jobs where AI helps workers rather than replacing them, employment for young people has been flat or rising. So is the problem AI, or the kind of AI a company chooses to deploy?

Even the Stanford authors add a careful caveat: “We do not view this paper, or any single study, as definitive evidence of AI’s labor-market effects.”

Singapore offers a more reassuring data point, though it cannot speak for all of Asia. Singapore’s Manpower Ministry told parliament in February that employment rates for fresh graduates “have remained broadly stable over the decade,” and that AI’s specific impact on entry-level professional jobs “remains uncertain.”

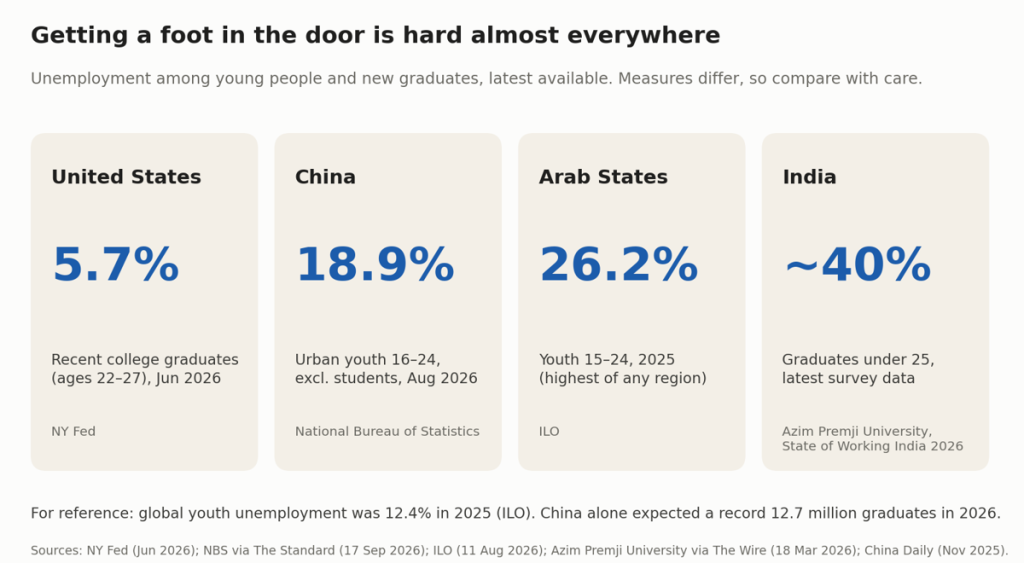
India shows why that distinction matters. Azim Premji University’s State of Working India 2026 report puts unemployment among graduates under 25 at about 39%, using 2023–24 survey data. That figure describes a broader difficulty finding work; it does not establish that AI caused it. For a young person sending out applications, though, the uncertainty about the cause doesn’t make the wait any easier.

Behind those numbers are young people, and the phrases they’ve coined for how it feels.

In China, the “lying flat” meme is often read by older generations as laziness. It is closer to exhaustion: a generation that studied hard, sat the exams and did what was asked, then found the reward wasn’t there. Graduates also joke about “Kong Yiji’s long gown,” after a classic literary character who couldn’t let go of his scholar’s robe even as it stopped doing him any good. For them, the degree they were proud of has become the gown: hard-earned, hard to take off, and no longer opening doors. In India, many young people spend years preparing for competitive government exams, putting their lives on hold for the chance of one secure job.

None of this is young people being picky or soft. It’s what happens when the promise made to them, work hard, get the degree and the job will follow, stops holding. AI is only one thread in that story, and in much of Asia it may not be the main one yet. But for a 24-year-old in her second year of waiting, the cause matters less than the fact that the door still hasn’t opened. As the ILO’s Sukti Dasgupta put it in August, AI’s direct impact on jobs “is still unclear,” but “we must not be complacent and underestimate the risks.”

We’ve Seen Machines Eat Entry-Level Work Before

History offers a useful rhyme, and a warning.

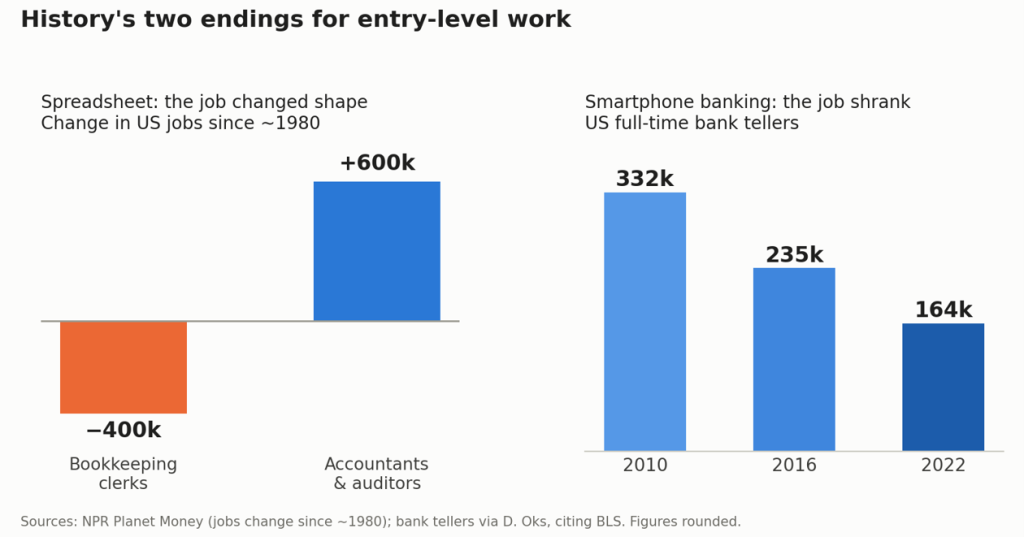
When the spreadsheet arrived around 1980, it wiped out a huge amount of clerical number-crunching. By one widely cited estimate, the US lost around 400,000 bookkeeping and accounting clerk jobs in the decades that followed. But it gained roughly 600,000 accountants and auditors, because cheap calculation created more demand for people who could interpret the numbers.

ATMs were supposed to end bank tellers. Instead, as economist James Bessen found, teller numbers in the US held up for decades: cheaper branches meant banks opened more of them, and tellers shifted from counting cash to selling products.

Then came the smartphone. Once people could bank from their sofa, they stopped visiting branches. Full-time teller jobs fell from about 332,000 in 2010 to about 164,000 in 2022. The ATM automated a task; the phone made the whole place unnecessary.

That’s the real lesson, and it cuts both ways. Technology that does one piece of a junior’s job tends to reshape the job. Technology that removes the reason the job exists is a different story. Which kind is AI? It may be both, depending on the job.

The other warning is timing: the new jobs weren’t always for the same people, and the transition took years. A 23-year-old doesn’t have years. At 23, waiting can mean another year relying on parents who may already be stretched, or taking whatever work pays the bills while the career you trained for feels further away. An eventual recovery doesn’t give that time back.

The Question Worth Asking

Here is where we land. It’s a view, not a verdict.

Alongside the question of how many junior jobs AI is taking, we need to ask how young people will learn to do those jobs. The junior job was never just a job. It was a training programme that companies paid for without calling it one. You learned judgment by doing the dull work under someone who already had it.

If AI does the dull work, the company saves money this year. But where does it get its senior people in 2036? Every firm has an incentive to let someone else train the juniors, and if everyone waits, nobody does it.

Employers need to decide who will do that training and pay for it. Otherwise, graduates are left waiting for a chance that each company expects another to provide.

There’s a second puzzle, and it lands hardest on the graduates themselves. If the new entry-level job is “check the AI’s work,” how do you check work you’ve never learned to do? The old ladder taught you to spot a wrong number by making a few yourself.

A new graduate needs someone experienced to explain why an answer is wrong, and time to learn without being expected to know everything already. What replaces that support?

Some firms are already experimenting with answers: apprenticeships redesigned around AI tools, juniors paired with agents rather than replaced by them, and programmes like Singapore’s graduate traineeships.

What would change our mind? A few things we’re watching:

  • Whether the young-worker gap keeps widening in AI-exposed jobs while overall hiring recovers. That would point more clearly to AI.
  • Whether the grad-versus-all gap narrows as interest rates fall. That would point to the business cycle.
  • What happens in Asia’s graduate data over the next year or two, allowing for the very different starting points across countries.

Until then, a small thought for anyone hiring: the cheapest junior you’ll ever employ is the one who becomes your best senior. The question is whether anyone is still willing to pay for that.

And to anyone graduating into this: the fact that the first rung is harder to find says more about this moment than it does about you. As the ILO’s director-general, Gilbert Houngbo, put it in August: “A generation that cannot find decent work cannot build its future with confidence.” Fixing that is everyone’s job, not only yours.

Who took a chance on you when you were starting out, and who are you taking a chance on now?


Tara Mulia

For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
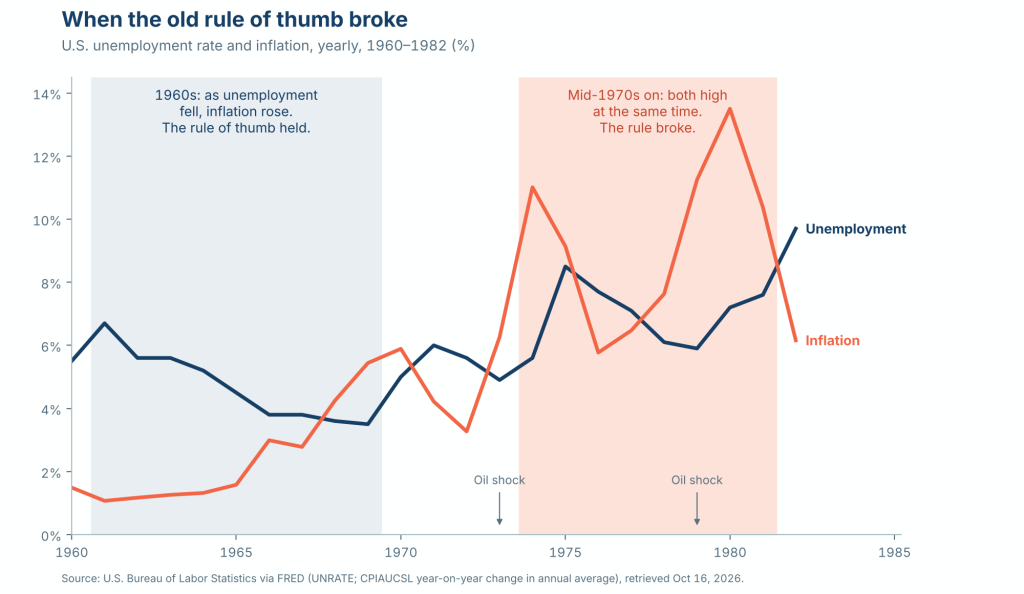


Every senior banker, lawyer and engineer you know has a version of the same story. Their first job was mostly grunt work: formatting slides at midnight, checking footnotes, writing code nobody would ever read, summarising documents for someone more important. It was dull, and it was also how they learned. Someone hired them before they knew much and gave them time to get better.

Now picture that work being done in eight seconds by software. The slides are formatted, the footnotes are checked and the summary is decent. For someone looking for a first job, the worry is straightforward: if that work disappears, where do you get the experience employers keep asking for?

Researchers are now trying to measure what is happening. Is AI quietly closing the door on graduates? Or are we blaming a new technology for an old-fashioned hiring slump? Here’s the difficult part: the data points in two directions.

Before we get into the numbers, one thing is worth saying plainly. For the young people living through this, it isn’t a debate. It’s the fortieth application with no reply, the rent that’s due anyway, and the awkward dinner where you explain to your parents why the degree they helped pay for hasn’t turned into a job yet.

Most of them did exactly what they were told to do. The ladder moved anyway.

The Case That AI Is Pulling Up the Ladder

The most-cited evidence comes from Stanford. Economists Erik Brynjolfsson, Bharat Chandar and Ruyu Chen have been tracking payroll data from ADP, one of the biggest payroll processors in the US. In their August 2026 update, workers aged 22 to 25 in the jobs most exposed to AI had a 19% employment gap compared with young workers in less-exposed jobs. A year earlier the gap was 15%.

How it’s happening matters. Companies aren’t firing juniors en masse; they’re hiring fewer of them. The declines are concentrated in roles where AI can do the task outright, like customer service or routine coding, and in work built on “codified” knowledge, the kind you can write down in a manual. Experienced workers, whose value sits in judgment learned on the job, are doing fine or better.

There are louder voices too. In 2025, Anthropic’s chief executive Dario Amodei warned that AI could wipe out half of all entry-level white-collar jobs within five years. (We’ll note the obvious: a company selling AI has reasons to talk up its power. So do its critics have reasons to play it down.)

Why the Class of 2026 Is Worried

The anxiety was hard to miss at this year’s graduation ceremonies.

In May, commencement speakers across the US discovered that the fastest way to lose a room of graduates was to praise AI. At the University of Central Florida on 8 May, real estate executive Gloria Caulfield called AI “the next industrial revolution” and was met with boos. “OK, I struck a chord,” she said. The next day at Middle Tennessee State, music executive Scott Borchetta told graduates that “AI is rewriting production as we sit here.” When they booed, he pushed back: “Deal with it… It’s a tool. Make it work for you.” And on 15 May at the University of Arizona, former Google chief executive Eric Schmidt was jeered repeatedly as he told the class that AI “will touch every profession, every classroom, every hospital.”

You can watch a compilation here in PBS NewsHour Classroom, “Shorts: 2026 graduates boo commencement speeches on AI” (27 May 2026, 2m40s), which is embedded from YouTube on the PBS page: https://www.pbs.org/newshour/classroom/daily-news-lessons/2026/05/shorts-2026-graduates-boo-commencement-speeches-on-ai

The boos don’t tell us how many jobs AI has displaced. But we should take the worry seriously. These students have spent years working towards a qualification, often with considerable help and sacrifice from their families. Being told to embrace a technology that might reduce their chances of getting hired offers little reassurance.

Fortune reported a 2025 Harvard Kennedy School poll in which around seven in ten college students said AI threatened their job prospects. We still need to establish how much of the hiring slowdown AI explains. Graduates shouldn’t have to prove the cause before we take their difficulty finding work seriously.

The broader graduate data points the same way. In the US, the New York Fed’s series on recent college graduates shows their unemployment rate at about 5.7% in June 2026, against about 4.1% for all workers. More than four in ten recent grads are underemployed, working in jobs that don’t need a degree.

Read that again: for most of the past 35 years, a fresh degree meant you were less likely to be unemployed than the average worker. That’s no longer true. For anyone who studied hard on the understanding that a degree would help them find work, that is a difficult change to accept.

The Case That AI Is Getting the Blame

Now look at the same chart again, because it also contains the best argument on the other side.

The line for recent grads crossed above the line for all workers in 2019. ChatGPT launched in November 2022. Whatever opened the gap, it started three years before generative AI was a household word.

Researchers at Yale’s Budget Lab have gone looking for AI’s fingerprints in the wider job market and so far haven’t found them. Comparing AI-exposed jobs with unexposed ones, economist Ryan Nunn wrote in May: “When we apply our preferred strategy, we find no strong evidence of impacts as of yet.”

There are plenty of other suspects. Interest rates rose sharply from 2022, and hiring slowed across the economy. US payroll growth averaged only around 20,000 jobs a month over the year to March, according to the Budget Lab, and unemployment crept up from 3.4% in 2023 to 4.3%. Many tech companies over-hired during the pandemic and have spent the years since trimming. When companies stop hiring, the people who feel it first are always the ones trying to get in the door. They’re also the ones with the least savings to wait it out.

The Stanford data itself isn’t all gloom, either. In jobs where AI helps workers rather than replacing them, employment for young people has been flat or rising. So is the problem AI, or the kind of AI a company chooses to deploy?

Even the Stanford authors add a careful caveat: “We do not view this paper, or any single study, as definitive evidence of AI’s labor-market effects.”

Singapore offers a more reassuring data point, though it cannot speak for all of Asia. Singapore’s Manpower Ministry told parliament in February that employment rates for fresh graduates “have remained broadly stable over the decade,” and that AI’s specific impact on entry-level professional jobs “remains uncertain.”

India shows why that distinction matters. Azim Premji University’s State of Working India 2026 report puts unemployment among graduates under 25 at about 39%, using 2023–24 survey data. That figure describes a broader difficulty finding work; it does not establish that AI caused it. For a young person sending out applications, though, the uncertainty about the cause doesn’t make the wait any easier.

Behind those numbers are young people, and the phrases they’ve coined for how it feels.

In China, the “lying flat” meme is often read by older generations as laziness. It is closer to exhaustion: a generation that studied hard, sat the exams and did what was asked, then found the reward wasn’t there. Graduates also joke about “Kong Yiji’s long gown,” after a classic literary character who couldn’t let go of his scholar’s robe even as it stopped doing him any good. For them, the degree they were proud of has become the gown: hard-earned, hard to take off, and no longer opening doors. In India, many young people spend years preparing for competitive government exams, putting their lives on hold for the chance of one secure job.

None of this is young people being picky or soft. It’s what happens when the promise made to them, work hard, get the degree and the job will follow, stops holding. AI is only one thread in that story, and in much of Asia it may not be the main one yet. But for a 24-year-old in her second year of waiting, the cause matters less than the fact that the door still hasn’t opened. As the ILO’s Sukti Dasgupta put it in August, AI’s direct impact on jobs “is still unclear,” but “we must not be complacent and underestimate the risks.”

We’ve Seen Machines Eat Entry-Level Work Before

History offers a useful rhyme, and a warning.

When the spreadsheet arrived around 1980, it wiped out a huge amount of clerical number-crunching. By one widely cited estimate, the US lost around 400,000 bookkeeping and accounting clerk jobs in the decades that followed. But it gained roughly 600,000 accountants and auditors, because cheap calculation created more demand for people who could interpret the numbers.

ATMs were supposed to end bank tellers. Instead, as economist James Bessen found, teller numbers in the US held up for decades: cheaper branches meant banks opened more of them, and tellers shifted from counting cash to selling products.

Then came the smartphone. Once people could bank from their sofa, they stopped visiting branches. Full-time teller jobs fell from about 332,000 in 2010 to about 164,000 in 2022. The ATM automated a task; the phone made the whole place unnecessary.

That’s the real lesson, and it cuts both ways. Technology that does one piece of a junior’s job tends to reshape the job. Technology that removes the reason the job exists is a different story. Which kind is AI? It may be both, depending on the job.

The other warning is timing: the new jobs weren’t always for the same people, and the transition took years. A 23-year-old doesn’t have years. At 23, waiting can mean another year relying on parents who may already be stretched, or taking whatever work pays the bills while the career you trained for feels further away. An eventual recovery doesn’t give that time back.

The Question Worth Asking

Here is where we land. It’s a view, not a verdict.

Alongside the question of how many junior jobs AI is taking, we need to ask how young people will learn to do those jobs. The junior job was never just a job. It was a training programme that companies paid for without calling it one. You learned judgment by doing the dull work under someone who already had it.

If AI does the dull work, the company saves money this year. But where does it get its senior people in 2036? Every firm has an incentive to let someone else train the juniors, and if everyone waits, nobody does it.

Employers need to decide who will do that training and pay for it. Otherwise, graduates are left waiting for a chance that each company expects another to provide.

There’s a second puzzle, and it lands hardest on the graduates themselves. If the new entry-level job is “check the AI’s work,” how do you check work you’ve never learned to do? The old ladder taught you to spot a wrong number by making a few yourself.

A new graduate needs someone experienced to explain why an answer is wrong, and time to learn without being expected to know everything already. What replaces that support?

Some firms are already experimenting with answers: apprenticeships redesigned around AI tools, juniors paired with agents rather than replaced by them, and programmes like Singapore’s graduate traineeships.

What would change our mind? A few things we’re watching:

  • Whether the young-worker gap keeps widening in AI-exposed jobs while overall hiring recovers. That would point more clearly to AI.
  • Whether the grad-versus-all gap narrows as interest rates fall. That would point to the business cycle.
  • What happens in Asia’s graduate data over the next year or two, allowing for the very different starting points across countries.

Until then, a small thought for anyone hiring: the cheapest junior you’ll ever employ is the one who becomes your best senior. The question is whether anyone is still willing to pay for that.

And to anyone graduating into this: the fact that the first rung is harder to find says more about this moment than it does about you. As the ILO’s director-general, Gilbert Houngbo, put it in August: “A generation that cannot find decent work cannot build its future with confidence.” Fixing that is everyone’s job, not only yours.

Who took a chance on you when you were starting out, and who are you taking a chance on now?


Tara Mulia

For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
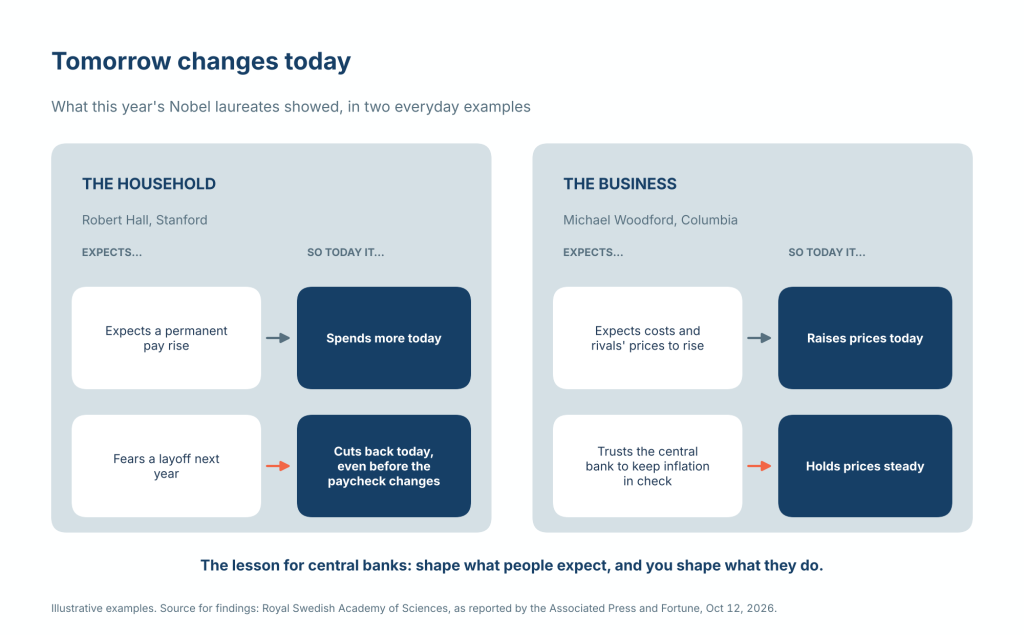


Picture putting $6 billion on a credit card. Then doing it again tomorrow. And the day after that, weekends included, without once turning the statement over to check the balance.

That is not a thought experiment. That is the US federal budget right now. Through the first ten months of this fiscal year the government has borrowed $1.8 trillion, roughly $6 billion every single day, weekends included (July ran hotter still, $431 billion in the month alone).

FY 2026 deficit so far is the second largest in the last 6 years
Source: Peter G. Peterson Foundation, Department of Treasury

And borrowing is the whole point: a deficit is simply the gap between what Washington spends and what it takes in, a shortfall it covers by selling Treasuries to anyone who will buy them. That is the credit card. The tab already tops what Washington borrowed in all of the previous twelve months, with two still on the clock, and the Congressional Budget Office expects the full year to clear $2 trillion.

Read that again: more in ten months than in the entire year before it. When a household runs its finances this way, we call it a spending problem. When the government that prints the world’s reserve currency does it, we call it Tuesday.

But here is the part that never makes the front page. Every dollar borrowed is a dollar that somebody, somewhere, has to be willing to hold. And a growing number of the people who used to hold them are, very quietly, reaching for something else.

A Hawk With Nothing to Hawk With

The bull case for the dollar this year rested on one name: Warsh. The consensus went that a hawkish new Fed chair would defend the currency and bury gold, since the metal pays no yield and higher rates are supposed to make it look silly by comparison.

Except his opening move was to say nothing at all. Asked in June why he would not publish his own rate path, Kevin Warsh was blunt: “Forward guidance isn’t the business we should be in.” We wrote about the corner he is painted into back in July, in “The Hawk With Clipped Wings,” a central banker who wants to look tough while sitting on a debt pile that cannot survive him actually being tough.

Then the ground moved under him. July’s jobs report did not just miss. The economy actually shed 23,000 jobs against forecasts of an 80,000 gain, and June was revised down to a threadbare 20,000. You do not raise rates into a labor market that soft.

The futures pits got the message instantly: the odds of a September hike collapsed from 55% to 40%, and gold tore to its best week since January. Stack the fiscal reality on top: net interest now swallows close to a fifth of every tax dollar, more than the US spends on its military, and Warsh’s bind is complete.

Probability is above 60% now on not hiking rates
Source: CME Group

The debt says he cannot afford to hike; the jobs numbers say he should not; and cutting, with the deficit doing what it is doing, would give the game away entirely. A hawk at the podium, and nothing left to hawk with. What, exactly, is the dollar’s defender defending it with?

That is the disconnect. The market keeps pricing the Fed as if it were free to fight. The Fed’s own books say it is not. And the people standing closest to the printing press seem to agree, which brings us to the other side of the trade.

Meanwhile, Someone Was Buying

While the Treasury spent July writing IOUs, the People’s Bank of China spent it doing the reverse. It added another 19.9 tonnes of gold (that is 0.64 million ounces), its twenty-first consecutive month of buying, the longest unbroken run on its record.

Twenty-one months. Through gold’s record high near $5,589 in January, through a stomach-churning 14% correction in the spring, through every “gold is overbought” note the sell-side could publish, Beijing simply kept stacking. When the West panicked and sold, China did what it has always done with gold: it bought more.

Source: People’s Bank of China, Bloomberg

And this is no China quirk. The World Gold Council’s 2026 survey landed like a quiet bombshell:
• 89% of central banks expect global official gold reserves to keep climbing.
• a record 45% plan to add to their own.
• and 74% see the dollar’s share of reserves lower within five years.

The Council’s own read is that central banks “continue to hold favourable expectations on gold” as the dollar’s share slips. They have hoovered up an average of 1,000 tonnes a year for four years running, double the pace of the prior decade, and official buying hit a record 289 tonnes in the second quarter alone.

The loudest signal, though, is China’s, because it is the most deliberate. Chinese gold imports ran to 173 tonnes in June, the most since early 2024, bringing the first half to roughly 865 tonnes, nearly double the same stretch a year earlier. That is not reserve managers rebalancing at the margin. That is a savings culture moving its money out of paper and into metal, one month at a time.

Source: Bloomberg, Heyokha Research

You Don’t Pour a 2,000-Tonne Vault for Paperwork

Here is the tell that the accumulation is real and not just a headline. You can trade gold two ways. You can trade the promise of it: paper claims that net out on a screen and rarely trouble an actual bar. London and New York move enormous volumes this way, and most of it never leaves the vault because most of it was never there to leave. Or you can trade the metal itself, and for that, you need somewhere to put it.

Guess which one the East is busy building.

Here is the tangible progress so far:
• The Shanghai Gold Exchange opened its first vault outside the mainland, in Hong Kong, with Singapore and Riyadh next on the list.
• Hong Kong’s own physical-gold clearing system began trials in July, complete with a “Delivery Connect” channel to Shanghai: think Stock Connect, but for bullion.
• The city plans to lift vault capacity from around 200 tonnes to more than 2,000 within three years.

Nobody pours ten times the storage for claims that settle on paper. You build steel-lined rooms for 2,000 tonnes because you expect the metal to actually turn up.

There is a second tell, and it is the sharpest of the lot. Through June, one large Chinese bank after another told retail savers that leveraged gold trading on the Shanghai exchange would end in July, with margins on whatever was left pushed to 140%.

Read what is being closed against what is left wide open: access to paper gold, shut off; buying and holding the physical metal, untouched. Whatever the regulatory motivation, the asymmetry is revealing: leverage is being discouraged while ownership of physical metal remains open.

And none of it rides alone. The gold rail is being welded alongside a payments rail. China’s CIPS (cross border interbank payment system) cleared Rmb101 trillion in the first half of 2026, so a trading partner left holding renminbi has somewhere to park it, and something hard to turn it into. As J.P. Morgan told Congress back in 1912, “Gold is money. Everything else is credit.” A century on, someone is quietly laying the plumbing to prove him right.


Bit by bit the challenge against the dollar is revealing itself
Source: CIPS, Heyokha Research

The Metal Ends Up With the Patient

So set the two halves of the year side by side. One government borrowing some $6 billion a day, its central bank unwilling to say what it will do next. One central bank on the far side of the planet buying the thing that cannot be printed for the twenty-first month straight, while its country pours the vaults to hold it.

As we pointed out in our “Q1 2026 Reflection report”, Iran taking renminbi for oil, the PBOC buying the dip, a nation of savers stepping off paper: these are the same story told at different speeds. Confidence draining out of fiat and settling into metal, one decision at a time. Call it de-dollarization; we have started calling it de-fiatization. It is slow, it is quiet, and it does not reverse because gold had a bad quarter.

We do not pretend to be seers. We cannot tell you what gold prints next week or what Warsh mutters next month. But the direction is critical. When the currency is being quietly debased and the people closest to the printing press are the ones stockpiling the thing that cannot be printed, what you would want to own stops being a riddle. This week said it out loud: soft jobs, a cornered Fed, gold roaring to its best week since January.

Could we be wrong? Of course. If US growth surprises, if the deficit narrows, if the world falls back in love with Treasuries, the urgency drains out of all this and gold just sits there being shiny and dull. We would only note that betting on Washington’s fiscal restraint has been a losing trade for about twenty-five years. “Paper money,” as the line attributed to Voltaire runs, “eventually returns to its intrinsic value: zero.” The open question is simply how long “eventually” takes.

Here is what we keep circling back to. When the world’s largest borrower and the world’s most patient buyer sit on opposite sides of the same table, it is worth asking which one intends to be there when the game ends. The IOUs pile higher on one side. The metal stacks quietly on the other. And the metal, as the last fifty years keep teaching anyone willing to sit still long enough, ends up with whoever is most patient.

Washington is writing the receipts. Somewhere in the East, someone is quietly pouring the vault to hold the collateral.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
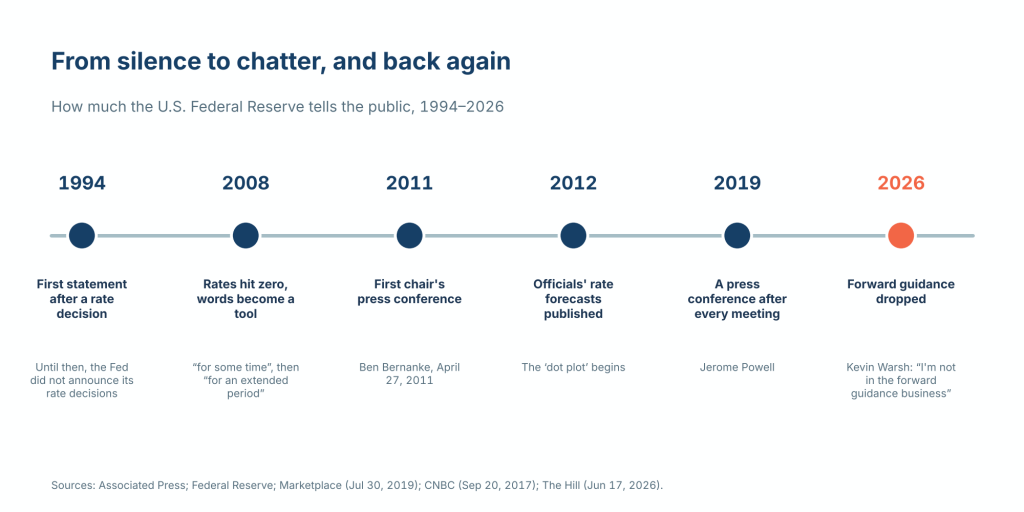


Picture putting $6 billion on a credit card. Then doing it again tomorrow. And the day after that, weekends included, without once turning the statement over to check the balance.

That is not a thought experiment. That is the US federal budget right now. Through the first ten months of this fiscal year the government has borrowed $1.8 trillion, roughly $6 billion every single day, weekends included (July ran hotter still, $431 billion in the month alone).

FY 2026 deficit so far is the second largest in the last 6 years
Source: Peter G. Peterson Foundation, Department of Treasury

And borrowing is the whole point: a deficit is simply the gap between what Washington spends and what it takes in, a shortfall it covers by selling Treasuries to anyone who will buy them. That is the credit card. The tab already tops what Washington borrowed in all of the previous twelve months, with two still on the clock, and the Congressional Budget Office expects the full year to clear $2 trillion.

Read that again: more in ten months than in the entire year before it. When a household runs its finances this way, we call it a spending problem. When the government that prints the world’s reserve currency does it, we call it Tuesday.

But here is the part that never makes the front page. Every dollar borrowed is a dollar that somebody, somewhere, has to be willing to hold. And a growing number of the people who used to hold them are, very quietly, reaching for something else.

A Hawk With Nothing to Hawk With

The bull case for the dollar this year rested on one name: Warsh. The consensus went that a hawkish new Fed chair would defend the currency and bury gold, since the metal pays no yield and higher rates are supposed to make it look silly by comparison.

Except his opening move was to say nothing at all. Asked in June why he would not publish his own rate path, Kevin Warsh was blunt: “Forward guidance isn’t the business we should be in.” We wrote about the corner he is painted into back in July, in “The Hawk With Clipped Wings,” a central banker who wants to look tough while sitting on a debt pile that cannot survive him actually being tough.

Then the ground moved under him. July’s jobs report did not just miss. The economy actually shed 23,000 jobs against forecasts of an 80,000 gain, and June was revised down to a threadbare 20,000. You do not raise rates into a labor market that soft.

The futures pits got the message instantly: the odds of a September hike collapsed from 55% to 40%, and gold tore to its best week since January. Stack the fiscal reality on top: net interest now swallows close to a fifth of every tax dollar, more than the US spends on its military, and Warsh’s bind is complete.

Probability is above 60% now on not hiking rates
Source: CME Group

The debt says he cannot afford to hike; the jobs numbers say he should not; and cutting, with the deficit doing what it is doing, would give the game away entirely. A hawk at the podium, and nothing left to hawk with. What, exactly, is the dollar’s defender defending it with?

That is the disconnect. The market keeps pricing the Fed as if it were free to fight. The Fed’s own books say it is not. And the people standing closest to the printing press seem to agree, which brings us to the other side of the trade.

Meanwhile, Someone Was Buying

While the Treasury spent July writing IOUs, the People’s Bank of China spent it doing the reverse. It added another 19.9 tonnes of gold (that is 0.64 million ounces), its twenty-first consecutive month of buying, the longest unbroken run on its record.

Twenty-one months. Through gold’s record high near $5,589 in January, through a stomach-churning 14% correction in the spring, through every “gold is overbought” note the sell-side could publish, Beijing simply kept stacking. When the West panicked and sold, China did what it has always done with gold: it bought more.

Source: People’s Bank of China, Bloomberg

And this is no China quirk. The World Gold Council’s 2026 survey landed like a quiet bombshell:
• 89% of central banks expect global official gold reserves to keep climbing.
• a record 45% plan to add to their own.
• and 74% see the dollar’s share of reserves lower within five years.

The Council’s own read is that central banks “continue to hold favourable expectations on gold” as the dollar’s share slips. They have hoovered up an average of 1,000 tonnes a year for four years running, double the pace of the prior decade, and official buying hit a record 289 tonnes in the second quarter alone.

The loudest signal, though, is China’s, because it is the most deliberate. Chinese gold imports ran to 173 tonnes in June, the most since early 2024, bringing the first half to roughly 865 tonnes, nearly double the same stretch a year earlier. That is not reserve managers rebalancing at the margin. That is a savings culture moving its money out of paper and into metal, one month at a time.

Source: Bloomberg, Heyokha Research

You Don’t Pour a 2,000-Tonne Vault for Paperwork

Here is the tell that the accumulation is real and not just a headline. You can trade gold two ways. You can trade the promise of it: paper claims that net out on a screen and rarely trouble an actual bar. London and New York move enormous volumes this way, and most of it never leaves the vault because most of it was never there to leave. Or you can trade the metal itself, and for that, you need somewhere to put it.

Guess which one the East is busy building.

Here is the tangible progress so far:
• The Shanghai Gold Exchange opened its first vault outside the mainland, in Hong Kong, with Singapore and Riyadh next on the list.
• Hong Kong’s own physical-gold clearing system began trials in July, complete with a “Delivery Connect” channel to Shanghai: think Stock Connect, but for bullion.
• The city plans to lift vault capacity from around 200 tonnes to more than 2,000 within three years.

Nobody pours ten times the storage for claims that settle on paper. You build steel-lined rooms for 2,000 tonnes because you expect the metal to actually turn up.

There is a second tell, and it is the sharpest of the lot. Through June, one large Chinese bank after another told retail savers that leveraged gold trading on the Shanghai exchange would end in July, with margins on whatever was left pushed to 140%.

Read what is being closed against what is left wide open: access to paper gold, shut off; buying and holding the physical metal, untouched. Whatever the regulatory motivation, the asymmetry is revealing: leverage is being discouraged while ownership of physical metal remains open.

And none of it rides alone. The gold rail is being welded alongside a payments rail. China’s CIPS (cross border interbank payment system) cleared Rmb101 trillion in the first half of 2026, so a trading partner left holding renminbi has somewhere to park it, and something hard to turn it into. As J.P. Morgan told Congress back in 1912, “Gold is money. Everything else is credit.” A century on, someone is quietly laying the plumbing to prove him right.


Bit by bit the challenge against the dollar is revealing itself
Source: CIPS, Heyokha Research

The Metal Ends Up With the Patient

So set the two halves of the year side by side. One government borrowing some $6 billion a day, its central bank unwilling to say what it will do next. One central bank on the far side of the planet buying the thing that cannot be printed for the twenty-first month straight, while its country pours the vaults to hold it.

As we pointed out in our “Q1 2026 Reflection report”, Iran taking renminbi for oil, the PBOC buying the dip, a nation of savers stepping off paper: these are the same story told at different speeds. Confidence draining out of fiat and settling into metal, one decision at a time. Call it de-dollarization; we have started calling it de-fiatization. It is slow, it is quiet, and it does not reverse because gold had a bad quarter.

We do not pretend to be seers. We cannot tell you what gold prints next week or what Warsh mutters next month. But the direction is critical. When the currency is being quietly debased and the people closest to the printing press are the ones stockpiling the thing that cannot be printed, what you would want to own stops being a riddle. This week said it out loud: soft jobs, a cornered Fed, gold roaring to its best week since January.

Could we be wrong? Of course. If US growth surprises, if the deficit narrows, if the world falls back in love with Treasuries, the urgency drains out of all this and gold just sits there being shiny and dull. We would only note that betting on Washington’s fiscal restraint has been a losing trade for about twenty-five years. “Paper money,” as the line attributed to Voltaire runs, “eventually returns to its intrinsic value: zero.” The open question is simply how long “eventually” takes.

Here is what we keep circling back to. When the world’s largest borrower and the world’s most patient buyer sit on opposite sides of the same table, it is worth asking which one intends to be there when the game ends. The IOUs pile higher on one side. The metal stacks quietly on the other. And the metal, as the last fifty years keep teaching anyone willing to sit still long enough, ends up with whoever is most patient.

Washington is writing the receipts. Somewhere in the East, someone is quietly pouring the vault to hold the collateral.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
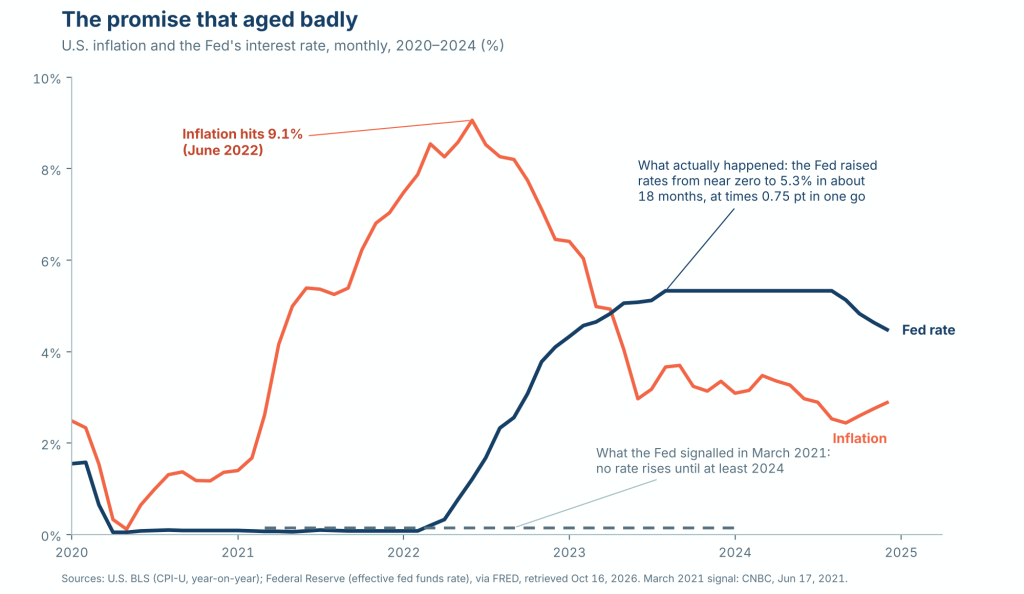


For the first time in almost 30 years, the United States and Japan intervened together to rescue the yen, hauling it off a 40-year low of 164 to the dollar back to around 156 in a matter of days.

It was loud, coordinated and impossible to miss: the financial equivalent of Spider-Man swinging into midtown in broad daylight. Everyone saw it. The yen jumped on cue, and the headlines wrote themselves.

But a masked hero only shows up when something has gone badly wrong, and the crowd watching the acrobatics almost never asks the more interesting question: who is under the mask, and what is he really trying to hold together?

The rescue was the easy part to see. The thing that made it necessary went almost unremarked, and it has a name. It’s called financial repression, and it has been quietly at work for years while everyone watched the swinging.

The $59 Billion Web-Shooter

On Thursday, the yen was on the floor: 164 to the dollar, a 40-year low. By Friday it was back to around 156. Nothing about Japan’s situation changed in between. What changed was who showed up to help.

Tokyo intervening is nothing new; it has propped up the yen on its own for years, spending as much as roughly $58.97 billion (equivalent to ¥8.45 trillion), in this single day alone, its largest one-day intervention on record. What was new was that it didn’t do it alone.

Source: Bloomberg, Heyokha Research

For the first time since the 1998 Asian Financial Crisis, the New York Fed sold euros to buy yen on behalf of the U.S. Treasury, routed through Goldman Sachs and Morgan Stanley. The U.S. has quietly lent a hand before, but not for nearly 30 years, and rarely this openly. Washington doesn’t usually put its name on the tape like this.

Now look at the number again: roughly $59 billion in one day, to nudge a currency back toward a level that much of the market doubts it can hold. Goldman spent the same week lifting its twelve-month forecast to 165, roughly where the yen started. That is one bank’s forecast, not a certainty: a bolder Bank of Japan, or a narrower gap between U.S. and Japanese interest rates, could give the yen firmer footing than the bears expect. But if neither arrives, it is fair to ask what $59 billion actually bought. Our read: less a fix than the appearance of one.

The intervention was ostensibly about the yen. But the plumbing suggests

Washington may have been protecting something larger too: the Treasury market.

What the Mask Is Hiding

Financial repression has a simple definition: it’s how a government moves a fortune from its savers to itself without passing a single law that says so.

The mechanics go like this:

  • A government with more debt than it can ever repay holds interest rates below the rate of inflation
  • So a captive base of savers funds the state at a slow, silent loss
  • The saver still sees a positive number on the statement. The bond still pays its coupon. And every year, quietly, the money buys a little less.

No tax to legislate, no benefit to cut, no default to announce. Just a fifth of a lifetime’s caution gone over a decade, with no single day on which anything visibly breaks.

Japan wrote the modern playbook, using a tool called yield-curve control.

Here is how it worked:

  • Instead of setting an overnight rate and hoping the bond market followed, the Bank of Japan fixed the price of the government’s own borrowing directly.
  • It set a target for the 10-year yield, near zero at first, and promised to buy unlimited quantities of government bonds, at whatever price it took, to stop that yield from rising above the line.
  • Every time a trader tried to sell bonds and push yields up, the BOJ printed fresh yen and bought whatever was for sale. Do that long enough and you don’t influence the market; you become it.
  • By the end, the central bank owned more than half of its own government’s bond market.

When you are the biggest buyer of your own IOUs, the yield stops being a signal and becomes a setting. The number on the screen no longer tells you anything true. It tells you what someone decided you should see.

Japan pinned its bond yields for more than two decades, and the yen paid the price

Source: Bloomberg, Heyokha Research

This isn’t only Japan. The United States is also facing immense fiscal strain, with net interest plus entitlements eating up 96.2% of all federal government receipts in the twelve months to June 2026.

While this staggering metric demonstrates severe fiscal pressure, it requires a specific causal chain to become financial repression: fiscal pressure creates political constraints against high real rates, which forces monetary accommodation and captive demand, ultimately leading to negative real returns.

The fiscal gap is financed through some combination of borrowing, taxation, spending choices, and monetary accommodation. But under regimes of financial repression, the residual burden silently falls on the saver through a currency that buys a little less each year.

Source: Jefferies, Bureau Fiscal Service, Bloomberg

Who Is Really Being Rescued

This brings us to the core dynamic: the world’s two largest developed sovereign bond markets may increasingly constrain each other’s monetary choices. Suddenly, Tokyo’s monetary problem becomes Washington’s duration problem.

Buried in the details was a second request, and notice who it was aimed at: the Fed. Bessent, the Treasury Secretary, publicly urged the supposedly independent central bank to expand The Foreign and International Monetary Authorities (FIMA) Repo Facility, and to keep expanding it. It’s plumbing, not headlines, which is exactly why it matters.

FIMA lets a foreign government borrow dollars against its U.S. Treasuries without selling them. It was created as temporary measure during the COVID-19 pandemic.

FIMA was designed for periods of turmoil, not an everyday funding tool.
Which bears the question: why the suggestion to use it now? Is this the U.S. admitting they are in turmoil?

Its proposed expansion tells us something subtler: policymakers increasingly want mechanisms that provide dollar liquidity without forcing foreign reserve managers to sell Treasuries.

Why?:

  • Japan is the largest foreign holder of U.S. government debt on Earth, a pile that peaked near $1.33 trillion in 2021 and has already begun to shrink, down to roughly $1.14 trillion by May.
  • If Tokyo raised dollars the honest way, by selling a slice of that pile, it would push U.S. yields up at the worst possible moment, with the American 10-year already near 4.7% and the 30-year above 5%. America cannot let their debt servicing worse than it already is.
  • FIMA is the side door that lets Japan get its dollars while the Treasuries stay put.

Goldman Sachs said it plainly: “The fact that US authorities approved the use of this facility suggests the US side sees potential risk that FX intervention could push up US Treasury yields.” Or, as the FT’s Unhedged put it, this was “less of an intervention to support the yen and more of an intervention to support Treasuries.”

So who is really being rescued here, the yen or the Treasury market?

The crowd saw a currency saved. What actually happened was two of the most indebted governments on the planet quietly propping each other up so that neither has to let interest rates tell the truth.

We wrote in July 2026, in “The Hawk with Clipped Wings” that even a hawk like Kevin Warsh can’t tighten when the debt won’t allow it. In June 2026, in “How a Throwaway Line on 1980s TV Became the World’s 2% Inflation Target” we showed how even the sacred 2% inflation target began as a throwaway line on 1980s television that now conveniently lets governments inflate their debt away. This is the same story in a new costume.

How many of the numbers we glance at every day, a bond yield, a mortgage rate, a currency quote, are just the mask? And how often do we stop to ask who’s underneath?

Why the Mask Slips

The BOJ voted eight to one to hold rates at just 1%, its highest since 1995 but still miles below the Fed’s 3.75%.

The reason Tokyo won’t simply hike its way out is that it can’t afford to.
Case in point: Japan’s gross government interest bill runs a startlingly low 1.3% of GDP, against America’s 4.7%. That comfort is the whole trick: it exists only because yields have been pinned down for years. Let rates find their honest level and that 1.3% balloons, which is precisely why they dare not.

And the pinning is already slipping: the 10-year JGB now yields 2.8% and the 30-year 4%, nosebleed levels for a market that sat near zero for a generation.

The nosebleed
Source: Bloomberg

The strange part is that everyone can see it. The Wall Street Journal’s Heard on the Street said flatly that only real BOJ rate hikes can durably stop the slide. Leveraged funds are sitting on their largest net-short yen position since 2007, betting the rescue wears off.

Japan spent decades using a weak yen as its release valve; now the valve has blown so far open, with at least $255 billion of intervention since 2022, that Tokyo is trying to defend the currency and the bond market at the same time.

Can it hold both? History suggests that is hard to do for long: when a country tries to defend its currency and hold down its bond yields at the same time, one of the two has often had to give. But that is a pattern, not a law. Betting against Japan’s bond market earned the nickname “the widow-maker trade” because so many who tried it lost money, and a steady, well-signalled run of BOJ hikes, or a narrower gap with U.S. rates, could still let Tokyo manage both for longer than the sceptics expect. What would tell us the strain is winning: repeated rounds of intervention that buy less time with each go, and long-dated JGB yields that keep climbing regardless.

The Thing You Can’t Print

A mask changes what people see. It doesn’t change who is underneath, or what is real.

You can move the price of the yen for a day, or pin the yield on a bond for a decade, but you cannot change what money is actually worth. When currencies are quietly debased and yields are quietly capped, capital stops arguing and starts reaching for what can’t be printed.

When global sovereigns are forced into a regime of negative real rates, the mechanical engine of financial repression, they systematically eliminate the traditional yield advantage of holding fiat. In this environment, gold stops being merely a legacy asset and becomes the ultimate non-printable anchor for capital seeking refuge from silent confiscation.

Look at what gold did in the very week of the rescue. As Washington helped push the dollar down to lift the yen, gold climbed about 4% to around $4,300 an ounce, its highest in seven weeks. Central banks have been the steady buyers underneath, more than 1,000 tonnes a year in 2022, 2023 and 2024, and a record 288.9 tonnes in the second quarter of 2026 alone.

This is what de-dollarization actually looks like. Not a headline, not a summit, just capital quietly reaching for the real thing, one central-bank gold purchase at a time. Fiat is a variable. Gold is the constant.

Watch the acrobatics if you like. Just remember there is a man under the mask, and a reason he can’t stop swinging. Our suspicion is that the $59 billion rescue proves temporary, and that without a real narrowing of the rate gap, the yen could drift back toward where the fundamentals pull it. We could be wrong: a bolder BOJ or a softer dollar would change that picture quickly. Either way, the question that matters most, for a saver watching a perfectly positive number tick up on a statement that buys a little less each year, is the one nobody in the crowd thinks to ask: what is being done to you while you’re watching the show?


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
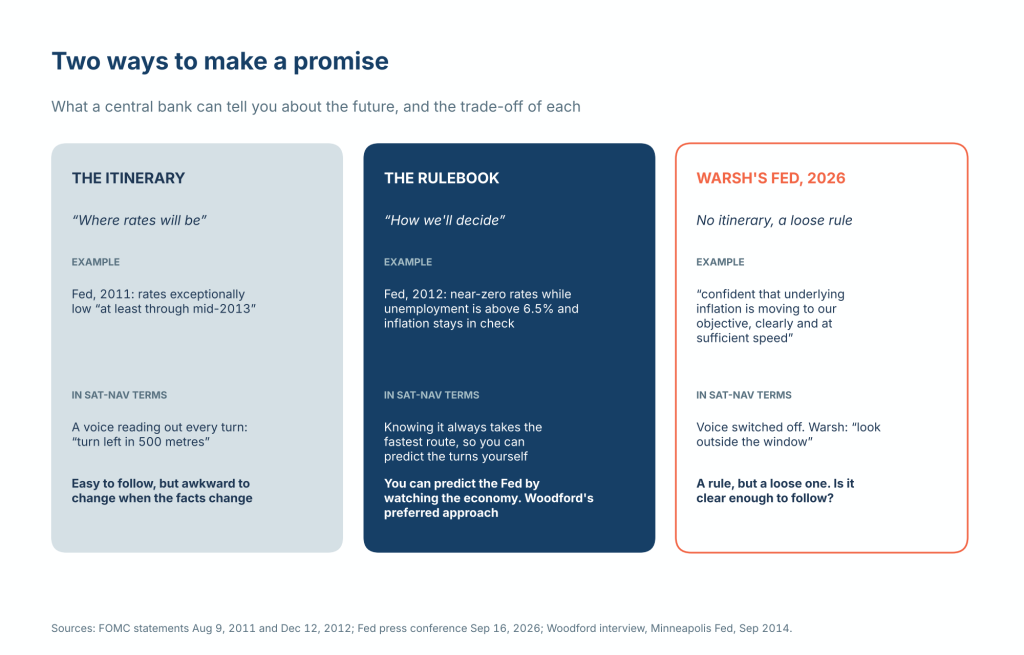


For the first time in almost 30 years, the United States and Japan intervened together to rescue the yen, hauling it off a 40-year low of 164 to the dollar back to around 156 in a matter of days.

It was loud, coordinated and impossible to miss: the financial equivalent of Spider-Man swinging into midtown in broad daylight. Everyone saw it. The yen jumped on cue, and the headlines wrote themselves.

But a masked hero only shows up when something has gone badly wrong, and the crowd watching the acrobatics almost never asks the more interesting question: who is under the mask, and what is he really trying to hold together?

The rescue was the easy part to see. The thing that made it necessary went almost unremarked, and it has a name. It’s called financial repression, and it has been quietly at work for years while everyone watched the swinging.

The $59 Billion Web-Shooter

On Thursday, the yen was on the floor: 164 to the dollar, a 40-year low. By Friday it was back to around 156. Nothing about Japan’s situation changed in between. What changed was who showed up to help.

Tokyo intervening is nothing new; it has propped up the yen on its own for years, spending as much as roughly $58.97 billion (equivalent to ¥8.45 trillion), in this single day alone, its largest one-day intervention on record. What was new was that it didn’t do it alone.

Source: Bloomberg, Heyokha Research

For the first time since the 1998 Asian Financial Crisis, the New York Fed sold euros to buy yen on behalf of the U.S. Treasury, routed through Goldman Sachs and Morgan Stanley. The U.S. has quietly lent a hand before, but not for nearly 30 years, and rarely this openly. Washington doesn’t usually put its name on the tape like this.

Now look at the number again: roughly $59 billion in one day, to nudge a currency back toward a level that much of the market doubts it can hold. Goldman spent the same week lifting its twelve-month forecast to 165, roughly where the yen started. That is one bank’s forecast, not a certainty: a bolder Bank of Japan, or a narrower gap between U.S. and Japanese interest rates, could give the yen firmer footing than the bears expect. But if neither arrives, it is fair to ask what $59 billion actually bought. Our read: less a fix than the appearance of one.

The intervention was ostensibly about the yen. But the plumbing suggests

Washington may have been protecting something larger too: the Treasury market.

What the Mask Is Hiding

Financial repression has a simple definition: it’s how a government moves a fortune from its savers to itself without passing a single law that says so.

The mechanics go like this:

  • A government with more debt than it can ever repay holds interest rates below the rate of inflation
  • So a captive base of savers funds the state at a slow, silent loss
  • The saver still sees a positive number on the statement. The bond still pays its coupon. And every year, quietly, the money buys a little less.

No tax to legislate, no benefit to cut, no default to announce. Just a fifth of a lifetime’s caution gone over a decade, with no single day on which anything visibly breaks.

Japan wrote the modern playbook, using a tool called yield-curve control.

Here is how it worked:

  • Instead of setting an overnight rate and hoping the bond market followed, the Bank of Japan fixed the price of the government’s own borrowing directly.
  • It set a target for the 10-year yield, near zero at first, and promised to buy unlimited quantities of government bonds, at whatever price it took, to stop that yield from rising above the line.
  • Every time a trader tried to sell bonds and push yields up, the BOJ printed fresh yen and bought whatever was for sale. Do that long enough and you don’t influence the market; you become it.
  • By the end, the central bank owned more than half of its own government’s bond market.

When you are the biggest buyer of your own IOUs, the yield stops being a signal and becomes a setting. The number on the screen no longer tells you anything true. It tells you what someone decided you should see.

Japan pinned its bond yields for more than two decades, and the yen paid the price

Source: Bloomberg, Heyokha Research

This isn’t only Japan. The United States is also facing immense fiscal strain, with net interest plus entitlements eating up 96.2% of all federal government receipts in the twelve months to June 2026.

While this staggering metric demonstrates severe fiscal pressure, it requires a specific causal chain to become financial repression: fiscal pressure creates political constraints against high real rates, which forces monetary accommodation and captive demand, ultimately leading to negative real returns.

The fiscal gap is financed through some combination of borrowing, taxation, spending choices, and monetary accommodation. But under regimes of financial repression, the residual burden silently falls on the saver through a currency that buys a little less each year.

Source: Jefferies, Bureau Fiscal Service, Bloomberg

Who Is Really Being Rescued

This brings us to the core dynamic: the world’s two largest developed sovereign bond markets may increasingly constrain each other’s monetary choices. Suddenly, Tokyo’s monetary problem becomes Washington’s duration problem.

Buried in the details was a second request, and notice who it was aimed at: the Fed. Bessent, the Treasury Secretary, publicly urged the supposedly independent central bank to expand The Foreign and International Monetary Authorities (FIMA) Repo Facility, and to keep expanding it. It’s plumbing, not headlines, which is exactly why it matters.

FIMA lets a foreign government borrow dollars against its U.S. Treasuries without selling them. It was created as temporary measure during the COVID-19 pandemic.

FIMA was designed for periods of turmoil, not an everyday funding tool.
Which bears the question: why the suggestion to use it now? Is this the U.S. admitting they are in turmoil?

Its proposed expansion tells us something subtler: policymakers increasingly want mechanisms that provide dollar liquidity without forcing foreign reserve managers to sell Treasuries.

Why?:

  • Japan is the largest foreign holder of U.S. government debt on Earth, a pile that peaked near $1.33 trillion in 2021 and has already begun to shrink, down to roughly $1.14 trillion by May.
  • If Tokyo raised dollars the honest way, by selling a slice of that pile, it would push U.S. yields up at the worst possible moment, with the American 10-year already near 4.7% and the 30-year above 5%. America cannot let their debt servicing worse than it already is.
  • FIMA is the side door that lets Japan get its dollars while the Treasuries stay put.

Goldman Sachs said it plainly: “The fact that US authorities approved the use of this facility suggests the US side sees potential risk that FX intervention could push up US Treasury yields.” Or, as the FT’s Unhedged put it, this was “less of an intervention to support the yen and more of an intervention to support Treasuries.”

So who is really being rescued here, the yen or the Treasury market?

The crowd saw a currency saved. What actually happened was two of the most indebted governments on the planet quietly propping each other up so that neither has to let interest rates tell the truth.

We wrote in July 2026, in “The Hawk with Clipped Wings” that even a hawk like Kevin Warsh can’t tighten when the debt won’t allow it. In June 2026, in “How a Throwaway Line on 1980s TV Became the World’s 2% Inflation Target” we showed how even the sacred 2% inflation target began as a throwaway line on 1980s television that now conveniently lets governments inflate their debt away. This is the same story in a new costume.

How many of the numbers we glance at every day, a bond yield, a mortgage rate, a currency quote, are just the mask? And how often do we stop to ask who’s underneath?

Why the Mask Slips

The BOJ voted eight to one to hold rates at just 1%, its highest since 1995 but still miles below the Fed’s 3.75%.

The reason Tokyo won’t simply hike its way out is that it can’t afford to.
Case in point: Japan’s gross government interest bill runs a startlingly low 1.3% of GDP, against America’s 4.7%. That comfort is the whole trick: it exists only because yields have been pinned down for years. Let rates find their honest level and that 1.3% balloons, which is precisely why they dare not.

And the pinning is already slipping: the 10-year JGB now yields 2.8% and the 30-year 4%, nosebleed levels for a market that sat near zero for a generation.

The nosebleed
Source: Bloomberg

The strange part is that everyone can see it. The Wall Street Journal’s Heard on the Street said flatly that only real BOJ rate hikes can durably stop the slide. Leveraged funds are sitting on their largest net-short yen position since 2007, betting the rescue wears off.

Japan spent decades using a weak yen as its release valve; now the valve has blown so far open, with at least $255 billion of intervention since 2022, that Tokyo is trying to defend the currency and the bond market at the same time.

Can it hold both? History suggests that is hard to do for long: when a country tries to defend its currency and hold down its bond yields at the same time, one of the two has often had to give. But that is a pattern, not a law. Betting against Japan’s bond market earned the nickname “the widow-maker trade” because so many who tried it lost money, and a steady, well-signalled run of BOJ hikes, or a narrower gap with U.S. rates, could still let Tokyo manage both for longer than the sceptics expect. What would tell us the strain is winning: repeated rounds of intervention that buy less time with each go, and long-dated JGB yields that keep climbing regardless.

The Thing You Can’t Print

A mask changes what people see. It doesn’t change who is underneath, or what is real.

You can move the price of the yen for a day, or pin the yield on a bond for a decade, but you cannot change what money is actually worth. When currencies are quietly debased and yields are quietly capped, capital stops arguing and starts reaching for what can’t be printed.

When global sovereigns are forced into a regime of negative real rates, the mechanical engine of financial repression, they systematically eliminate the traditional yield advantage of holding fiat. In this environment, gold stops being merely a legacy asset and becomes the ultimate non-printable anchor for capital seeking refuge from silent confiscation.

Look at what gold did in the very week of the rescue. As Washington helped push the dollar down to lift the yen, gold climbed about 4% to around $4,300 an ounce, its highest in seven weeks. Central banks have been the steady buyers underneath, more than 1,000 tonnes a year in 2022, 2023 and 2024, and a record 288.9 tonnes in the second quarter of 2026 alone.

This is what de-dollarization actually looks like. Not a headline, not a summit, just capital quietly reaching for the real thing, one central-bank gold purchase at a time. Fiat is a variable. Gold is the constant.

Watch the acrobatics if you like. Just remember there is a man under the mask, and a reason he can’t stop swinging. Our suspicion is that the $59 billion rescue proves temporary, and that without a real narrowing of the rate gap, the yen could drift back toward where the fundamentals pull it. We could be wrong: a bolder BOJ or a softer dollar would change that picture quickly. Either way, the question that matters most, for a saver watching a perfectly positive number tick up on a statement that buys a little less each year, is the one nobody in the crowd thinks to ask: what is being done to you while you’re watching the show?


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


The Trojans, the story goes, had no idea. The horse looked like a gift, so they pulled it inside and celebrated, and by the time the soldiers climbed out it was far too late.

The modern re-run of that story, film director Christopher Nolan suggests, is stranger still.

Asked about artificial intelligence while promoting his new film The Odyssey, he offered an image we have not been able to shake: “AI is a Trojan horse that everybody knows the Greeks are inside. It’s a transparent horse. It’s made of glass. Everybody can see what’s going on inside of there.”

Source: hugodecryptegrandsformats Youtube

He added something sharper still: “I’ve never seen a technology advancing so rapidly that’s been so completely rejected by the public.”

Now, Nolan is a filmmaker, not an economist, and some of what he is reacting to is his own industry’s revolt against AI: the actors, writers and artists who watched it come for their work first and the “AI slop” it produces. But the people it comes for next look a lot like the rest of us.

Sit with what Nolan said for a second. This time the horse is see-through. The crowd can watch the soldiers loading their spears. And the crowd is cheering it through the gates regardless, because the people handing over the gift keep promising that what is inside is not an army but a golden age.

Maybe it is. We are not here to argue that AI is fake or feeble; betting against it has been a fast way to look foolish.

We are here to talk about the part nobody selling the horse wants to linger on: the gap between the day the soldiers climb out and the day the golden age is supposed to arrive.

The Valley Between Two Worlds

Peter Diamandis, who wrote a book literally called Abundance, is one of the great evangelists for the AI future. Even he does not pretend the road is smooth. He describes a stretch he calls “the chasm,” a period in which the old jobs vanish before the new prosperity shows up. He puts it at two to eight years.

Mo Gawdat, the former chief business officer of Google’s moonshot lab, thinks it is longer and darker, calling it a twelve to fifteen year “dystopia” before things get better.


How Mo Gawdat, former chief business officer of Google’s moonshot lab sees what will transpire moving forward

Here is the trouble with a chasm. How green does the far side have to be to justify the crossing? It does not matter how green it is if you cannot get across. Next decade’s abundance does not pay this month’s rent.

And the crossing, on the optimists’ own timelines, is measured not in months but in years. As one MIT study in 2025 found, 95% of companies deploying generative AI had yet to see any measurable return at all. The payoff is a promise. The disruption is already here.

So before we admire the far side, let us be honest about the valley.

Who Falls In First

The first wave is the one everyone pictures: routine, physical, blue-collar work. In the United States alone:

  • Around 2.2 million people drive heavy trucks for a living, before you count couriers and ride-hailing drivers.
  • Roughly 5 million work in food service.
  • Close to 2.8 million staff call centres.

The machines are already here for them. Tesla and BYD have turned the car itself into a robot, and Elon Musk, whose trillion-dollar pay deal back in November 2025 is pegged to shipping a million humanoid Optimus robots, talked cheerfully about a world with more robots than people.

National Bureau of Economic Research on “ How Adaptable are American Workers to AI-Induced Job Displacement”?


The comforting reply has always been that the displaced will retrain into something better. But retrain into what, exactly? Not every laid-off truck driver becomes an AI engineer, and the internet does not need more influencers.

Then comes the part that is genuinely new, and the reason this is a middle-class story and not just a blue-collar one. The wave does not stop at the bottom of the ladder. It climbs.

As Gawdat lays it out, AI comes for the rungs we always assumed were safe:

  • The paralegal.
  • The financial analyst.
  • The radiologist reading a scan.
  • The graphic designer.
  • Even the layer of middle management whose whole job was coordinating other people.

This is not a fringe worry.

Dario Amodei, the chief executive of Anthropic, warns that AI could wipe out half of all entry-level white-collar jobs and push unemployment to 10 to 20% within five years, with finance, law, consulting and tech first in line.

When the person building the thing is the one raising the alarm, it is worth taking the alarm more seriously than the sales pitch.

And here is the part that should stop you cold: it does not take mass unemployment to do real damage. Gawdat puts the threshold bluntly. “At 10 to 20% job displacement, you’re in a very different economy, an economy that is clearly spiraling downwards.”

Remember that consumer spending is close to 70% of the US economy. The workers being automated away are also the customers who buy what the economy makes. What happens to a business when the people it just replaced were also the people who bought its product?

You do not simply create an unemployment problem. You knock the legs out from under demand itself.

The Generation That Did Everything Right

You can already watch the chasm opening, if you know where to look. We sat through the clips from this year’s American graduation season, and they are something to behold. Students booed their own commencement speakers for daring to praise AI.

Eric Schmidt, the former chief executive of Google, was jeered at the University of Arizona.

Picture it: a generation that spent four years and a small fortune on a degree, booing the future being handed to them. It is easy to call that entitled. We think it is something closer to clear-eyed.

The cruelty is in the order of events. The bottom rung of the white-collar ladder, the entry-level job a graduate used to climb, is the first thing sawn off, stranding the people who did everything they were told to do.


How will the youth get jobs? Even those with degrees are losing out

Source: U.S. Census Bureau and U.S. Bureau of Labor Statistics, Current Population Survey (IPUMS)

The Nobel laureate Geoffrey Hinton, often called the godfather of AI, framed the real fear better than any protest sign. The graduates, he suggests, are not frightened of the technology. They are frightened of the bargain: a system in which the gains flow to shareholders and the redundancy flows to them, with no net to catch the fall and no healthcare that is not tied to a job.

As Hinton puts it, AI “will make a few people much richer and most people poorer. That’s not AI’s fault, that is the capitalist system.”

That single sentence reframes the whole debate. The problem in the belly of the glass horse is not the machine. It is how we have decided to share what the machine produces. Gawdat says it plainly: “This is a distribution problem, not a technology one.”

China Cheers, America Boos

Here is where the view widens, because the same glass horse looks completely different depending on which gate it is rolling through.

A 2024 Ipsos survey of more than 23,000 people across 32 countries asked a simple question: do the benefits of AI outweigh the harms? The answers split the world almost neatly in two:

  • China: 83% said yes.
  • Indonesia: 80%.
  • Thailand: 77%.
  • United States: just 39%.
  • The Netherlands, most fearful of all: 36%.

The Anglosphere are the most nervous for AI whereas Asia are most excited

Source: Ipsos

It is worth holding the two pictures side by side. A rising power, China, greets the new machine with 83% optimism, and at the very same time steadily swaps its dollars for gold.

A late-cycle power, the United States, fears the machine, cannot agree on how to share its spoils, and answers every shock by printing more of the very currency the rest of the world is quietly edging away from.

The technology is identical. Only the safety net differs.

Run the same automation through a society with universal healthcare and a real income floor, and losing your job to a robot is a setback rather than a catastrophe. America has no such cushion, so the displacement does not stay quiet.

It becomes an immediate demand to be made whole, and there is only one way a government in this fiscal position can meet that demand: off the printing press.

So the booing graduates and the money-printing turn out to be the same story told from opposite ends. A society that will not share the gains of automation through wages and taxes ends up redistributing them anyway, through inflation.

The Same Story We Always Tell

Step back far enough and something clicks into place. This is the same story we have been telling for years, only now seen from the inside.

The world is quietly losing faith in the dollar, and in paper money as a whole.

You can watch it in the one place that cannot spin a press release: central banks voting with their reserves, selling US Treasuries and buying gold. We tracked the retail end of that shift in “Gold out of Stock? But Still in Our Minds” the queues around the block in Asia; the central banks are now doing the same thing at scale.

That is the external symptom of an empire past its peak. And it does not arrive as one dramatic event.

It looks exactly like what we have been describing: a confident newcomer calmly accumulating real assets, while the incumbent debases its paper and argues with itself about who gets what.

Ray Dalio has a name for this. He calls it the late stage of the long-term debt and empire cycle, the point where money-printing stops being a question of whether and becomes a question of when. Seen that way, AI is not the escape hatch from the cycle. On the evidence of its own graduates, it is the accelerant. It pulls the reckoning forward.

America looks to be heading downhill

Source: Ray Dalio

 The Oldest Story There Is

Nolan chose The Odyssey for a reason. It is a three-thousand-year-old story, and we keep retelling it, in every language and every century, because underneath the sea monsters it is really a story about us. The tale does not change. Only the costumes do.

The loss of faith in a currency is that same kind of story.

It has played out in Rome, in Weimar, in a dozen empires that were each certain their paper was the exception.

The machine is new. The plot is ancient: a society is handed a gift it can all see through, refuses to share what the gift produces, papers over the anger by quietly printing money, and one day discovers the money itself is the thing people no longer trust. We argued in “Philosophy eats AI” that the hardest questions this technology raises are not technical but human. This is the hardest of them.

So what do we do with a horse we can all see through? Nolan’s own answer was not to smash it. “Technology”, he said, “is always going to give us great gifts, but it has to be viewed with skepticism, and the motives of the people giving it to us also have to be viewed with skepticism.”

Source: hugodecryptegrandsformats Youtube

It is a stance we share. Healthy skepticism is not fear of progress; it is simply insisting on the oldest and most useful questions there are: who gets the gains, who pays the cost, and how that cost gets paid.

The abundance may be real… But the danger was never that AI destroys every job. It is that the gains pool at the top, with the few who own the machines, while the strain spreads to everyone else. It does not have to erase the work to hollow out the middle. It only has to keep the winnings and pass down the losses.

The gift is genuine. So are the soldiers. Both things are true at once.

And a society that will not share the winnings through wages and taxes ends up sharing the losses anyway, through inflation. The bill always gets paid. So far, Washington keeps paying it at the printing press.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
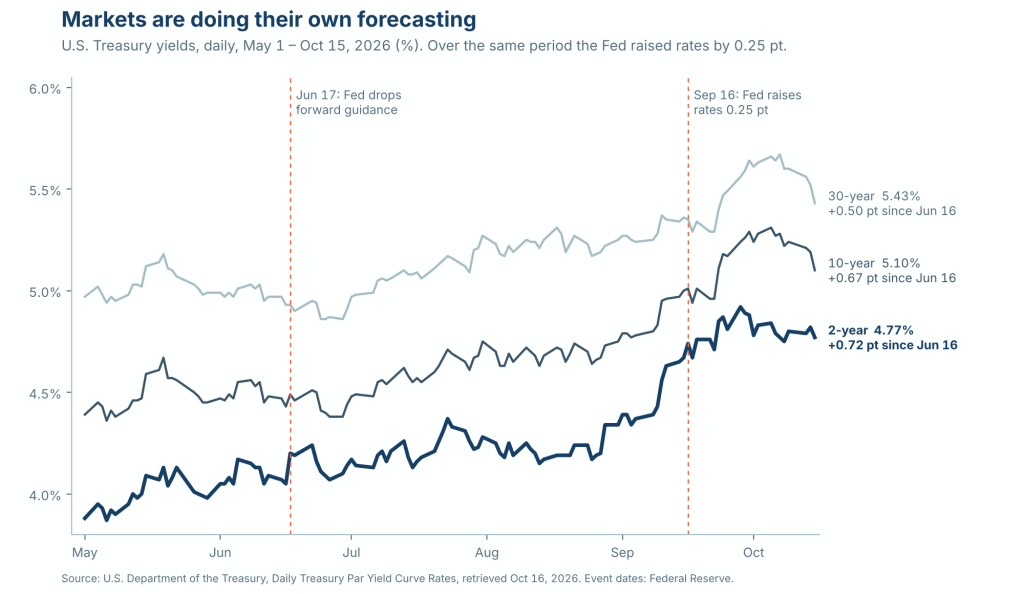


The Trojans, the story goes, had no idea. The horse looked like a gift, so they pulled it inside and celebrated, and by the time the soldiers climbed out it was far too late.

The modern re-run of that story, film director Christopher Nolan suggests, is stranger still.

Asked about artificial intelligence while promoting his new film The Odyssey, he offered an image we have not been able to shake: “AI is a Trojan horse that everybody knows the Greeks are inside. It’s a transparent horse. It’s made of glass. Everybody can see what’s going on inside of there.”

Source: hugodecryptegrandsformats Youtube

He added something sharper still: “I’ve never seen a technology advancing so rapidly that’s been so completely rejected by the public.”

Now, Nolan is a filmmaker, not an economist, and some of what he is reacting to is his own industry’s revolt against AI: the actors, writers and artists who watched it come for their work first and the “AI slop” it produces. But the people it comes for next look a lot like the rest of us.

Sit with what Nolan said for a second. This time the horse is see-through. The crowd can watch the soldiers loading their spears. And the crowd is cheering it through the gates regardless, because the people handing over the gift keep promising that what is inside is not an army but a golden age.

Maybe it is. We are not here to argue that AI is fake or feeble; betting against it has been a fast way to look foolish.

We are here to talk about the part nobody selling the horse wants to linger on: the gap between the day the soldiers climb out and the day the golden age is supposed to arrive.

The Valley Between Two Worlds

Peter Diamandis, who wrote a book literally called Abundance, is one of the great evangelists for the AI future. Even he does not pretend the road is smooth. He describes a stretch he calls “the chasm,” a period in which the old jobs vanish before the new prosperity shows up. He puts it at two to eight years.

Mo Gawdat, the former chief business officer of Google’s moonshot lab, thinks it is longer and darker, calling it a twelve to fifteen year “dystopia” before things get better.


How Mo Gawdat, former chief business officer of Google’s moonshot lab sees what will transpire moving forward

Here is the trouble with a chasm. How green does the far side have to be to justify the crossing? It does not matter how green it is if you cannot get across. Next decade’s abundance does not pay this month’s rent.

And the crossing, on the optimists’ own timelines, is measured not in months but in years. As one MIT study in 2025 found, 95% of companies deploying generative AI had yet to see any measurable return at all. The payoff is a promise. The disruption is already here.

So before we admire the far side, let us be honest about the valley.

Who Falls In First

The first wave is the one everyone pictures: routine, physical, blue-collar work. In the United States alone:

  • Around 2.2 million people drive heavy trucks for a living, before you count couriers and ride-hailing drivers.
  • Roughly 5 million work in food service.
  • Close to 2.8 million staff call centres.

The machines are already here for them. Tesla and BYD have turned the car itself into a robot, and Elon Musk, whose trillion-dollar pay deal back in November 2025 is pegged to shipping a million humanoid Optimus robots, talked cheerfully about a world with more robots than people.

National Bureau of Economic Research on “ How Adaptable are American Workers to AI-Induced Job Displacement”?


The comforting reply has always been that the displaced will retrain into something better. But retrain into what, exactly? Not every laid-off truck driver becomes an AI engineer, and the internet does not need more influencers.

Then comes the part that is genuinely new, and the reason this is a middle-class story and not just a blue-collar one. The wave does not stop at the bottom of the ladder. It climbs.

As Gawdat lays it out, AI comes for the rungs we always assumed were safe:

  • The paralegal.
  • The financial analyst.
  • The radiologist reading a scan.
  • The graphic designer.
  • Even the layer of middle management whose whole job was coordinating other people.

This is not a fringe worry.

Dario Amodei, the chief executive of Anthropic, warns that AI could wipe out half of all entry-level white-collar jobs and push unemployment to 10 to 20% within five years, with finance, law, consulting and tech first in line.

When the person building the thing is the one raising the alarm, it is worth taking the alarm more seriously than the sales pitch.

And here is the part that should stop you cold: it does not take mass unemployment to do real damage. Gawdat puts the threshold bluntly. “At 10 to 20% job displacement, you’re in a very different economy, an economy that is clearly spiraling downwards.”

Remember that consumer spending is close to 70% of the US economy. The workers being automated away are also the customers who buy what the economy makes. What happens to a business when the people it just replaced were also the people who bought its product?

You do not simply create an unemployment problem. You knock the legs out from under demand itself.

The Generation That Did Everything Right

You can already watch the chasm opening, if you know where to look. We sat through the clips from this year’s American graduation season, and they are something to behold. Students booed their own commencement speakers for daring to praise AI.

Eric Schmidt, the former chief executive of Google, was jeered at the University of Arizona.

Picture it: a generation that spent four years and a small fortune on a degree, booing the future being handed to them. It is easy to call that entitled. We think it is something closer to clear-eyed.

The cruelty is in the order of events. The bottom rung of the white-collar ladder, the entry-level job a graduate used to climb, is the first thing sawn off, stranding the people who did everything they were told to do.


How will the youth get jobs? Even those with degrees are losing out

Source: U.S. Census Bureau and U.S. Bureau of Labor Statistics, Current Population Survey (IPUMS)

The Nobel laureate Geoffrey Hinton, often called the godfather of AI, framed the real fear better than any protest sign. The graduates, he suggests, are not frightened of the technology. They are frightened of the bargain: a system in which the gains flow to shareholders and the redundancy flows to them, with no net to catch the fall and no healthcare that is not tied to a job.

As Hinton puts it, AI “will make a few people much richer and most people poorer. That’s not AI’s fault, that is the capitalist system.”

That single sentence reframes the whole debate. The problem in the belly of the glass horse is not the machine. It is how we have decided to share what the machine produces. Gawdat says it plainly: “This is a distribution problem, not a technology one.”

China Cheers, America Boos

Here is where the view widens, because the same glass horse looks completely different depending on which gate it is rolling through.

A 2024 Ipsos survey of more than 23,000 people across 32 countries asked a simple question: do the benefits of AI outweigh the harms? The answers split the world almost neatly in two:

  • China: 83% said yes.
  • Indonesia: 80%.
  • Thailand: 77%.
  • United States: just 39%.
  • The Netherlands, most fearful of all: 36%.

The Anglosphere are the most nervous for AI whereas Asia are most excited

Source: Ipsos

It is worth holding the two pictures side by side. A rising power, China, greets the new machine with 83% optimism, and at the very same time steadily swaps its dollars for gold.

A late-cycle power, the United States, fears the machine, cannot agree on how to share its spoils, and answers every shock by printing more of the very currency the rest of the world is quietly edging away from.

The technology is identical. Only the safety net differs.

Run the same automation through a society with universal healthcare and a real income floor, and losing your job to a robot is a setback rather than a catastrophe. America has no such cushion, so the displacement does not stay quiet.

It becomes an immediate demand to be made whole, and there is only one way a government in this fiscal position can meet that demand: off the printing press.

So the booing graduates and the money-printing turn out to be the same story told from opposite ends. A society that will not share the gains of automation through wages and taxes ends up redistributing them anyway, through inflation.

The Same Story We Always Tell

Step back far enough and something clicks into place. This is the same story we have been telling for years, only now seen from the inside.

The world is quietly losing faith in the dollar, and in paper money as a whole.

You can watch it in the one place that cannot spin a press release: central banks voting with their reserves, selling US Treasuries and buying gold. We tracked the retail end of that shift in “Gold out of Stock? But Still in Our Minds” the queues around the block in Asia; the central banks are now doing the same thing at scale.

That is the external symptom of an empire past its peak. And it does not arrive as one dramatic event.

It looks exactly like what we have been describing: a confident newcomer calmly accumulating real assets, while the incumbent debases its paper and argues with itself about who gets what.

Ray Dalio has a name for this. He calls it the late stage of the long-term debt and empire cycle, the point where money-printing stops being a question of whether and becomes a question of when. Seen that way, AI is not the escape hatch from the cycle. On the evidence of its own graduates, it is the accelerant. It pulls the reckoning forward.

America looks to be heading downhill

Source: Ray Dalio

 The Oldest Story There Is

Nolan chose The Odyssey for a reason. It is a three-thousand-year-old story, and we keep retelling it, in every language and every century, because underneath the sea monsters it is really a story about us. The tale does not change. Only the costumes do.

The loss of faith in a currency is that same kind of story.

It has played out in Rome, in Weimar, in a dozen empires that were each certain their paper was the exception.

The machine is new. The plot is ancient: a society is handed a gift it can all see through, refuses to share what the gift produces, papers over the anger by quietly printing money, and one day discovers the money itself is the thing people no longer trust. We argued in “Philosophy eats AI” that the hardest questions this technology raises are not technical but human. This is the hardest of them.

So what do we do with a horse we can all see through? Nolan’s own answer was not to smash it. “Technology”, he said, “is always going to give us great gifts, but it has to be viewed with skepticism, and the motives of the people giving it to us also have to be viewed with skepticism.”

Source: hugodecryptegrandsformats Youtube

It is a stance we share. Healthy skepticism is not fear of progress; it is simply insisting on the oldest and most useful questions there are: who gets the gains, who pays the cost, and how that cost gets paid.

The abundance may be real… But the danger was never that AI destroys every job. It is that the gains pool at the top, with the few who own the machines, while the strain spreads to everyone else. It does not have to erase the work to hollow out the middle. It only has to keep the winnings and pass down the losses.

The gift is genuine. So are the soldiers. Both things are true at once.

And a society that will not share the winnings through wages and taxes ends up sharing the losses anyway, through inflation. The bill always gets paid. So far, Washington keeps paying it at the printing press.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


This week the Heyokha team is doing something deeply serious and analytical: booking tickets to a movie. Christopher Nolan’s “The Odyssey” lands in cinemas this week, with Matt Damon rowing his way home as the long-suffering Odysseus, and we are far more excited about it than grown professionals probably should admit.

There is one stretch of that voyage we will be watching for in particular.

Odysseus has to steer his ship through a narrow strait guarded on one side by Scylla, a six-headed monster bolted to a rock, and on the other by Charybdis, a whirlpool that swallows ships whole.

The cruel joke of the myth is that there is no clean way through. Sail toward the rock and the monster picks off your crew. Sail toward the whirlpool and you lose the whole ship. All a captain can really do is pick the less catastrophic option and keep narrating confidently so the crew doesn’t panic.

We bring this up because a modern captain is sailing that exact strait right now, and his name is Kevin Warsh.

A Magnificent Speech, and Then Nothing

There is a particular kind of theatre to a Fed chair’s first testimony to Congress, and on July 14 the newly installed Warsh delivered it beautifully.

He invoked the late Alan Greenspan. He spoke of the nation’s founding principles. And then, with the gravity of a man drawing a line in the sand, he vowed that the inflation surge of the last five years “will be a thing of the past.”

It is the kind of line that gets clipped and replayed. Tough. Hawkish. Reassuring, if you are the sort who lies awake worrying about the dollar in your pocket.

There was just one small detail. Having promised to vanquish inflation, Warsh’s committee had, a month earlier, held interest rates exactly where they found them on June 17, at a target range of 3.5% to 3.75%, according to the Federal Reserve’s policy statement that day. No hike. Not even a threatened one. The sheriff rode into town, delivered a stirring speech about law and order, and then declined to load the gun.

How people are reacting to this – probabilities of a rate hike is now below 50%

Source: CME Group

This is not, we should say up front, a knock on the man. Warsh’s hawkish credentials are real. After 2008 he was among the loudest voices warning that quantitative easing, the Fed printing money to buy bonds, had gone too far. Say his name and the market hears discipline.

It duly marked gold down when he arrived, on the theory that the adults were back in charge. But there is a widening gap between what a famous hawk says and what a cornered central bank can actually do. In that gap sits the whole story.

Warsh is stuck between a rock and a hard place. The trouble is that he was stuck before he even sat down.

The Rock: You Must Sound Like Volcker

The rock is inflation, and it has not left the building. Warsh himself conceded that the latest cooler reading was “not mission accomplished.” Prices have been rising uncomfortably for years, households are exhausted by it, and a Fed chair who shrugged at inflation would be run out of Washington by lunchtime.

And “not mission accomplished” is doing a lot of quiet work in that sentence. June’s inflation number, published by the Bureau of Labor Statistics on July 14, did come in cooler than almost anyone expected, at 3.5% for the year against the 3.8% consensus forecast compiled by FactSet, down from 4.2% in May.

But lift the hood and the relief was almost entirely a swoon in energy prices. Petrol fell, and core inflation, the bit that strips out food and fuel, barely moved. That kind of good news has a short shelf life, and it may already be curdling. The U.S. and Iran ceasefire has broken down, Tehran has again threatened to choke the Strait of Hormuz, the maritime tollbooth through which roughly a fifth of the world’s oil passes, according to the U.S. Energy Information Administration, and Brent crude jumped about 11% in a single session to roughly $87 a barrel on July 14 (Fortune, Al Jazeera).

We walked through exactly why these chokepoints matter in our previous blog “Tollbooth at the end of the world”
Energy is the whole reason June looked tame. Energy is also the fastest route for July to look frightening. The rock, in other words, is not going anywhere.

So the rock demands a performance of toughness. It demands the Greenspan invocations, the “resolute commitment to price stability,” the promise that high inflation will become a museum exhibit. Every incentive Warsh has, reputational and political and personal, pushes him to sound like Paul Volcker, the chair who broke inflation’s back in the early 1980s by hiking rates into the stratosphere and cheerfully inducing a recession to do it.


Source: Federal Reserve Bank of St. Louis (FRED), total public debt as % of GDP, late 1970s vs Q1 2026. Other rows reflect Heyokha’s views

The catch is that Volcker could actually swing the hammer. When he took rates to nearly 20%, US federal debt was a svelte thing, around a third of the size of the economy. The government could absorb the pain because the government barely owed anything. Warsh has inherited the same hammer. What he has not inherited is Volcker’s arm.

The Hard Place: The Bill Nobody Can Pay

Which brings us to the whirlpool: the debt.

The United States now owes about $39.4 trillion (Joint Economic Committee, citing Treasury data, July 2026), and this is the part that matters, that pile can only be serviced comfortably at low interest rates. Every percentage point Warsh would add to fight inflation lands directly on the government’s own interest bill, which is already one of the largest single lines in the federal budget.

Raise rates like Volcker and you do not just cool the economy. You risk blowing a hole in the Treasury’s finances.

The debt rolls over at higher interest rates

This is what economists call fiscal dominance, the polite term for the moment when the government’s borrowing needs quietly start steering monetary policy, rather than the other way around. The central bank stops being the disciplinarian and becomes the enabler, because the alternative is a debt crisis.

We laid out the full trajectory in “Banana Republic Yellen” and if anything it has accelerated: once the numbers get big enough, the printing press stops being an emergency tool and becomes a permanent fixture.

Here is the truly awkward bit for our hawk. The tightening he is famous for wanting has already been tried, and it already broke.

Quantitative tightening, the process of shrinking the Fed’s balance sheet by letting its hoard of bonds roll off and draining money back out of the system, quietly died on December 1, 2025. The Fed had spent two years trying to pull cash out.

But when bank reserves got thin enough, the repo market, the overnight plumbing where banks fund themselves, started to groan, and the Fed slammed the process into park. The balance sheet froze at roughly $6.6 trillion, according to the Fed’s weekly H.4.1 data, barely half the pandemic bloat unwound, and since its December 10, 2025 meeting the Fed has been buying Treasury bills again to keep bank reserves ample, under what it calls reserve management purchases.

Read that twice. The system tried to run on less money and could not.

The most hawkish maneuver in the toolkit was attempted, and the market seized up like an engine run dry. So when investors cheer a “hawk” taking over, they are cheering a project that already hit a physical wall, before Warsh even arrived. He is inheriting a ship whose oars only pull in one direction.

When You Cannot Move, Move the Walls

Here is where it gets interesting, and where you can watch a genuinely clever man work an impossible problem. If you are wedged between a rock and a whirlpool and you cannot move toward either, there is exactly one move left: change the shape of the strait.

Warsh has wasted no time. On day one he declined to submit his own “dot” to the Fed’s dot-plot, the chart where each official pencils in where they think rates are heading, breaking a tradition that runs back nearly two decades. The effect, whatever the intent, is a central bank that no longer tells you which way it is leaning. It is harder to be caught missing a target you have stopped announcing.

With Warsh being tight-lipped on his personal guidance, maybe this guy will be out of a job?

Then there is the small matter of the scoreboard itself. Warsh has signaled openness to measuring inflation with a “trimmed-mean” gauge, which strips out the categories that move the most. In fairness, trimmed-mean measures are no gimmick: the Dallas Fed has long published one, and many economists see them as a cleaner read of underlying inflation because they drop extremes in both directions. Still, a chair who changes scoreboards mid-game invites the suspicion that the new one was picked for its kinder view. It can look a bit like declaring yourself on a strict diet after quietly deciding that dessert no longer counts.

And for the grand finale, he has convened five task forces to “start from first principles” and rethink how the Fed does nearly everything: communications, the balance sheet, the data, and the inflation framework itself.

The one on productivity, jobs and AI he handed to Marc Andreessen. Yes, that Andreessen from Andreessen Horowitz. He is the venture capitalist whose firm is one of the most committed backers of the AI boom.

Ask the biggest AI believer in the country whether AI will lift productivity enough to let the Fed cut rates without stoking inflation, and you can probably guess the verdict before the task force even convenes. Warsh has already floated exactly this hope: that the AI build-out will do his tightening for him, letting rates fall without prices rising.

But will AI grow fast enough to get out of the debt? We are not convinced yet given a third of the debt needs to be refinanced

None of these are the acts of a man assembling the brutal, positive-real-rate regime that would actually threaten inflation, or gold. They are the acts of a captain quietly widening the strait so that whatever the current forces him to do next can still be called seamanship.

Back to the perilous journey

Which returns us to Odysseus, and to why the myth is such a good map of the moment.

The whole point of Scylla and Charybdis is that there was no good option, only the least-bad one and a lot of brave talk to get the crew through it. Warsh is navigating the same waters.

On one side, the monster of inflation, which he cannot ignore. On the other, the whirlpool of the debt, which he cannot afford to feed with high rates. He cannot steer hard toward either. So he does the only thing a skilled captain can: he keeps up a confident narration while, we suspect, letting the current carry the ship where it was likely to go anyway.

That is why we think the market has the story upside down. It read the arrival of a celebrated hawk as proof the Fed is serious about discipline. But the hawkishness is a costume the debt cannot afford to wear for real.

We could be wrong, and it is worth saying how. If core inflation keeps cooling without help from energy, or if Warsh does hike and the Treasury absorbs a higher interest bill without a funding scare, the hawk would turn out to have real talons and the market’s first reading would prove right. A faster AI productivity boom would ease the squeeze from both sides too. Those are the signposts we are watching.

Source: CNBC

Appoint the most famous critic of money-printing in the country and the outcome barely changes, because the system has already shown it cannot run on less money. The reputation is not a constraint. It is cover.

This is precisely why, quietly, the people whose job is to hold the world’s reserves keep reaching for the one asset that does not depend on anybody’s promises. Central banks bought more than 1,000 tonnes of gold in each of 2022, 2023 and 2024, and a still-hefty 863 tonnes in 2025, according to the World Gold Council, roughly double their 2010–2021 average of 473 tonnes a year. Even Tether, a company whose entire product is the digital dollar, has been stacking bullion.

When the people closest to the printing press are the ones buying the thing that cannot be printed, the trend is at least worth understanding, even if their reasons, from sanctions risk to reserve diversification, are not every investor’s reasons.

Gold is no one-way bet, though. It pays no income, it has historically struggled when real interest rates rise, and central bank buying already slowed in 2025. It could slow further if prices stay high or reserve managers decide their worries about the dollar were overdone.

Odysseus made it home in the end, but not by defeating the monster or the whirlpool. He survived by accepting that the strait could not be beaten, only crossed, and by being honest with himself about the losses along the way.

A Fed chair can promise to make inflation a thing of the past. He can invoke Greenspan, quote the Framers, and mean every word. But talk is a policy tool with a very short half-life. In our view, the debt is what actually sets the speed limit, and it does not much care how hawkish anyone sounds. That view would be tested if inflation fades on its own, or if markets prove happy to fund the Treasury at higher rates without complaint.

Whichever way the current runs, we will be watching closely. Enjoy the movie.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


This week the Heyokha team is doing something deeply serious and analytical: booking tickets to a movie. Christopher Nolan’s “The Odyssey” lands in cinemas this week, with Matt Damon rowing his way home as the long-suffering Odysseus, and we are far more excited about it than grown professionals probably should admit.

There is one stretch of that voyage we will be watching for in particular.

Odysseus has to steer his ship through a narrow strait guarded on one side by Scylla, a six-headed monster bolted to a rock, and on the other by Charybdis, a whirlpool that swallows ships whole.

The cruel joke of the myth is that there is no clean way through. Sail toward the rock and the monster picks off your crew. Sail toward the whirlpool and you lose the whole ship. All a captain can really do is pick the less catastrophic option and keep narrating confidently so the crew doesn’t panic.

We bring this up because a modern captain is sailing that exact strait right now, and his name is Kevin Warsh.

A Magnificent Speech, and Then Nothing

There is a particular kind of theatre to a Fed chair’s first testimony to Congress, and on July 14 the newly installed Warsh delivered it beautifully.

He invoked the late Alan Greenspan. He spoke of the nation’s founding principles. And then, with the gravity of a man drawing a line in the sand, he vowed that the inflation surge of the last five years “will be a thing of the past.”

It is the kind of line that gets clipped and replayed. Tough. Hawkish. Reassuring, if you are the sort who lies awake worrying about the dollar in your pocket.

There was just one small detail. Having promised to vanquish inflation, Warsh’s committee had, a month earlier, held interest rates exactly where they found them on June 17, at a target range of 3.5% to 3.75%, according to the Federal Reserve’s policy statement that day. No hike. Not even a threatened one. The sheriff rode into town, delivered a stirring speech about law and order, and then declined to load the gun.

How people are reacting to this – probabilities of a rate hike is now below 50%

Source: CME Group

This is not, we should say up front, a knock on the man. Warsh’s hawkish credentials are real. After 2008 he was among the loudest voices warning that quantitative easing, the Fed printing money to buy bonds, had gone too far. Say his name and the market hears discipline.

It duly marked gold down when he arrived, on the theory that the adults were back in charge. But there is a widening gap between what a famous hawk says and what a cornered central bank can actually do. In that gap sits the whole story.

Warsh is stuck between a rock and a hard place. The trouble is that he was stuck before he even sat down.

The Rock: You Must Sound Like Volcker

The rock is inflation, and it has not left the building. Warsh himself conceded that the latest cooler reading was “not mission accomplished.” Prices have been rising uncomfortably for years, households are exhausted by it, and a Fed chair who shrugged at inflation would be run out of Washington by lunchtime.

And “not mission accomplished” is doing a lot of quiet work in that sentence. June’s inflation number, published by the Bureau of Labor Statistics on July 14, did come in cooler than almost anyone expected, at 3.5% for the year against the 3.8% consensus forecast compiled by FactSet, down from 4.2% in May.

But lift the hood and the relief was almost entirely a swoon in energy prices. Petrol fell, and core inflation, the bit that strips out food and fuel, barely moved. That kind of good news has a short shelf life, and it may already be curdling. The U.S. and Iran ceasefire has broken down, Tehran has again threatened to choke the Strait of Hormuz, the maritime tollbooth through which roughly a fifth of the world’s oil passes, according to the U.S. Energy Information Administration, and Brent crude jumped about 11% in a single session to roughly $87 a barrel on July 14 (Fortune, Al Jazeera).

We walked through exactly why these chokepoints matter in our previous blog “Tollbooth at the end of the world”
Energy is the whole reason June looked tame. Energy is also the fastest route for July to look frightening. The rock, in other words, is not going anywhere.

So the rock demands a performance of toughness. It demands the Greenspan invocations, the “resolute commitment to price stability,” the promise that high inflation will become a museum exhibit. Every incentive Warsh has, reputational and political and personal, pushes him to sound like Paul Volcker, the chair who broke inflation’s back in the early 1980s by hiking rates into the stratosphere and cheerfully inducing a recession to do it.


Source: Federal Reserve Bank of St. Louis (FRED), total public debt as % of GDP, late 1970s vs Q1 2026. Other rows reflect Heyokha’s views

The catch is that Volcker could actually swing the hammer. When he took rates to nearly 20%, US federal debt was a svelte thing, around a third of the size of the economy. The government could absorb the pain because the government barely owed anything. Warsh has inherited the same hammer. What he has not inherited is Volcker’s arm.

The Hard Place: The Bill Nobody Can Pay

Which brings us to the whirlpool: the debt.

The United States now owes about $39.4 trillion (Joint Economic Committee, citing Treasury data, July 2026), and this is the part that matters, that pile can only be serviced comfortably at low interest rates. Every percentage point Warsh would add to fight inflation lands directly on the government’s own interest bill, which is already one of the largest single lines in the federal budget.

Raise rates like Volcker and you do not just cool the economy. You risk blowing a hole in the Treasury’s finances.

The debt rolls over at higher interest rates

This is what economists call fiscal dominance, the polite term for the moment when the government’s borrowing needs quietly start steering monetary policy, rather than the other way around. The central bank stops being the disciplinarian and becomes the enabler, because the alternative is a debt crisis.

We laid out the full trajectory in “Banana Republic Yellen” and if anything it has accelerated: once the numbers get big enough, the printing press stops being an emergency tool and becomes a permanent fixture.

Here is the truly awkward bit for our hawk. The tightening he is famous for wanting has already been tried, and it already broke.

Quantitative tightening, the process of shrinking the Fed’s balance sheet by letting its hoard of bonds roll off and draining money back out of the system, quietly died on December 1, 2025. The Fed had spent two years trying to pull cash out.

But when bank reserves got thin enough, the repo market, the overnight plumbing where banks fund themselves, started to groan, and the Fed slammed the process into park. The balance sheet froze at roughly $6.6 trillion, according to the Fed’s weekly H.4.1 data, barely half the pandemic bloat unwound, and since its December 10, 2025 meeting the Fed has been buying Treasury bills again to keep bank reserves ample, under what it calls reserve management purchases.

Read that twice. The system tried to run on less money and could not.

The most hawkish maneuver in the toolkit was attempted, and the market seized up like an engine run dry. So when investors cheer a “hawk” taking over, they are cheering a project that already hit a physical wall, before Warsh even arrived. He is inheriting a ship whose oars only pull in one direction.

When You Cannot Move, Move the Walls

Here is where it gets interesting, and where you can watch a genuinely clever man work an impossible problem. If you are wedged between a rock and a whirlpool and you cannot move toward either, there is exactly one move left: change the shape of the strait.

Warsh has wasted no time. On day one he declined to submit his own “dot” to the Fed’s dot-plot, the chart where each official pencils in where they think rates are heading, breaking a tradition that runs back nearly two decades. The effect, whatever the intent, is a central bank that no longer tells you which way it is leaning. It is harder to be caught missing a target you have stopped announcing.

With Warsh being tight-lipped on his personal guidance, maybe this guy will be out of a job?

Then there is the small matter of the scoreboard itself. Warsh has signaled openness to measuring inflation with a “trimmed-mean” gauge, which strips out the categories that move the most. In fairness, trimmed-mean measures are no gimmick: the Dallas Fed has long published one, and many economists see them as a cleaner read of underlying inflation because they drop extremes in both directions. Still, a chair who changes scoreboards mid-game invites the suspicion that the new one was picked for its kinder view. It can look a bit like declaring yourself on a strict diet after quietly deciding that dessert no longer counts.

And for the grand finale, he has convened five task forces to “start from first principles” and rethink how the Fed does nearly everything: communications, the balance sheet, the data, and the inflation framework itself.

The one on productivity, jobs and AI he handed to Marc Andreessen. Yes, that Andreessen from Andreessen Horowitz. He is the venture capitalist whose firm is one of the most committed backers of the AI boom.

Ask the biggest AI believer in the country whether AI will lift productivity enough to let the Fed cut rates without stoking inflation, and you can probably guess the verdict before the task force even convenes. Warsh has already floated exactly this hope: that the AI build-out will do his tightening for him, letting rates fall without prices rising.

But will AI grow fast enough to get out of the debt? We are not convinced yet given a third of the debt needs to be refinanced

None of these are the acts of a man assembling the brutal, positive-real-rate regime that would actually threaten inflation, or gold. They are the acts of a captain quietly widening the strait so that whatever the current forces him to do next can still be called seamanship.

Back to the perilous journey

Which returns us to Odysseus, and to why the myth is such a good map of the moment.

The whole point of Scylla and Charybdis is that there was no good option, only the least-bad one and a lot of brave talk to get the crew through it. Warsh is navigating the same waters.

On one side, the monster of inflation, which he cannot ignore. On the other, the whirlpool of the debt, which he cannot afford to feed with high rates. He cannot steer hard toward either. So he does the only thing a skilled captain can: he keeps up a confident narration while, we suspect, letting the current carry the ship where it was likely to go anyway.

That is why we think the market has the story upside down. It read the arrival of a celebrated hawk as proof the Fed is serious about discipline. But the hawkishness is a costume the debt cannot afford to wear for real.

We could be wrong, and it is worth saying how. If core inflation keeps cooling without help from energy, or if Warsh does hike and the Treasury absorbs a higher interest bill without a funding scare, the hawk would turn out to have real talons and the market’s first reading would prove right. A faster AI productivity boom would ease the squeeze from both sides too. Those are the signposts we are watching.

Source: CNBC

Appoint the most famous critic of money-printing in the country and the outcome barely changes, because the system has already shown it cannot run on less money. The reputation is not a constraint. It is cover.

This is precisely why, quietly, the people whose job is to hold the world’s reserves keep reaching for the one asset that does not depend on anybody’s promises. Central banks bought more than 1,000 tonnes of gold in each of 2022, 2023 and 2024, and a still-hefty 863 tonnes in 2025, according to the World Gold Council, roughly double their 2010–2021 average of 473 tonnes a year. Even Tether, a company whose entire product is the digital dollar, has been stacking bullion.

When the people closest to the printing press are the ones buying the thing that cannot be printed, the trend is at least worth understanding, even if their reasons, from sanctions risk to reserve diversification, are not every investor’s reasons.

Gold is no one-way bet, though. It pays no income, it has historically struggled when real interest rates rise, and central bank buying already slowed in 2025. It could slow further if prices stay high or reserve managers decide their worries about the dollar were overdone.

Odysseus made it home in the end, but not by defeating the monster or the whirlpool. He survived by accepting that the strait could not be beaten, only crossed, and by being honest with himself about the losses along the way.

A Fed chair can promise to make inflation a thing of the past. He can invoke Greenspan, quote the Framers, and mean every word. But talk is a policy tool with a very short half-life. In our view, the debt is what actually sets the speed limit, and it does not much care how hawkish anyone sounds. That view would be tested if inflation fades on its own, or if markets prove happy to fund the Treasury at higher rates without complaint.

Whichever way the current runs, we will be watching closely. Enjoy the movie.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


On Karrot, Korea’s neighborhood flea market app, someone recently listed a plain grey SK Hynix work jacket for 40,000 won, about 28 dollars. The selling point was not the fabric. The listing called it “the ultimate blind date outfit.”

Karrot a second hand clothing app listing (translated to English)

The meme has already earned its own SNL Korea sketch: a luxury store clerk ignores a scruffy customer until she spots the Hynix logo inside his collar, then snaps into a deep bow.

Korean matchmaking agencies now rank chip workers alongside doctors and lawyers.

And the best joke belongs to a netizen: Hynix employees on blind dates apparently say they work at Samsung first, and only reveal the truth once the match proves worthy.

Korean comedy program “Saturday Night Live” parodying a store saleswoman treating a customer way better after finding out he works at SK Hynix

Why a Work Jacket Beats a Tuxedo

The reason is not subtle. By Reuters’ calculations, SK Hynix employees are projected to receive bonuses averaging around 454,000 dollars this year, if the company hits its expected profit. At Samsung, a memory chip worker on a 52,000 dollar base salary stands to collect roughly 410,000 dollars in bonus, according to a union source cited by Reuters.

If we total Samsung and SK Hynix pay (salary + bonus), it’s a 5 story building worth of cash!

The AI boom needs high-bandwidth memory, Korea makes most of it, and the unions negotiated a fixed slice of operating profit right before that profit went vertical. The receipt for what we wrote in our blog “AI Arms Race” has arrived, and it is being spent: The Guardian reported that at one department store near the fabs, jewelry sales jumped 146% in the first weeks of May, and watch sales 85%.

The Bank of Korea is so alarmed it did something we cannot recall any central bank doing before: it flagged the paychecks of two companies as a national inflation risk. Somewhere in Seoul, a very serious institution is effectively hiking rates against romance.

source: The Next Web

The Statistic Nobody Puts in the Same Headline

Here is the part that deserves a slow clap. Korea’s birthrate, the most famously doomed number in all of economics, just rose for the second year running, to 0.80 babies per woman in 2025 from 0.75 in 2024, according to figures the national statistics office released in February.

source: The Guardian

Demographers credit the echo boomers, the 3.6 million Koreans born in the early 1990s who are now reaching parenthood. Fair enough. But squint at the full picture: a generation hitting family age at the exact moment the economy starts paying young engineers like founders and handing the rest of the country a doubling stock market. Blind dates are booking out, department stores are heaving, and the babies are arriving.

Korea has spent two decades and hundreds of trillions of won trying to engineer this outcome. Subsidies, campaigns, committees, slogans. The results were famously nothing.

Then the chip cycle handed young workers actual money, and suddenly the marriage market is the hottest market in the country. Surprise, surprise: people never needed to be persuaded to build families. They needed to be able to afford them.

And the affording is not only about bonus checks. The deeper shift is that a generation that felt locked out of wealth suddenly has a stake in it, whether through a payslip or a portfolio.

Prosperity Goes Public

Here is why this is bigger than 113,000 lucky employees. A wealth effect from corporate profits is nothing new; what makes Korea’s moment different is that the prosperity is being felt far beyond the fab gates, because it found a transmission mechanism: the stock market.

According to Korea Exchange data, the KOSPI doubled in the first half of 2026, up 101% to close June at 8,476, after topping 9,000 for the first time, with Samsung up about 179% and SK Hynix up about 307%. Along the way, Korea’s market did something nobody had on their bingo card: in late April, by Bloomberg’s count, at $4.04 trillion in market value it overtook the United Kingdom ($3.99 trillion) to become the world’s eighth largest stock market, having already left France behind.

Read that against the GDP tables and it gets better: Korea’s economy is roughly a third the size of Germany’s, yet its stock market now trades in the same league.

How the tables have turned

source: Bloomberg

And here is the detail that makes it a prosperity story rather than a hot-money story: foreigners were not the buyers. Korea Exchange data show foreign investors sold a record net 148 trillion won (about $107 billion) of KOSPI shares in the first half, taking profits.

The bid came from home. Korean retail investors poured a net 99 trillion won into KOSPI shares over the same six months, and the Korea Securities Depository now counts about 14.4 million individual shareholders, more than double the number in 2018 and roughly one in three Korean voters.

Zoom in and the numbers get even more striking:

  • That is more than one in four of all Koreans, babies included
  • In a Statista Consumer Insights survey, 44% of Korean respondents said they had invested in stocks, funds or ETFs in the past year
  • Near the top of the 32 countries surveyed, and well over twice the 17% seen in the United States.

When this market doubles, nearly half the adult population feels it directly.

That is not a niche hobby anymore. That is a constituency, which is why politicians of every stripe suddenly compete on shareholder-friendly reforms. Koreans are buying Korea, and Korea is legislating for Koreans who buy Korea.

More skin in the game now. Retail investors also make up more than half of Korea’s market turnover

source: CLSA

That is the part worth underlining. A bonus enriches an employee. A doubling stock market enriches everyone holding a pension, a retirement account, or a teenage trading-app habit.

The rally has added well over a quadrillion won of market value, a number so large Korean media had to dust off a unit nobody normally uses. This is how a windfall in one industry becomes prosperity an entire country can feel.

Run the comparison honestly and the market wins on almost every axis.

The bonuses, however spectacular, land on about 113,000 badge holders at two companies. The rally lands on everyone: 14 million direct retail accounts, every pension fund, every savings product with equity exposure.

One honest caveat for the economists in the room: per won, bonus cash is probably more spendable. A bonus hits the checking account and feels like income, while stock gains sit unrealized, guarded by loss aversion.

So the consumption punch per won may still favor the paycheck. But the perceived wealth effect, the thing that changes how an entire country feels about its future, belongs overwhelmingly to the market.

A Prescription for the Patient Across the Sea

Which brings us to China, fighting the opposite disease: deflation, price wars, and involution, its own companies competing each other to death while consumers wait for tomorrow’s discount.

Beijing’s prescription so far has been administrative. Anti-involution campaigns, capacity cuts, stern words.

But let us be honest about the mechanism, because the naive reading of Korea would be that the answer is bonus checks. It is not.

You cannot pay 1.4 billion people like memory engineers, and even Korea’s own bonanza directly touches only 113,000 badge holders.

The bonus checks were the spark. The engine is the stock market.

What actually changed the national mood is that one industry’s windfall got amplified through a market that nearly half the adult population owns, so the prosperity arrived in millions of brokerage accounts that never saw a chip bonus.

If you think about it, this is the playbook the United States has run for decades: let the index grind higher, let households feel wealthier, and watch the confidence show up in spending long before any paycheck moves. Korea just joined that club in a single year.

When China Takes the Medicine

We like to think of economies as impossibly complex machines, and mostly they are. But underneath the models sits a very short circuit: people who feel rich spend, marry, and multiply. Korea flipped the switch by accident, and every dial moved at once, from jewelry counters to maternity wards.

Now consider who else is watching this experiment. Beijing has spent years trying to cure deflation with capacity cuts and stern memos, treating the symptom while households stay cautious.

Here is China’s complication: its old prosperity machine is broken. For a generation, Chinese households stored their optimism in apartments. Housing still makes up roughly half of household assets, with only 11% in equities, by Goldman Sachs’ estimate in January, and after five years of falling prices the property engine now runs in reverse.

Every yuan parked in real estate has been quietly shrinking, which is exactly why consumers hoard cash and wait for tomorrow’s discount. Handing people money is only half the cure. They also need somewhere for that money to grow.

Imagine the impact when the switch up to stocks happens

source: CLSA

Beijing appears to have noticed, and picked its next instrument: the stock market.

Policymakers are openly steering household savings out of deposits and property and into equities, and the early data says it is catching: retail participation in A-shares has been climbing steadily since late 2024, household cash moving into the market in step with the index itself.

The arithmetic leaves plenty of room to run, with Goldman estimating more than 14 trillion yuan of new household money looking for a home every single year. Korea found its prosperity in a paycheck, and the stock market multiplied it.

China may be attempting the reverse: start with the stock market, and hope the confidence follows.

Which leaves the question we will be watching for the rest of this decade: if a doubling index can change the mood of 51 million people in Korea, imagine what it can do to the mood of 1.4 billion in China?


Tara Mulia and Nicholas
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
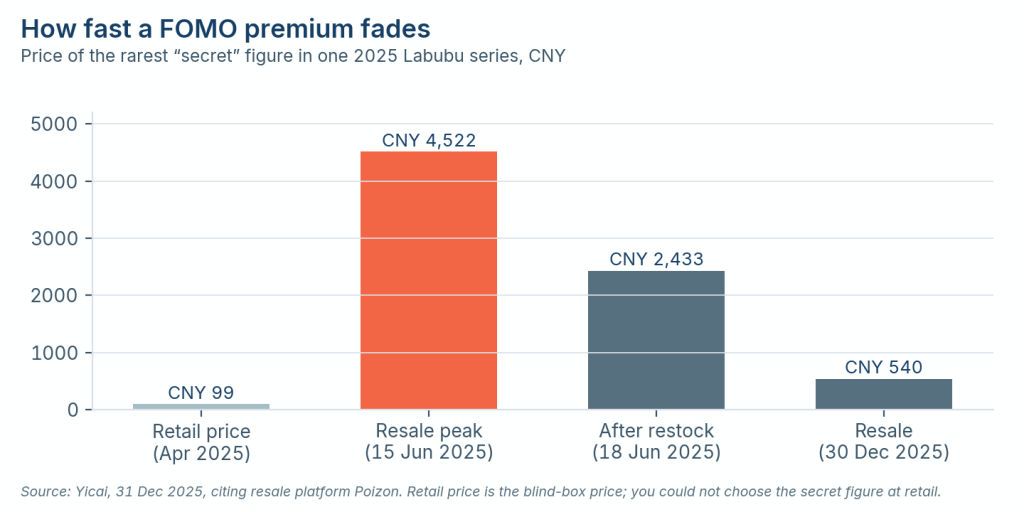


On Karrot, Korea’s neighborhood flea market app, someone recently listed a plain grey SK Hynix work jacket for 40,000 won, about 28 dollars. The selling point was not the fabric. The listing called it “the ultimate blind date outfit.”

Karrot a second hand clothing app listing (translated to English)

The meme has already earned its own SNL Korea sketch: a luxury store clerk ignores a scruffy customer until she spots the Hynix logo inside his collar, then snaps into a deep bow.

Korean matchmaking agencies now rank chip workers alongside doctors and lawyers.

And the best joke belongs to a netizen: Hynix employees on blind dates apparently say they work at Samsung first, and only reveal the truth once the match proves worthy.

Korean comedy program “Saturday Night Live” parodying a store saleswoman treating a customer way better after finding out he works at SK Hynix

Why a Work Jacket Beats a Tuxedo

The reason is not subtle. By Reuters’ calculations, SK Hynix employees are projected to receive bonuses averaging around 454,000 dollars this year, if the company hits its expected profit. At Samsung, a memory chip worker on a 52,000 dollar base salary stands to collect roughly 410,000 dollars in bonus, according to a union source cited by Reuters.

If we total Samsung and SK Hynix pay (salary + bonus), it’s a 5 story building worth of cash!

The AI boom needs high-bandwidth memory, Korea makes most of it, and the unions negotiated a fixed slice of operating profit right before that profit went vertical. The receipt for what we wrote in our blog “AI Arms Race” has arrived, and it is being spent: The Guardian reported that at one department store near the fabs, jewelry sales jumped 146% in the first weeks of May, and watch sales 85%.

The Bank of Korea is so alarmed it did something we cannot recall any central bank doing before: it flagged the paychecks of two companies as a national inflation risk. Somewhere in Seoul, a very serious institution is effectively hiking rates against romance.

source: The Next Web

The Statistic Nobody Puts in the Same Headline

Here is the part that deserves a slow clap. Korea’s birthrate, the most famously doomed number in all of economics, just rose for the second year running, to 0.80 babies per woman in 2025 from 0.75 in 2024, according to figures the national statistics office released in February.

source: The Guardian

Demographers credit the echo boomers, the 3.6 million Koreans born in the early 1990s who are now reaching parenthood. Fair enough. But squint at the full picture: a generation hitting family age at the exact moment the economy starts paying young engineers like founders and handing the rest of the country a doubling stock market. Blind dates are booking out, department stores are heaving, and the babies are arriving.

Korea has spent two decades and hundreds of trillions of won trying to engineer this outcome. Subsidies, campaigns, committees, slogans. The results were famously nothing.

Then the chip cycle handed young workers actual money, and suddenly the marriage market is the hottest market in the country. Surprise, surprise: people never needed to be persuaded to build families. They needed to be able to afford them.

And the affording is not only about bonus checks. The deeper shift is that a generation that felt locked out of wealth suddenly has a stake in it, whether through a payslip or a portfolio.

Prosperity Goes Public

Here is why this is bigger than 113,000 lucky employees. A wealth effect from corporate profits is nothing new; what makes Korea’s moment different is that the prosperity is being felt far beyond the fab gates, because it found a transmission mechanism: the stock market.

According to Korea Exchange data, the KOSPI doubled in the first half of 2026, up 101% to close June at 8,476, after topping 9,000 for the first time, with Samsung up about 179% and SK Hynix up about 307%. Along the way, Korea’s market did something nobody had on their bingo card: in late April, by Bloomberg’s count, at $4.04 trillion in market value it overtook the United Kingdom ($3.99 trillion) to become the world’s eighth largest stock market, having already left France behind.

Read that against the GDP tables and it gets better: Korea’s economy is roughly a third the size of Germany’s, yet its stock market now trades in the same league.

How the tables have turned

source: Bloomberg

And here is the detail that makes it a prosperity story rather than a hot-money story: foreigners were not the buyers. Korea Exchange data show foreign investors sold a record net 148 trillion won (about $107 billion) of KOSPI shares in the first half, taking profits.

The bid came from home. Korean retail investors poured a net 99 trillion won into KOSPI shares over the same six months, and the Korea Securities Depository now counts about 14.4 million individual shareholders, more than double the number in 2018 and roughly one in three Korean voters.

Zoom in and the numbers get even more striking:

  • That is more than one in four of all Koreans, babies included
  • In a Statista Consumer Insights survey, 44% of Korean respondents said they had invested in stocks, funds or ETFs in the past year
  • Near the top of the 32 countries surveyed, and well over twice the 17% seen in the United States.

When this market doubles, nearly half the adult population feels it directly.

That is not a niche hobby anymore. That is a constituency, which is why politicians of every stripe suddenly compete on shareholder-friendly reforms. Koreans are buying Korea, and Korea is legislating for Koreans who buy Korea.

More skin in the game now. Retail investors also make up more than half of Korea’s market turnover

source: CLSA

That is the part worth underlining. A bonus enriches an employee. A doubling stock market enriches everyone holding a pension, a retirement account, or a teenage trading-app habit.

The rally has added well over a quadrillion won of market value, a number so large Korean media had to dust off a unit nobody normally uses. This is how a windfall in one industry becomes prosperity an entire country can feel.

Run the comparison honestly and the market wins on almost every axis.

The bonuses, however spectacular, land on about 113,000 badge holders at two companies. The rally lands on everyone: 14 million direct retail accounts, every pension fund, every savings product with equity exposure.

One honest caveat for the economists in the room: per won, bonus cash is probably more spendable. A bonus hits the checking account and feels like income, while stock gains sit unrealized, guarded by loss aversion.

So the consumption punch per won may still favor the paycheck. But the perceived wealth effect, the thing that changes how an entire country feels about its future, belongs overwhelmingly to the market.

A Prescription for the Patient Across the Sea

Which brings us to China, fighting the opposite disease: deflation, price wars, and involution, its own companies competing each other to death while consumers wait for tomorrow’s discount.

Beijing’s prescription so far has been administrative. Anti-involution campaigns, capacity cuts, stern words.

But let us be honest about the mechanism, because the naive reading of Korea would be that the answer is bonus checks. It is not.

You cannot pay 1.4 billion people like memory engineers, and even Korea’s own bonanza directly touches only 113,000 badge holders.

The bonus checks were the spark. The engine is the stock market.

What actually changed the national mood is that one industry’s windfall got amplified through a market that nearly half the adult population owns, so the prosperity arrived in millions of brokerage accounts that never saw a chip bonus.

If you think about it, this is the playbook the United States has run for decades: let the index grind higher, let households feel wealthier, and watch the confidence show up in spending long before any paycheck moves. Korea just joined that club in a single year.

When China Takes the Medicine

We like to think of economies as impossibly complex machines, and mostly they are. But underneath the models sits a very short circuit: people who feel rich spend, marry, and multiply. Korea flipped the switch by accident, and every dial moved at once, from jewelry counters to maternity wards.

Now consider who else is watching this experiment. Beijing has spent years trying to cure deflation with capacity cuts and stern memos, treating the symptom while households stay cautious.

Here is China’s complication: its old prosperity machine is broken. For a generation, Chinese households stored their optimism in apartments. Housing still makes up roughly half of household assets, with only 11% in equities, by Goldman Sachs’ estimate in January, and after five years of falling prices the property engine now runs in reverse.

Every yuan parked in real estate has been quietly shrinking, which is exactly why consumers hoard cash and wait for tomorrow’s discount. Handing people money is only half the cure. They also need somewhere for that money to grow.

Imagine the impact when the switch up to stocks happens

source: CLSA

Beijing appears to have noticed, and picked its next instrument: the stock market.

Policymakers are openly steering household savings out of deposits and property and into equities, and the early data says it is catching: retail participation in A-shares has been climbing steadily since late 2024, household cash moving into the market in step with the index itself.

The arithmetic leaves plenty of room to run, with Goldman estimating more than 14 trillion yuan of new household money looking for a home every single year. Korea found its prosperity in a paycheck, and the stock market multiplied it.

China may be attempting the reverse: start with the stock market, and hope the confidence follows.

Which leaves the question we will be watching for the rest of this decade: if a doubling index can change the mood of 51 million people in Korea, imagine what it can do to the mood of 1.4 billion in China?


Tara Mulia and Nicholas
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
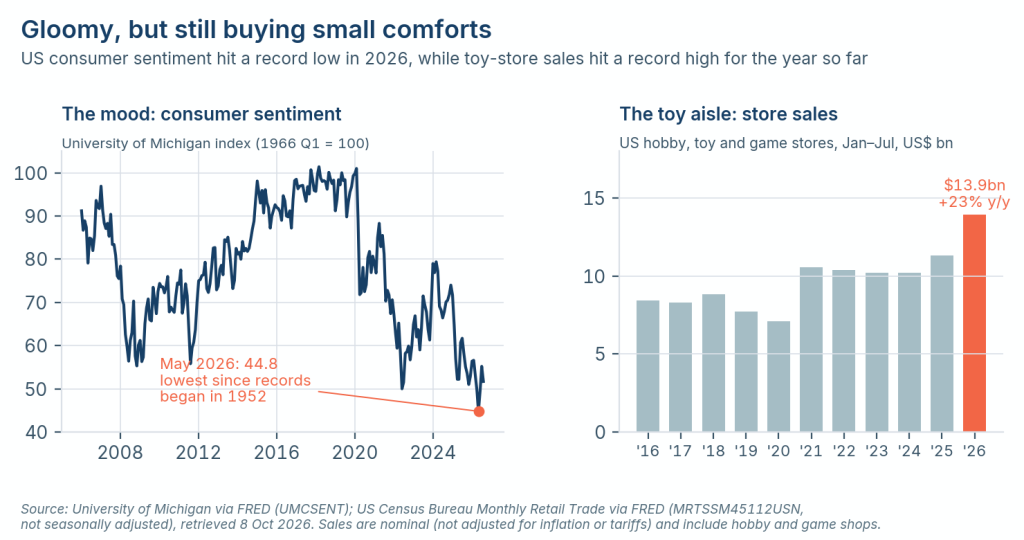


Have you ever wondered how the 2% inflation target got to 2%?

Picture a television studio in New Zealand, 1988. Big hair, boxy suits, the works. The country has spent two decades getting mugged by inflation, which tore through the 1970s and early 1980s and refused to fully sit down even after a painful round of reforms.

The finance minister, Roger Douglas, is on air trying to convince a skeptical public that the central bank will not quietly tolerate rising prices forever. Pressed on what he is actually aiming for, he says he’d like to see inflation somewhere around zero to one percent.

There was no model behind the number, no white paper, no committee. It was the central-banking equivalent of being asked your goal weight and answering, “I dunno, abs?”

Don Brash, the kiwifruit farmer turned central banker who had just taken over the Reserve Bank of New Zealand, later put it plainly: “It was almost a chance remark. The figure was plucked out of the air to influence the public’s expectations.”

1988 comic ridiculing the Reserve Bank of New Zealand’s inflation prediction
Source: Malcolm Walker, Reserve Bank of New Zealand

Brash, as it happens, had personal reasons to loathe inflation. He liked to tell the story of an uncle who sold his apple orchard in 1971, parked the proceeds in long-term government bonds to fund his retirement, and then watched inflation incinerate 90 percent of his life savings by the time those bonds matured. Keep that uncle in mind.

The Reserve Bank Act of 1989 turned the chance remark into a job description. It ordered the finance minister and the central bank to agree on a formal inflation target, handed the bank independence to chase it, and made the goal enforceable by allowing the governor to be fired for missing.

Brash and the finance minister of the day, David Caygill, took Douglas’s zero-to-one, widened it a touch for breathing room, and settled on a band of zero to 2 percent. The law passed in a quick, near-unanimous vote by parliamentarians keen to get home for Christmas.

Here is the punchline: it worked. Inflation was 7.6 percent when the law passed in 1989. By the end of 1991 it was 2 percent. Simply by announcing a number and meaning it, New Zealand talked wages and prices into behaving.
Brash evangelized to fellow central bankers at Jackson Hole, and the converts piled in: Canada in 1991, then Sweden, then Britain. Today roughly 45 countries plus the Euro Area run on an inflation target, and 2 percent has become, in the New York Times’s lovely phrase, “virtually an economic religion.”

The religion, live on air. First thing that appeared on our Bloomberg TV

We mention all this not to dunk on New Zealand, which also gave us excellent lamb and the cinematic “Lord of the Rings”, but because a figure plucked from the air on a Wellington TV set now governs the value of your savings. When a target is arbitrary, it is also negotiable. And the people most exposed to that negotiation are savers.

New Zealand started it first and others began to follow suit
Sources: NYT; World Bank

The Federal Reserve was a late and reluctant convert. Behind the oversized doors of its boardroom in 1995 and 1996, officials argued about whether to copy the Kiwis at all, and if so, what the number should be. Heavyweights like Paul Volcker and Alan Greenspan leaned toward zero, on the logic that a dollar today should buy roughly what a dollar buys in twenty years.

The governor who argued hardest for a positive target of around 2 percent was a woman named Janet Yellen. Her case was the grease-the-wheels argument: a little inflation lets employers quietly trim real wages without the misery of cutting nominal pay, and, crucially, it lets real interest rates go negative when a recession demands it.

“A little inflation permits real interest rates to become negative on the rare occasions when required to counter a recession,” she told the room in 1996. “This could be important.” She had no idea how important.

Yellen won. The Fed privately settled on 2 percent in 1996 and only said so out loud in 2012. And yes, this is the same Janet Yellen from our “Welcome to the Banana Republic,” piece, the one who later ran the Treasury and issued the mountain of debt now straining against that very target.

A Hawk Walks In, and Says Almost Nothing

Which brings us to this week. On June 17, the Federal Reserve held its benchmark rate at 3.5% to 3.75%, the first meeting chaired by Kevin Warsh. No cut. The committee dropped its earlier forecast of a cut this year.

The appointment of a new chairman does matter here as each person leading carries different philosophies which can impact how the Fed will move forward. Kevin Warsh sat on the Fed’s Board of Governors from 2006 to 2011, through the heart of the financial crisis, then spent the years since as one of the institution’s sharpest critics. He argued the Fed had grown too talkative, too wedded to its models, and too comfortable with easy money. That is the tell.

Where Janet Yellen built the machinery of an explicit target, and Jerome Powell leaned into ever more detailed forward guidance, Warsh seems to want the opposite: fewer promises and more discretion. His appointment matters because it hands the keys of the post-2008 transparency project to a man who never quite believed in it.

The median official now pencils in a fed funds rate of 3.8 percent by December, which is to say a hike, with PCE inflation projected at 3.6 percent for the year, nearly double the target. The policy statement was stripped to what Warsh called “a bit shorter, a bit simpler,” and shorn of the “so-called forward guidance” he judged “not well-suited to the current policy conjuncture.”

Source: Fortune

But the real news was what Warsh would not say. While he encouraged his colleagues to keep submitting their forecasts to the famous dot plot, he refused to submit his own. “I have refrained from offering any projections of my own,” he announced, “consistent with my long-held views on the SEP.”

No dot, no roadmap, no breadcrumbs. This is a genuine break. For more than a decade the Fed has practically narrated its own intentions in advance; Warsh prefers what he admires about the Greenspan era, the deliberate fog, the man-behind-the-curtain mystique.

And tucked into the same meeting was the part that should make every saver sit up. Among five new task forces Warsh announced was one charged with re-examining the Fed’s “inflation frameworks” from “first principles,” weighing “the full range of ideas for delivering price stability.”

Why would a central bank want to be less clear about its target just as that target turns inconvenient? Maybe it is humility. Or maybe it has nothing to do with inflation, and everything to do with the size of the bill.

To be clear, none of this means the Fed has decided to raise its inflation target; reviewing a framework is not the same as loosening one, and a review could just as easily change nothing. But history is fairly blunt about the pattern: heavily indebted governments tend, sooner or later, to find reasons to tolerate a little more inflation than they once promised.

The Trillion-Dollar Tenant Nobody Voted For

Here is the number that should be keeping policymakers up at night. The US government is on track to spend roughly $1 trillion on interest payments this fiscal year. That is more than the entire defense budget, which runs around $947 billion, and net interest already overtook defense spending in the first quarter.

Put another way: for every dollar Washington collects in taxes, about 19 cents now goes straight to bondholders before a single road is paved or fighter jet is fueled. Interest costs are running near 3.2% of GDP, eclipsing a record set back in 1991.
The chart below covers only the first eight months of this fiscal year, and even on that partial tally net interest ($742 billion) has already overtaken the military ($600 billion); annualized, it crosses $1 trillion.

Source: Congressional Budget Office

The cruel mechanics are simple: the higher the Fed keeps rates to fight inflation, the more expensive that trillion-dollar tenant becomes. A government this indebted cannot actually afford honestly high interest rates for long. Something has to give, and “raise taxes” and “cut spending” are about as popular as a durian in a crowded elevator. So what’s left?

The option nobody campaigns on: let inflation run a little hot, keep rates a little too low, and let the gap quietly erode the real value of the debt. Economists have a polite name for this. They call it financial repression.

If an arbitrary target really is back on the table, it is at least worth asking which direction a government drowning in interest payments would quietly prefer it to move.

In fairness, this is a lens, not a verdict, and the other side deserves its hearing. There is a serious case for the 2%. A little inflation greases the labor market as Yellen argued for, letting real wages drift down without the bruising fight of cutting paychecks, and it keeps a safe distance from the deflationary trap that a zero target invites. Plenty of thoughtful people argue central banks prize flexibility for reasons that have nothing to do with debt.

We simply find it an interesting and underappreciated way to read the moment, one that happens to matter a great deal if you turn out to be the saver on the other side of the trade. Treat it as a question worth sitting with.

Remember war bonds? The generation that lived through the war certainly does

Remember Brash’s uncle, the one whose retirement bonds got vaporized? He had company, decades earlier and an ocean away as seen in war bonds.

If “captive demand for government debt” sounds abstract, it once had a friendlier face and a patriotic poster campaign. During the Second World War, more than 85 million Americans, over half the population, bought war bonds, lending the government some $185 billion at an implied return of under 3%. A Series E bond cost $18.75 and promised $25 a decade later. It was framed as a duty, and it was one: the bonds helped win the war. But it was also the purest financial repression ever run at scale.

Here is the part the posters left out. The Federal Reserve deliberately capped bond yields near 2.5% from 1942 until the 1951 Treasury-Fed Accord, which is why the bonds could pay so little in the first place. Savers were locked into a fixed yield of under 3%, and with that ceiling in place they had no way to roll into anything higher.

Then, once wartime price controls were lifted, post-war inflation ran into the teens. The saver who answered the call was repaid every promised dollar, but in money that bought meaningfully less than the sum first lent. Over the bond’s ten-year life, a nominal gain of a third was more than erased by inflation, leaving a real loss.

They funded the state at a loss and called it patriotism.

War bonds ads in the New York city subway back in the 1940s
Source: New York Transit Museum.

The Poster Just Changed Fonts

The difference today is one of marketing, not mechanism. Nobody is printing technicolor posters of Uncle Sam asking you to do your duty. Instead the captivity is engineered through plumbing.

Basel rules, the global rulebook that sets how much capital banks must hold, nudge banks to hold government bonds as “safe” assets. Pension and insurance mandates force institutions to park trillions in sovereign debt regardless of yield. Someone’s retirement fund is a war-bond buyer who never saw a poster and never got asked.

The mechanism is identical to 1942: a captive pool of demand for government debt, held at yields that conveniently sit below the rate at which money loses value. The saver still pays. They just don’t get a lapel pin for it. Which is also why we wrote “Invisible Inflation”: if the yardstick that defines “2%” is itself flexible, the repression runs deeper than the headline ever admits.

Know Which Side of the Ledger You’re On

Which brings us back to that television studio in 1988. The lesson isn’t that central bankers are villains. Roger Douglas and Don Brash were trying to tame a genuinely vicious inflation, and the experiment worked. The lesson is humbler and more useful: the rules that govern your savings are not laws of physics handed down from a mountain.

They are human choices, sometimes improvised on live TV, always serving someone’s balance sheet. New Zealand’s gift to the world was visibility about the number. The unsettling thing about this week is a Fed that has stopped telling you what it is thinking, at the exact moment the math gives it every reason to wish for a little more inflation than it would ever admit out loud.

You don’t get a vote in that redistribution. But you do get a choice about what you own. That is the whole reason we keep coming back to real assets: things that can’t be printed, pegged, or talked down on a television interview. Brash’s uncle and the war-bond savers answered the call and were repaid in shrunken dollars. They didn’t have the playbook. You do. The poster has changed fonts, but it is still asking you for the same thing. The only question is whether you read the fine print this time.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share
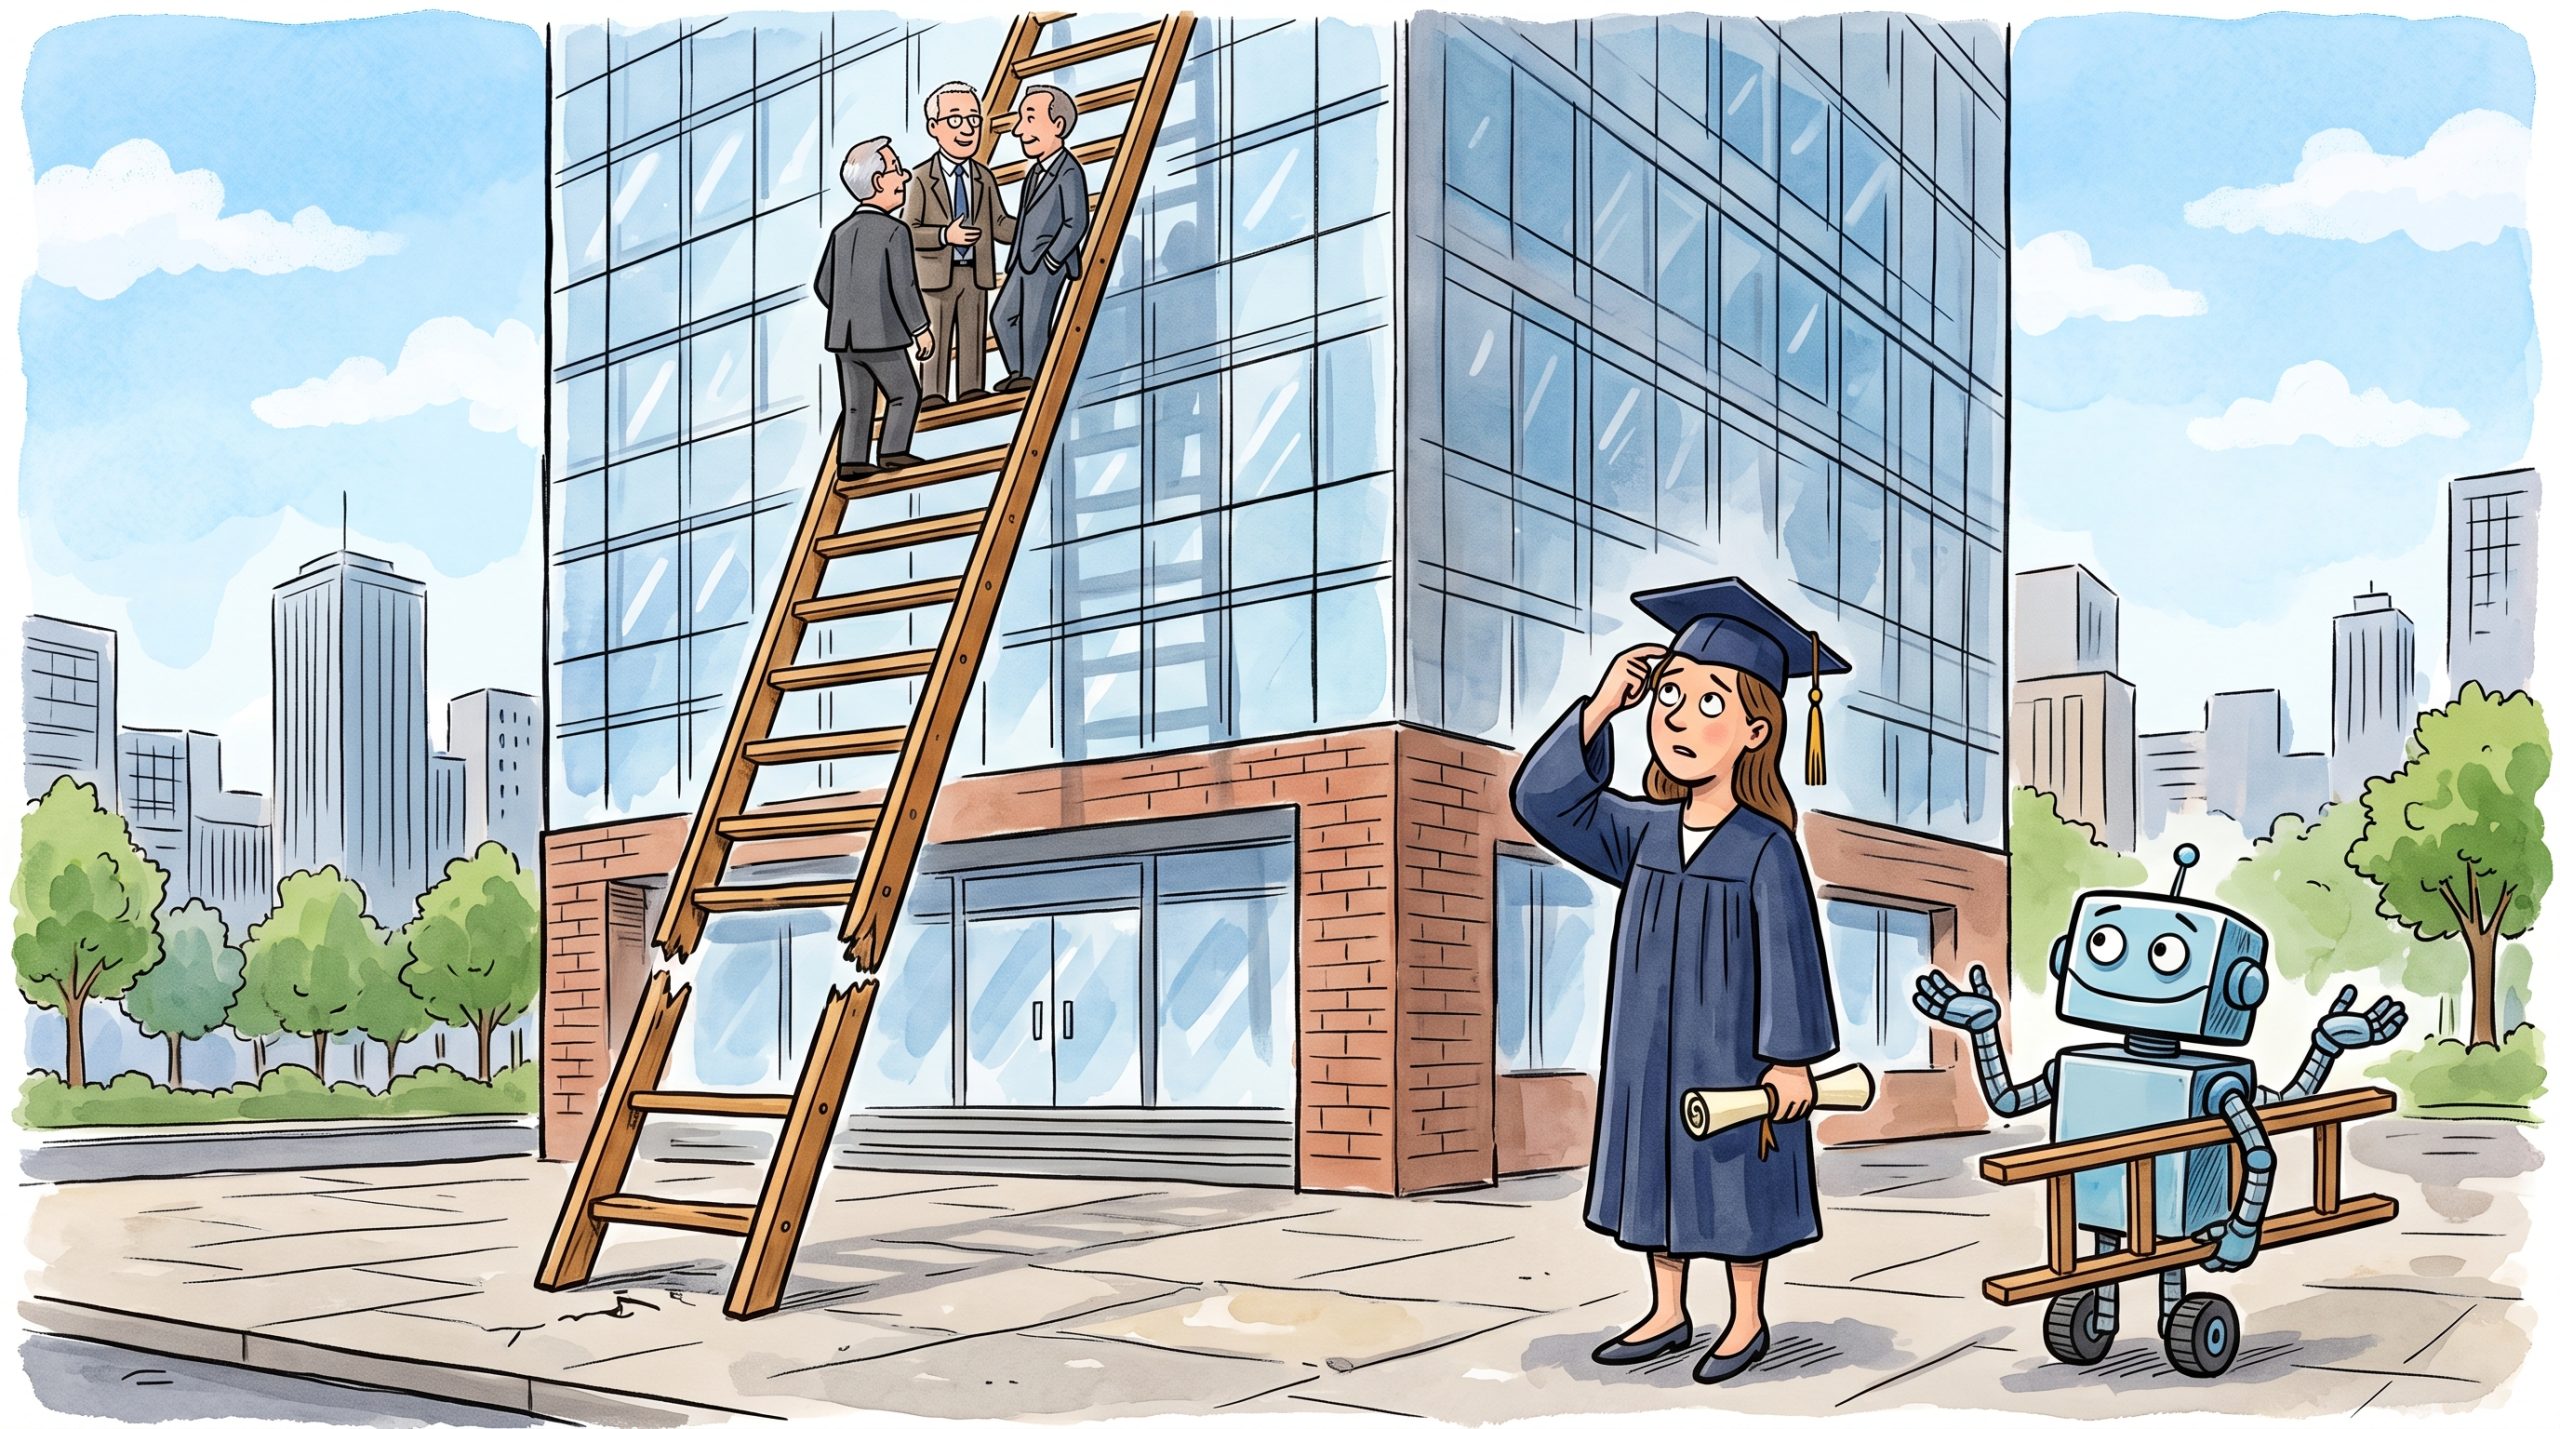


Have you ever wondered how the 2% inflation target got to 2%?

Picture a television studio in New Zealand, 1988. Big hair, boxy suits, the works. The country has spent two decades getting mugged by inflation, which tore through the 1970s and early 1980s and refused to fully sit down even after a painful round of reforms.

The finance minister, Roger Douglas, is on air trying to convince a skeptical public that the central bank will not quietly tolerate rising prices forever. Pressed on what he is actually aiming for, he says he’d like to see inflation somewhere around zero to one percent.

There was no model behind the number, no white paper, no committee. It was the central-banking equivalent of being asked your goal weight and answering, “I dunno, abs?”

Don Brash, the kiwifruit farmer turned central banker who had just taken over the Reserve Bank of New Zealand, later put it plainly: “It was almost a chance remark. The figure was plucked out of the air to influence the public’s expectations.”

1988 comic ridiculing the Reserve Bank of New Zealand’s inflation prediction
Source: Malcolm Walker, Reserve Bank of New Zealand

Brash, as it happens, had personal reasons to loathe inflation. He liked to tell the story of an uncle who sold his apple orchard in 1971, parked the proceeds in long-term government bonds to fund his retirement, and then watched inflation incinerate 90 percent of his life savings by the time those bonds matured. Keep that uncle in mind.

The Reserve Bank Act of 1989 turned the chance remark into a job description. It ordered the finance minister and the central bank to agree on a formal inflation target, handed the bank independence to chase it, and made the goal enforceable by allowing the governor to be fired for missing.

Brash and the finance minister of the day, David Caygill, took Douglas’s zero-to-one, widened it a touch for breathing room, and settled on a band of zero to 2 percent. The law passed in a quick, near-unanimous vote by parliamentarians keen to get home for Christmas.

Here is the punchline: it worked. Inflation was 7.6 percent when the law passed in 1989. By the end of 1991 it was 2 percent. Simply by announcing a number and meaning it, New Zealand talked wages and prices into behaving.
Brash evangelized to fellow central bankers at Jackson Hole, and the converts piled in: Canada in 1991, then Sweden, then Britain. Today roughly 45 countries plus the Euro Area run on an inflation target, and 2 percent has become, in the New York Times’s lovely phrase, “virtually an economic religion.”

The religion, live on air. First thing that appeared on our Bloomberg TV

We mention all this not to dunk on New Zealand, which also gave us excellent lamb and the cinematic “Lord of the Rings”, but because a figure plucked from the air on a Wellington TV set now governs the value of your savings. When a target is arbitrary, it is also negotiable. And the people most exposed to that negotiation are savers.

New Zealand started it first and others began to follow suit
Sources: NYT; World Bank

The Federal Reserve was a late and reluctant convert. Behind the oversized doors of its boardroom in 1995 and 1996, officials argued about whether to copy the Kiwis at all, and if so, what the number should be. Heavyweights like Paul Volcker and Alan Greenspan leaned toward zero, on the logic that a dollar today should buy roughly what a dollar buys in twenty years.

The governor who argued hardest for a positive target of around 2 percent was a woman named Janet Yellen. Her case was the grease-the-wheels argument: a little inflation lets employers quietly trim real wages without the misery of cutting nominal pay, and, crucially, it lets real interest rates go negative when a recession demands it.

“A little inflation permits real interest rates to become negative on the rare occasions when required to counter a recession,” she told the room in 1996. “This could be important.” She had no idea how important.

Yellen won. The Fed privately settled on 2 percent in 1996 and only said so out loud in 2012. And yes, this is the same Janet Yellen from our “Welcome to the Banana Republic,” piece, the one who later ran the Treasury and issued the mountain of debt now straining against that very target.

A Hawk Walks In, and Says Almost Nothing

Which brings us to this week. On June 17, the Federal Reserve held its benchmark rate at 3.5% to 3.75%, the first meeting chaired by Kevin Warsh. No cut. The committee dropped its earlier forecast of a cut this year.

The appointment of a new chairman does matter here as each person leading carries different philosophies which can impact how the Fed will move forward. Kevin Warsh sat on the Fed’s Board of Governors from 2006 to 2011, through the heart of the financial crisis, then spent the years since as one of the institution’s sharpest critics. He argued the Fed had grown too talkative, too wedded to its models, and too comfortable with easy money. That is the tell.

Where Janet Yellen built the machinery of an explicit target, and Jerome Powell leaned into ever more detailed forward guidance, Warsh seems to want the opposite: fewer promises and more discretion. His appointment matters because it hands the keys of the post-2008 transparency project to a man who never quite believed in it.

The median official now pencils in a fed funds rate of 3.8 percent by December, which is to say a hike, with PCE inflation projected at 3.6 percent for the year, nearly double the target. The policy statement was stripped to what Warsh called “a bit shorter, a bit simpler,” and shorn of the “so-called forward guidance” he judged “not well-suited to the current policy conjuncture.”

Source: Fortune

But the real news was what Warsh would not say. While he encouraged his colleagues to keep submitting their forecasts to the famous dot plot, he refused to submit his own. “I have refrained from offering any projections of my own,” he announced, “consistent with my long-held views on the SEP.”

No dot, no roadmap, no breadcrumbs. This is a genuine break. For more than a decade the Fed has practically narrated its own intentions in advance; Warsh prefers what he admires about the Greenspan era, the deliberate fog, the man-behind-the-curtain mystique.

And tucked into the same meeting was the part that should make every saver sit up. Among five new task forces Warsh announced was one charged with re-examining the Fed’s “inflation frameworks” from “first principles,” weighing “the full range of ideas for delivering price stability.”

Why would a central bank want to be less clear about its target just as that target turns inconvenient? Maybe it is humility. Or maybe it has nothing to do with inflation, and everything to do with the size of the bill.

To be clear, none of this means the Fed has decided to raise its inflation target; reviewing a framework is not the same as loosening one, and a review could just as easily change nothing. But history is fairly blunt about the pattern: heavily indebted governments tend, sooner or later, to find reasons to tolerate a little more inflation than they once promised.

The Trillion-Dollar Tenant Nobody Voted For

Here is the number that should be keeping policymakers up at night. The US government is on track to spend roughly $1 trillion on interest payments this fiscal year. That is more than the entire defense budget, which runs around $947 billion, and net interest already overtook defense spending in the first quarter.

Put another way: for every dollar Washington collects in taxes, about 19 cents now goes straight to bondholders before a single road is paved or fighter jet is fueled. Interest costs are running near 3.2% of GDP, eclipsing a record set back in 1991.
The chart below covers only the first eight months of this fiscal year, and even on that partial tally net interest ($742 billion) has already overtaken the military ($600 billion); annualized, it crosses $1 trillion.

Source: Congressional Budget Office

The cruel mechanics are simple: the higher the Fed keeps rates to fight inflation, the more expensive that trillion-dollar tenant becomes. A government this indebted cannot actually afford honestly high interest rates for long. Something has to give, and “raise taxes” and “cut spending” are about as popular as a durian in a crowded elevator. So what’s left?

The option nobody campaigns on: let inflation run a little hot, keep rates a little too low, and let the gap quietly erode the real value of the debt. Economists have a polite name for this. They call it financial repression.

If an arbitrary target really is back on the table, it is at least worth asking which direction a government drowning in interest payments would quietly prefer it to move.

In fairness, this is a lens, not a verdict, and the other side deserves its hearing. There is a serious case for the 2%. A little inflation greases the labor market as Yellen argued for, letting real wages drift down without the bruising fight of cutting paychecks, and it keeps a safe distance from the deflationary trap that a zero target invites. Plenty of thoughtful people argue central banks prize flexibility for reasons that have nothing to do with debt.

We simply find it an interesting and underappreciated way to read the moment, one that happens to matter a great deal if you turn out to be the saver on the other side of the trade. Treat it as a question worth sitting with.

Remember war bonds? The generation that lived through the war certainly does

Remember Brash’s uncle, the one whose retirement bonds got vaporized? He had company, decades earlier and an ocean away as seen in war bonds.

If “captive demand for government debt” sounds abstract, it once had a friendlier face and a patriotic poster campaign. During the Second World War, more than 85 million Americans, over half the population, bought war bonds, lending the government some $185 billion at an implied return of under 3%. A Series E bond cost $18.75 and promised $25 a decade later. It was framed as a duty, and it was one: the bonds helped win the war. But it was also the purest financial repression ever run at scale.

Here is the part the posters left out. The Federal Reserve deliberately capped bond yields near 2.5% from 1942 until the 1951 Treasury-Fed Accord, which is why the bonds could pay so little in the first place. Savers were locked into a fixed yield of under 3%, and with that ceiling in place they had no way to roll into anything higher.

Then, once wartime price controls were lifted, post-war inflation ran into the teens. The saver who answered the call was repaid every promised dollar, but in money that bought meaningfully less than the sum first lent. Over the bond’s ten-year life, a nominal gain of a third was more than erased by inflation, leaving a real loss.

They funded the state at a loss and called it patriotism.

War bonds ads in the New York city subway back in the 1940s
Source: New York Transit Museum.

The Poster Just Changed Fonts

The difference today is one of marketing, not mechanism. Nobody is printing technicolor posters of Uncle Sam asking you to do your duty. Instead the captivity is engineered through plumbing.

Basel rules, the global rulebook that sets how much capital banks must hold, nudge banks to hold government bonds as “safe” assets. Pension and insurance mandates force institutions to park trillions in sovereign debt regardless of yield. Someone’s retirement fund is a war-bond buyer who never saw a poster and never got asked.

The mechanism is identical to 1942: a captive pool of demand for government debt, held at yields that conveniently sit below the rate at which money loses value. The saver still pays. They just don’t get a lapel pin for it. Which is also why we wrote “Invisible Inflation”: if the yardstick that defines “2%” is itself flexible, the repression runs deeper than the headline ever admits.

Know Which Side of the Ledger You’re On

Which brings us back to that television studio in 1988. The lesson isn’t that central bankers are villains. Roger Douglas and Don Brash were trying to tame a genuinely vicious inflation, and the experiment worked. The lesson is humbler and more useful: the rules that govern your savings are not laws of physics handed down from a mountain.

They are human choices, sometimes improvised on live TV, always serving someone’s balance sheet. New Zealand’s gift to the world was visibility about the number. The unsettling thing about this week is a Fed that has stopped telling you what it is thinking, at the exact moment the math gives it every reason to wish for a little more inflation than it would ever admit out loud.

You don’t get a vote in that redistribution. But you do get a choice about what you own. That is the whole reason we keep coming back to real assets: things that can’t be printed, pegged, or talked down on a television interview. Brash’s uncle and the war-bond savers answered the call and were repaid in shrunken dollars. They didn’t have the playbook. You do. The poster has changed fonts, but it is still asking you for the same thing. The only question is whether you read the fine print this time.


Tara Mulia
For more blogs like these, subscribe to our newsletter here!


Important information

This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.

Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.

Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.

Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.


Admin heyokha


Share


Stay Connected with Heyokha

Sign up to receive insights, updates, and perspectives directly from Heyokha

Stay Connected with Heyokha

Sign up to receive insights, updates, and perspectives directly from Heyokha

Heyokha Footer Logo

We drive our mission with an exceptional culture through applying a growth mindset where holistic and on the ground research is at our core.

Help
×

Terms & Conditions

You must read the following information before proceeding. By accessing this website and any pages thereof, you acknowledge that you have read the following information and accept the terms and conditions set out below and agree to be bound by such terms and conditions. If you do not agree to such terms and conditions, please do not access this website or any pages thereof.

The website has been prepared by Heyokha Brothers Limited and is solely intended for informational purposes and should not be construed as an inducement to purchase or sell any security, product, service, or investment. The Site does not solicit an offer to buy or sell any financial instrument or enter into any agreement. It is important to note that the opinions expressed on the Site are not considered investment advice, and it is recommended that individuals seek independent advice as needed to address their specific objectives, financial situation, or needs. It is the responsibility of the persons who access this website to observe all applicable laws and regulations.

The Site offers general information exclusively and does not consider the individual circumstances of any person. The data, opinions, and estimates presented on the Site are current as of the publication date and are subject to changes without notice. Additionally, it is possible that such information may become obsolete with time.

Intended Users

The content presented on this website is exclusively intended for authorized intermediaries and qualified investors within Hong Kong, such as institutional investors, professional investors, and accredited investors (as defined under the SFO). It is not intended for retail investors or individuals located outside of Hong Kong.

The products and services mentioned on this website may or may not be authorized or registered for distribution in a particular jurisdiction and may not be suitable for all investor types. It is important to note that this website is not intended to constitute an offer or solicitation, nor is it directed toward individuals if the provider of the information is prohibited by any law of any jurisdiction from making the information available. Moreover, the website is not intended for any use that would violate local laws or regulations. The provider of the information is not permitted to promote any products or services mentioned on this website in jurisdictions where such promotion would be prohibited.

If you are not a qualified investor or licensed intermediary in Hong Kong, you should not proceed any further.

No Investment Advice

The information provided on this Website is for informational purposes only and should not be considered as investment advice or a recommendation to buy, sell, hold, or transact in any investment. It is strongly recommended that individuals seek professional investment advice before making any investment decisions.

The information presented on this Website does not consider the investment objectives, specific needs, or financial situations of any investor. It is important to note that nothing on this Website is intended to constitute financial, legal, accounting, or tax advice.

Before making any investment decision, individuals should carefully consider whether an investment aligns with their investment objectives, specific needs, and financial situation. This should also include informing oneself of any potential tax implications, legal requirements, foreign exchange restrictions, or exchange control requirements that may be relevant to an investment based on the laws of one’s citizenship, residence, or domicile. If there is any doubt regarding the information on this Website, it is recommended that individuals seek independent professional financial advice.

It is important to note that any opinion, comment, article, financial analysis, market forecast, market commentary, or other information published on the Website is not binding on Heyokha or its affiliates, and they are not responsible for the information, opinions, or ideas presented.

Obligations and Resposibilities of Users

Users are solely responsible for protecting and backing up their data and equipment, as well as taking reasonable precautions against any computer virus or other destructive elements. Additionally, users must ensure that their access to the Site is adequately secured against unauthorized access.

Users are prohibited from using the Site for any unlawful, defamatory, offensive, abusive, indecent, menacing, or threatening purposes, or in any way that infringes upon intellectual property rights or confidentiality obligations. Furthermore, users may not use the Site to cause annoyance, inconvenience, or anxiety to others, or in any way that violates any applicable laws or regulations.

Users must comply with any terms notified to them by third-party suppliers of data or services to the Site. This may include entering into a direct agreement with such third parties in respect of their use of the dat

Third-Party Content

This website may contain Third Party Content or links to websites maintained by third parties that are not affiliated with Heyokha. Heyokha does not participate in the preparation, adoption, or editing of such third-party materials and does not endorse or approve such content, either explicitly or implicitly. Any opinions or recommendations expressed on third party materials are solely those of the independent providers and not of Heyokha. Heyokha is not responsible for any errors or omissions relating to specific information provided by any third party.

Although Heyokha aims to provide accurate and timely information to users, neither Heyokha nor the Third-Party Content providers guarantee on the accuracy, timeliness, completeness, usefulness, or any other aspect of the information presented. Heyokha is not responsible or liable for any content, including advertising, products, or other materials on or available from third party sites. Users access and use Third Party content is at their own risk, and it is provided for informational purposes only. Both Heyokha and the Third-Party shall not be liable for any loss or damage arising from users’ reliance upon such information.

Intellectual Property Rights

The content of this website is subject to copyright and other intellectual property laws. All trademarks, service marks, logos, and brand features displayed on the website are owned by their respective owners, except as explicitly noted. Users may use the information on this website and reproduce it for personal reference only. However, reproduction, distribution, transmission, incorporation in any other database, document, or material, and sale or distribution of any part of the contents of the website is strictly prohibited. Users may download or print individual sections of the website for personal use and information only, provided they are legally entitled to access the material and retain all copyright and other proprietary notices.

Any unauthorized use of the content, trademarks, service marks, or logos displayed on the website may violate copyright, trademark, or other intellectual property laws, as well as laws of privacy and publicity and communications. Any reference or link to any specific commercial product, process, or service by trade name, trademark, manufacturer, or otherwise, does not necessarily constitute or imply its endorsement, recommendation, or favouring by our company.

We provide such references or links solely for the convenience of our users and to provide additional information. Our company is not responsible for the accuracy, legality, or content of any external website or resource linked to or referenced from our website. Users are solely responsible for complying with the terms and conditions of any external websites or resources.

Cookies

In order to enhance user experience and simplify future visits, this website may utilize cookies to track your activity. However, if you do not want to store cookies on your device, you can disable them by adjusting your browser’s security settings.

Data Privacy

Please read our Privacy Statement before providing Heyokha with any personal information on this website. By providing any personal information on this website, you will be deemed to have read and accepted our Privacy Statement.

Use of Website

The information contained on the website is accurate only as of the date of publication and does not constitute investment advice or recommendations. While certain tools available on the website may provide general investment or financial analyses based upon personalized input, such results are for information purposes only, and users should refer to the assumptions and limitations relevant to the use of such tools as set out on the website. Users are solely responsible for determining whether any investment, security or strategy, or any other product or service is appropriate or suitable for them based on their investment objectives and personal and financial situation. Users should consult their independent professional advisers if they have any questions. Any person considering an investment should seek independent advice on the suitability or otherwise of the particular investment.

Disclaimer of Liability Heyokha makes no warranty as to the accuracy, completeness, security, and confidentiality of information available through the website. Heyokha, its affiliates, directors, officers, or employees accept no liability for any errors or omissions relating to information available through the website or for any damages, losses or expenses arising in connection with the website, whether direct or indirect, arising from the use of the website or its contents. Heyokha also reserves the right to modify, suspend, or discontinue the website at any time without notice. Heyokha shall not be liable for any such modification, suspension, or discontinuance.

×

Data Privacy Terms and Conditions

Personal Information Collection Statement:

Pursuant to the Personal Data (Privacy) Ordinance (the ‘Ordinance’), Heyokha Brothers Limited is fully committed to safeguarding the privacy and security of personal information in compliance with all relevant laws and regulations. This statement outlines how we collect, use, and protect personal information provided to us.

Collection of Personal Information:

We collect and maintain personal information, in a manner consistent with all relevant laws and regulations. We take necessary measures to ensure that personal information is correct and up to date. Personal information will only be used for the purpose of utilization and will not be disclosed to third parties (except our related parties e.g.: Administrators) without consent from the individual, except for justifiable grounds as required by laws and regulations.

We may collect various types of personal data from or about you, including:

  • Your name
  • Your user names and passwords
  • Contact information, including address, email address and/or telephone number
  • Information relating to your engagement with material that we publish or otherwise provide to you
  • Records of our interactions with you, including any messages you send us, your comments and questions and any other information you choose to provide.

The Company may automatically collect information about you from computer or internet browser through the use of cookies, pixel tags, and other similar technologies to enhance the user experience on its websites. Third parties may be used to collect personal data and information indirectly through monitoring activities conducted by the Company or on its behalf.

Company does not knowingly collect personal data from anyone under the age of 18 and does not seek to collect or process sensitive information unless required or permitted by law and with express consent.

Uses of your Personal Data:

We may use your personal data for the purposes it was provided and in connection with our services as described below:

  • Provide products/services or info as requested or expected.
  • Fulfill agreements and facilitate business dealings.
  • Manage relationships, analyse websites and communications, and merge personal data for relevance.
  • Support and improve existing products/services, and plan/develop new ones.
  • Count/recognize website visitors and analyse usage.
  • To comply with and assess compliance with applicable laws, rules and regulations and internal policies and procedures.
  • Use information for any other purpose with consent.

Protection of Personal Information:

We provide thorough training to our officers and employees to prevent the leakage or inappropriate use of personal information and provide information on a need-to-know basis. Managers in charge for controls and inspections are appointed, and appropriate control systems are established to ensure the privacy and security of personal information.

In the event that personal information is provided to an external contractor (e.g.: Administrator), we take responsibility for ensuring that the external contractor has proper systems in place to protect the privacy of personal information.

Third parties disclosure of Personal Information:

Personal information held by us relating to an individual will be kept confidential but may be provided to third parties the following purpose:

  • Comply with applicable laws or legal processes.
  • Investigate and prevent illegal activity, fraud, or violations of terms and conditions.
  • Protect and defend legal rights or defend against legal claims.
  • Facilitate business or asset transactions, such as financing, mergers, acquisitions, or bankruptcy.
  • With our related parties (e.g.: administrators) that are subject to appropriate data protection obligations
  • Representatives, agents or custodians appointed by the client (e.g.: Auditors, accountant)

Retention of Personal Information:

Disclosure, correction and termination of usage shall be carried out upon request of an individual in accordance with relevant laws and regulations.

Personal information collected will be retained for no longer than is necessary for the fulfilment of the purposes for which it was collected as per applicable laws and regulations.

Rights of the Individual:

Under relevant laws and regulations, any individual has the right to request access to any of the personal data that we hold by submitting a written request. Individuals are also entitled to request to correct, cancel or delete any of the personal data we hold if they believe such information is inaccurate, out of date or we no longer have a legitimate interest or lawful justification to retain or process.

×

Disclaimer

Heyokha Brothers Limited is the issuer of this website and holds Type 4 (advising on securities) and Type 9 (asset management) licenses issued by the Securities and Futures Commission in Hong Kong.

The information provided on this website has been prepared solely for licensed intermediaries and qualified investors in Hong Kong, including professional investors, institutional investors, and accredited investors (as defined under the Securities and Futures Ordinance). The information provided on this website is for informational purposes only and should not be construed as investment advice, nor an offer to sell or a solicitation of an offer to buy any security, investment product, or service.

Investment involves risk and investors may lose their entire investment. Investors are advised to seek professional advice before making any investment decisions. Past performance is not indicative of future performance and the value of investments may fluctuate. Please refer to the offering document(s) for
details, including the investment objectives, risk factors, and fees and charges.

Heyokha Brothers Limited reserves the right to amend, update, or remove any information on this website at any time without notice. By accessing and using this website, you agree to be bound by the above terms and conditions.

Heyokha Footer Logo

We drive our mission with an exceptional culture through applying a growth mindset where holistic and on the ground research is at our core.

Publications
Help
×

Thank you for subscribing!

You will now gain access to our latest insights, updates, and carefully selected stories, designed to keep you informed and ahead of the curve.