Admin heyokha
Share
Admin heyokha
Share
Share


Share
How Tether quietly became one of the world’s biggest gold holders, and what it signals about the future of money
When we last wrote about stablecoins, we framed them as chips at a casino, and later as claw machine tokens in a rebuilt monetary arcade. They were becoming infrastructure quietly, steadily. But what happens when that infrastructure decides to hoard bullion?
Tether, the world’s largest stablecoin issuer, has quietly become one of the most aggressive gold buyers in the world. Not a central bank. Not a sovereign wealth fund. A crypto company with a token named after a rope.
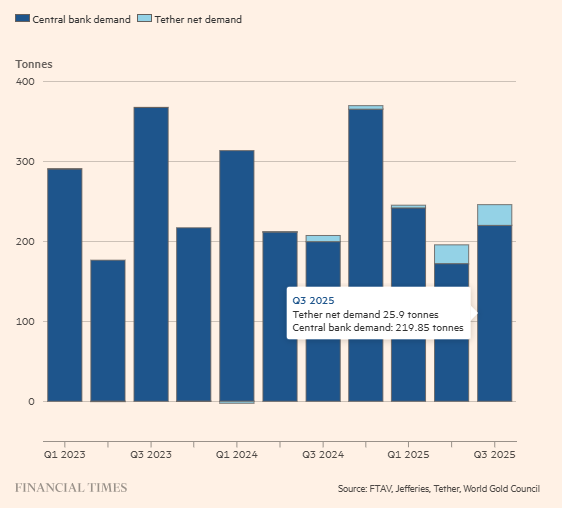
Gold purchases by quarter. Tether bought close to 12% of what the central banks were buying
Source: Financial Times
As of Q3 2025, Tether holds more than 116 tonnes of physical gold. That’s more than South Korea, Hungary, or Greece. According to Jefferies, that makes it the largest gold holder outside of central banks. Yes, probably bigger than your gold ETF. Bigger than most sovereigns. And with roughly $15 billion in projected profits this year, they’re just getting started.
It’s the most curious subplot in the financial system’s ongoing identity crisis: a crypto stablecoin company, built to track the U.S. dollar, is becoming one of the most aggressive buyers of the very metal that signals distrust in fiat.
It would be hilarious if it weren’t also brilliant.
How can Tether afford to buy this much gold?
It starts with its business model. Tether issues USDT, a dollar-pegged token backed mostly by U.S. Treasury bills. The company earns interest on those bills but pays zero interest to USDT holders. In a world of 5% base rates and $112 billion in reserves, that spread is pure profit. We suppose they’re putting it to good use.
In Q3 2025 alone, Tether bought 26 tonnes of gold—nearly 12% of global central bank demand and about 2% of total gold demand. If Tether ploughs half its profits into bullion, that pace could double.
But it’s not just bars in a vault.
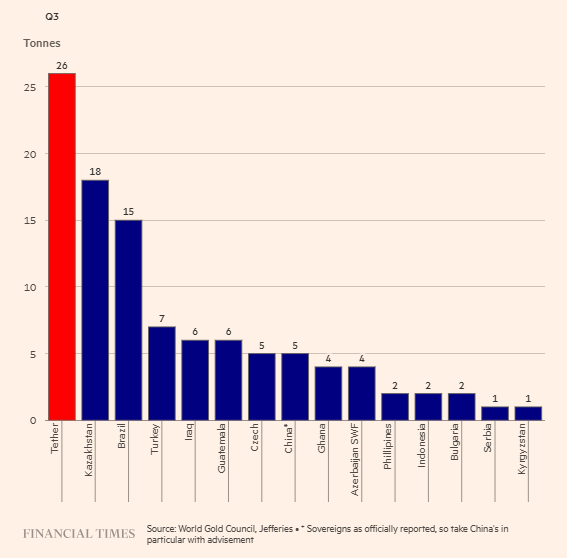
2025 net gold purchases, Tether vs select central banks
Source: Financial Times
Tether has begun deploying capital across the gold supply chain, from streaming and royalty companies to talks with mining operators and refiners.
In June, it acquired a minority stake in Toronto-listed Elemental Altus for $105 million. Later in the year, it invested another $100 million as the firm merged with EMX Royalty.
Tether has also been in discussions with gold-mining investment vehicles such as Terranova Resources, although no deal has materialized yet.
The goal seems clear: Tether doesn’t just want to own gold. It wants gold exposure with leverage, cash flow, and upstream access. Think royalties, not just vaults.
This echoes what we’ve seen in recent years in China, where companies like Xiaomi and BYD began as consumers of critical materials, then became stakeholders in upstream supply chains. It’s all part of building resilience into the foundation of your business.
Tether’s relationship with gold isn’t new. It launched XAUt, its gold-backed stablecoin, in 2020. Each token represents one troy ounce of physical gold, stored in Swiss vaults.
For most of its existence, XAUt was a side project. But that may be changing.
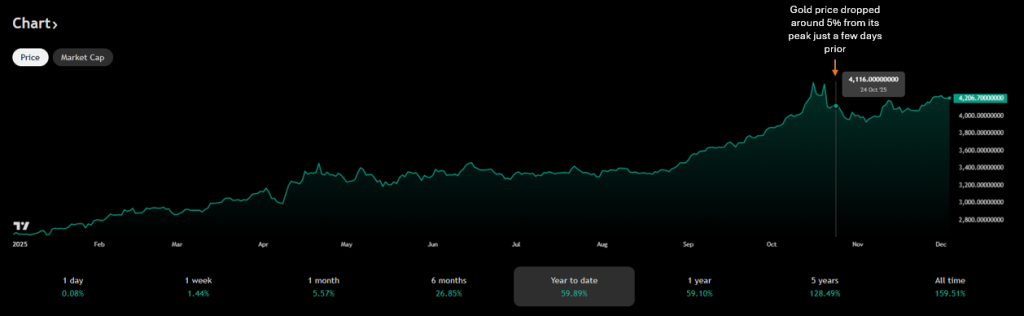

Despite gold price correction, Tether market cap increased by 0.54 billion indicating strong demand
Source: TradingView, Heyokha Research
Since August 2025, blockchain data suggests Tether added more than 275,000 ounces of gold to XAUt’s reserves. The token’s market cap has doubled over the past six months, now sitting between $1.5 to $2.1 billion.
XAUt and Paxos’ PAXG (another tokenized form of gold) together make up around 90% of the entire tokenized gold market, which is still small ($3–3.9 billion total), but growing. XAUt leads with about 49–54% market share.
Still, it’s early days. For all the hype, tokenized gold remains a tiny sliver of global gold markets, which settle over $60 billion daily.
But the use case is compelling.
Good question. Here’s how XAUt stacks up:
Compared to physical gold, XAUt offers:
But it also comes with:
Compared to “digital gold” like ETFs or app-based gold accounts, XAUt:
But:
It’s not better or worse. It’s built for a different user. If you already operate in crypto, XAUt feels like a natural extension. If your gold sits in a retirement account, it probably stays there.
The real question: will tokenized gold ever cross over?
We have explored this idea before in our blog, “Stablecoins: Genius or Just…Stable?”. We warned that stablecoins could evolve from dollar mirrors into asset-backed financial rails with their own monetary dynamics. If you ever need a refresher on how Stablecoins work, we got your back: “Stablecoins 101”.
All this to circle back on a thesis we have also explored and have been harping on – fiat debasement pushes the appeal of gold higher. You can read our thoughts in depth in our “Gold: The Return of Real Money” report.
Tether, it turns out, is acting on that thesis with alarming precision. A crypto company built on fiat liquidity is quietly becoming a force in the real-asset world.
This story is far from over.
Tether’s bullion buying already moves markets at the margin. If its 2025 profit estimates hold and the company keeps scaling gold exposure, it could soon rival the annual net purchases of more central banks.
Whether XAUt becomes a widely used digital gold standard is still uncertain. But that’s not the point.
The point is this: while most stablecoin players are debating compliance frameworks, Tether is quietly building a gold-backed war chest, a commodity lending book, and upstream access to the world’s oldest monetary metal.
And when the next currency crisis hits, the company that started by pegging to fiat might just be the one holding the hardest collateral in town.
As we like to say at Heyokha: in a world of soft money and harder choices, real money has a way of resurfacing.
Tara Mulia
For more blogs like these, subscribe to our newsletter here!
Important information
This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.
Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.
Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.
Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.
Share
How Tether quietly became one of the world’s biggest gold holders, and what it signals about the future of money
When we last wrote about stablecoins, we framed them as chips at a casino, and later as claw machine tokens in a rebuilt monetary arcade. They were becoming infrastructure quietly, steadily. But what happens when that infrastructure decides to hoard bullion?
Tether, the world’s largest stablecoin issuer, has quietly become one of the most aggressive gold buyers in the world. Not a central bank. Not a sovereign wealth fund. A crypto company with a token named after a rope.
Gold purchases by quarter. Tether bought close to 12% of what the central banks were buying
Source: Financial Times
As of Q3 2025, Tether holds more than 116 tonnes of physical gold. That’s more than South Korea, Hungary, or Greece. According to Jefferies, that makes it the largest gold holder outside of central banks. Yes, probably bigger than your gold ETF. Bigger than most sovereigns. And with roughly $15 billion in projected profits this year, they’re just getting started.
It’s the most curious subplot in the financial system’s ongoing identity crisis: a crypto stablecoin company, built to track the U.S. dollar, is becoming one of the most aggressive buyers of the very metal that signals distrust in fiat.
It would be hilarious if it weren’t also brilliant.
How can Tether afford to buy this much gold?
It starts with its business model. Tether issues USDT, a dollar-pegged token backed mostly by U.S. Treasury bills. The company earns interest on those bills but pays zero interest to USDT holders. In a world of 5% base rates and $112 billion in reserves, that spread is pure profit. We suppose they’re putting it to good use.
In Q3 2025 alone, Tether bought 26 tonnes of gold—nearly 12% of global central bank demand and about 2% of total gold demand. If Tether ploughs half its profits into bullion, that pace could double.
But it’s not just bars in a vault.
2025 net gold purchases, Tether vs select central banks
Source: Financial Times
Tether has begun deploying capital across the gold supply chain, from streaming and royalty companies to talks with mining operators and refiners.
In June, it acquired a minority stake in Toronto-listed Elemental Altus for $105 million. Later in the year, it invested another $100 million as the firm merged with EMX Royalty.
Tether has also been in discussions with gold-mining investment vehicles such as Terranova Resources, although no deal has materialized yet.
The goal seems clear: Tether doesn’t just want to own gold. It wants gold exposure with leverage, cash flow, and upstream access. Think royalties, not just vaults.
This echoes what we’ve seen in recent years in China, where companies like Xiaomi and BYD began as consumers of critical materials, then became stakeholders in upstream supply chains. It’s all part of building resilience into the foundation of your business.
Tether’s relationship with gold isn’t new. It launched XAUt, its gold-backed stablecoin, in 2020. Each token represents one troy ounce of physical gold, stored in Swiss vaults.
For most of its existence, XAUt was a side project. But that may be changing.
Despite gold price correction, Tether market cap increased by 0.54 billion indicating strong demand
Source: TradingView, Heyokha Research
Since August 2025, blockchain data suggests Tether added more than 275,000 ounces of gold to XAUt’s reserves. The token’s market cap has doubled over the past six months, now sitting between $1.5 to $2.1 billion.
XAUt and Paxos’ PAXG (another tokenized form of gold) together make up around 90% of the entire tokenized gold market, which is still small ($3–3.9 billion total), but growing. XAUt leads with about 49–54% market share.
Still, it’s early days. For all the hype, tokenized gold remains a tiny sliver of global gold markets, which settle over $60 billion daily.
But the use case is compelling.
Good question. Here’s how XAUt stacks up:
Compared to physical gold, XAUt offers:
But it also comes with:
Compared to “digital gold” like ETFs or app-based gold accounts, XAUt:
But:
It’s not better or worse. It’s built for a different user. If you already operate in crypto, XAUt feels like a natural extension. If your gold sits in a retirement account, it probably stays there.
The real question: will tokenized gold ever cross over?
We have explored this idea before in our blog, “Stablecoins: Genius or Just…Stable?”. We warned that stablecoins could evolve from dollar mirrors into asset-backed financial rails with their own monetary dynamics. If you ever need a refresher on how Stablecoins work, we got your back: “Stablecoins 101”.
All this to circle back on a thesis we have also explored and have been harping on – fiat debasement pushes the appeal of gold higher. You can read our thoughts in depth in our “Gold: The Return of Real Money” report.
Tether, it turns out, is acting on that thesis with alarming precision. A crypto company built on fiat liquidity is quietly becoming a force in the real-asset world.
This story is far from over.
Tether’s bullion buying already moves markets at the margin. If its 2025 profit estimates hold and the company keeps scaling gold exposure, it could soon rival the annual net purchases of more central banks.
Whether XAUt becomes a widely used digital gold standard is still uncertain. But that’s not the point.
The point is this: while most stablecoin players are debating compliance frameworks, Tether is quietly building a gold-backed war chest, a commodity lending book, and upstream access to the world’s oldest monetary metal.
And when the next currency crisis hits, the company that started by pegging to fiat might just be the one holding the hardest collateral in town.
As we like to say at Heyokha: in a world of soft money and harder choices, real money has a way of resurfacing.
Tara Mulia
For more blogs like these, subscribe to our newsletter here!
Important information
This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.
Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.
Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.
Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.
Share
When people talk about artificial intelligence, the conversation usually drifts into abstraction including but not limited to models, tokens, algorithms, cognition. But underneath all that magic is a very physical reality: silicon chips, cooling fans, thousands of kilometres of fibre optic cables, and megawatts of electricity coursing through humming data centres.
In fact, as 2025 unfolds, AI is no longer just a story of breakthroughs. It’s a story of build-outs. And increasingly, the real competitive edge doesn’t lie in model architecture or training techniques, but in something much simpler: who can scale electricity, chips, and infrastructure faster.
AI carried U.S. equities in Q3. The sector now accounts for nearly 80% of the S&P 500’s year-to-date gains. The capital intensity is staggering: AI-related investments contributed nearly 40% of U.S. GDP growth in 2025. Nvidia’s rally may get the headlines, but the unsung hero of this boom is infrastructure.
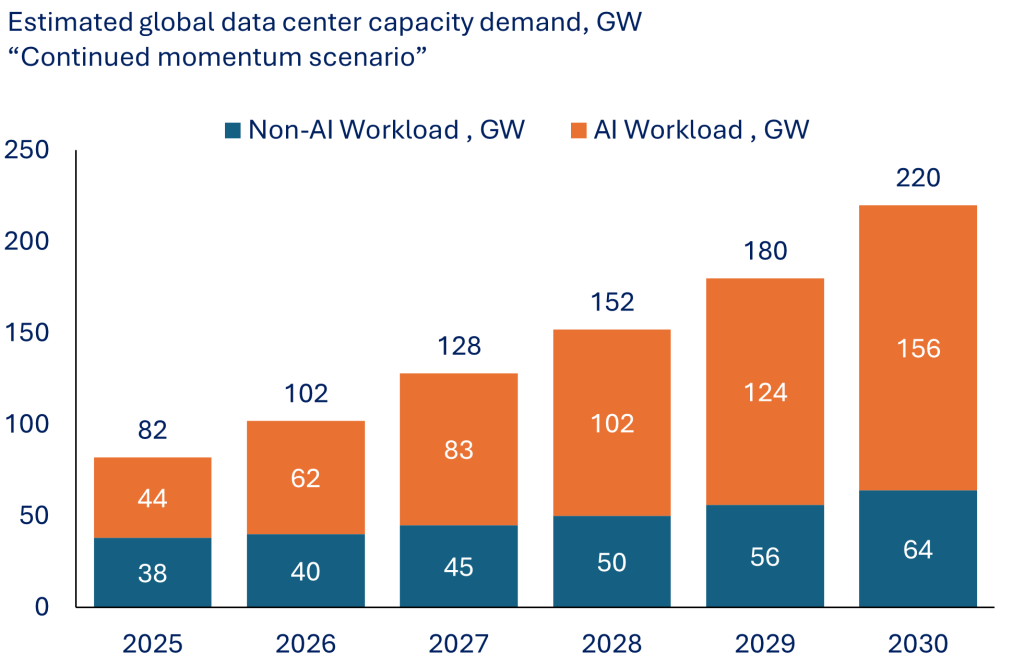
Global computing capacity is set to expand massively
Source: McKinsey
Data centres alone are projected to consume 1,600 TWh of electricity by 2035, which is the equivalent to 4.4% of global power use. That would make “AI” the world’s fourth-largest electricity consumer behind the U.S., China, and India.
Compute demand is now doubling every 100 days. Power, water, land, and transmission capacity are no longer cost inputs. They are hard constraints.
This shift is already causing cracks. Microsoft recently admitted that power has become “the biggest issue” for future data centre builds. Amazon is flagging grid shortages, even as hyperscaler capex is projected to jump from US$370 billion in 2025 to US$470 billion in 2026.
In response, U.S. tech giants are building their own generators just to keep expansion plans alive. But between fragmented state grids and a politicised permitting system, scaling energy capacity in America is looking less like innovation and more like improvisation.
China, by contrast, is turning its state-led muscle into an AI advantage. In the first nine months of 2025, China added 240 GW of solar power—more than the entire installed solar capacity of the U.S.
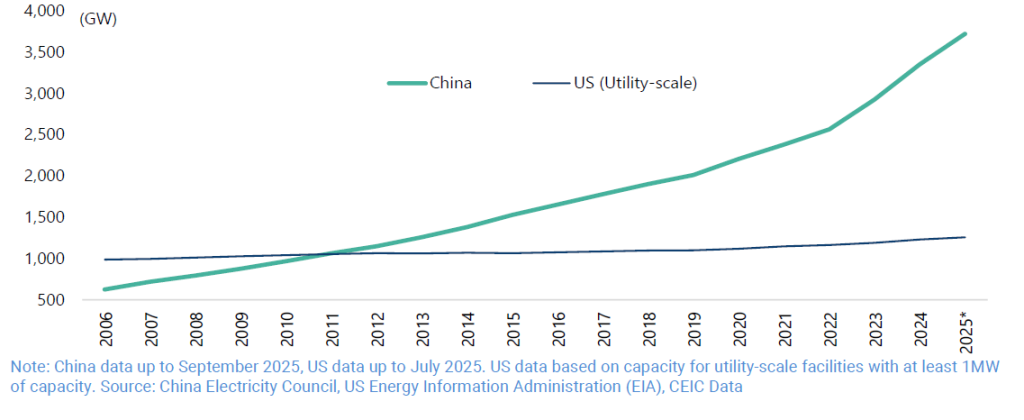
China and U.S. (utility scale) electricity generation capacity (stock). This is where the real power lies
Source: China Electricity Council, US Energy Information Administration (EIA)
According to OpenAI’s open letter to the White House, China added 429 GW of new power capacity in 2024 alone. That’s more than one-third of the entire U.S. grid, built in a single year.
And the state isn’t just expanding power. It’s subsidising it.
And it’s not just about keeping the lights on — it’s about rerouting the entire tech stack. With U.S. export controls choking access to Nvidia’s best chips, China is doubling down on homegrown hardware. That energy advantage is now powering a new playbook: build your own chips, subsidize their use, and cluster them like there’s no tomorrow.
Beijing’s strategy is clear: if you can’t buy the best chips, out-build the system around them.
With Washington tightening export controls on Nvidia’s AI hardware, Chinese tech giants found themselves cut off from the gold standard. So Huawei stepped in with a workaround: not a better chip, but a bigger cluster.
Its new CloudMatrix 384 system links together 384 of its Ascend 910C processors, compensating for weaker single-chip performance with brute-force architecture and advanced networking. The result? A cluster Huawei claims outperforms Nvidia’s flagship NVL72 on compute and memory, even if it gulps far more power and demands more manpower to maintain.
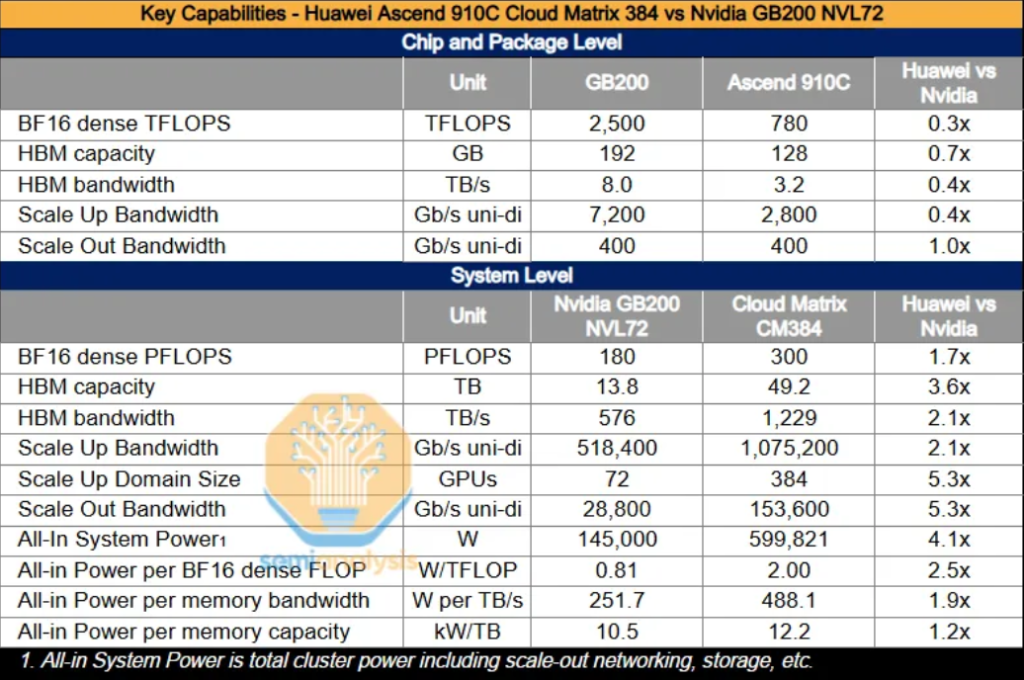
Source: SemiAnalysis, Nvidia, Huawei
A full CloudMatrix setup now delivers 300 PFLOPs of dense BF16 compute. This is nearly twice the performance of Nvidia’s GB200 NVL72. With over 3.6 times the total memory capacity and 2.1 times the bandwidth, Huawei isn’t just catching up. It’s building an AI system that can go toe-to-toe with Nvidia’s best.
And here’s where the state steps in again not just with chips, but with cheap juice.
Local governments in provinces like Gansu, Guizhou, and Inner Mongolia are now offering power subsidies that slash electricity bills by up to 50%, but only if you’re running domestic chips. That’s on top of cash incentives generous enough to cover a data centre’s operating costs for a year.
The logic is brutal but effective: reduce Chinese firms’ dependency on Nvidia and make up for the efficiency gap with fiscal firepower. Huawei’s chips may consume 30–50% more electricity than Nvidia’s, but if the power is cheap enough, it doesn’t matter.
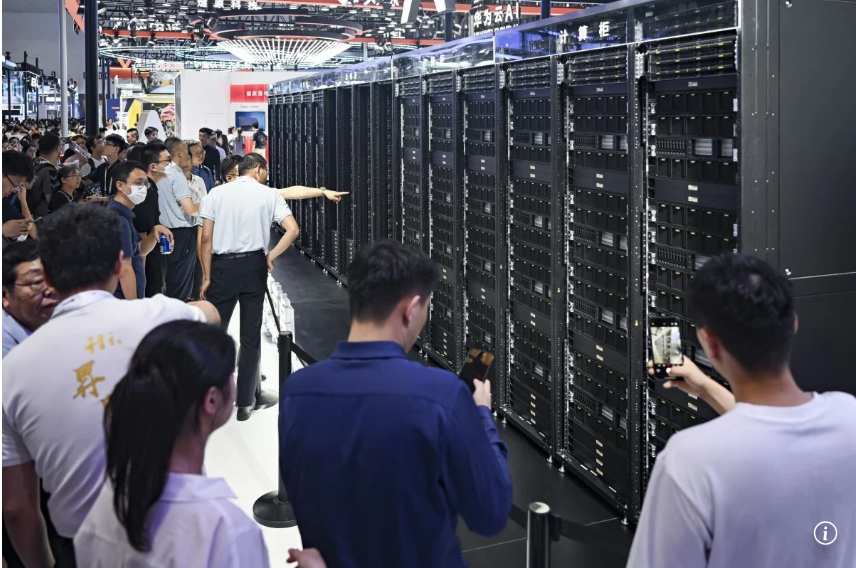
Crowd gathers to admire Huawei’s Ascend-powered CloudMatrix 384 system at the 2025 World AI Conference in Shanghai.
Source: South China Morning Post, Xinhua
And the power is, in fact, cheap. Thanks to China’s centralised grid and abundant power in remote provinces, average industrial electricity costs in these subsidised regions hover around 5.6 cents/kWh — a steep discount to the 9.1 cents/kWh U.S. average. Add a surplus of engineers, and the equation tilts further in Beijing’s favour.
CloudMatrix clusters are now being delivered to data centres serving top-tier Chinese tech clients. They aren’t just Plan B — they’re a parallel track. Built differently, powered locally, and scaled with state backing.
The Western narrative still sees AI dominance through the lens of software and algorithms. But the deeper we go, the more this becomes a game of logistics, power grids, and vertically integrated industrial policy.
China’s AI build-out shows what happens when you align energy strategy, chip design, and capital deployment. The result isn’t the most beautiful AI system. It’s the most deployable one.
For all the talk of exponential models and general intelligence, the ceiling of progress may come down to simple things: copper, electricity, trained labour, and land.
We’ve said it before in The Case for Copper: in a rewired world, it’s not software that limits us—it’s the metals behind the curtain. And AI is now hitting that same wall. Every model, every data centre, every breakthrough depends on the silent metals that carries the current.
As we like to say at Heyokha: When the world scrambles for intelligence, don’t forget who owns the grid.
Tara Mulia
For more blogs like these, subscribe to our newsletter here!
Important information
This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.
Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.
Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.
Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.
Share
When people talk about artificial intelligence, the conversation usually drifts into abstraction including but not limited to models, tokens, algorithms, cognition. But underneath all that magic is a very physical reality: silicon chips, cooling fans, thousands of kilometres of fibre optic cables, and megawatts of electricity coursing through humming data centres.
In fact, as 2025 unfolds, AI is no longer just a story of breakthroughs. It’s a story of build-outs. And increasingly, the real competitive edge doesn’t lie in model architecture or training techniques, but in something much simpler: who can scale electricity, chips, and infrastructure faster.
AI carried U.S. equities in Q3. The sector now accounts for nearly 80% of the S&P 500’s year-to-date gains. The capital intensity is staggering: AI-related investments contributed nearly 40% of U.S. GDP growth in 2025. Nvidia’s rally may get the headlines, but the unsung hero of this boom is infrastructure.
Global computing capacity is set to expand massively
Source: McKinsey
Data centres alone are projected to consume 1,600 TWh of electricity by 2035, which is the equivalent to 4.4% of global power use. That would make “AI” the world’s fourth-largest electricity consumer behind the U.S., China, and India.
Compute demand is now doubling every 100 days. Power, water, land, and transmission capacity are no longer cost inputs. They are hard constraints.
This shift is already causing cracks. Microsoft recently admitted that power has become “the biggest issue” for future data centre builds. Amazon is flagging grid shortages, even as hyperscaler capex is projected to jump from US$370 billion in 2025 to US$470 billion in 2026.
In response, U.S. tech giants are building their own generators just to keep expansion plans alive. But between fragmented state grids and a politicised permitting system, scaling energy capacity in America is looking less like innovation and more like improvisation.
China, by contrast, is turning its state-led muscle into an AI advantage. In the first nine months of 2025, China added 240 GW of solar power—more than the entire installed solar capacity of the U.S.
China and U.S. (utility scale) electricity generation capacity (stock). This is where the real power lies
Source: China Electricity Council, US Energy Information Administration (EIA)
According to OpenAI’s open letter to the White House, China added 429 GW of new power capacity in 2024 alone. That’s more than one-third of the entire U.S. grid, built in a single year.
And the state isn’t just expanding power. It’s subsidising it.
And it’s not just about keeping the lights on — it’s about rerouting the entire tech stack. With U.S. export controls choking access to Nvidia’s best chips, China is doubling down on homegrown hardware. That energy advantage is now powering a new playbook: build your own chips, subsidize their use, and cluster them like there’s no tomorrow.
Beijing’s strategy is clear: if you can’t buy the best chips, out-build the system around them.
With Washington tightening export controls on Nvidia’s AI hardware, Chinese tech giants found themselves cut off from the gold standard. So Huawei stepped in with a workaround: not a better chip, but a bigger cluster.
Its new CloudMatrix 384 system links together 384 of its Ascend 910C processors, compensating for weaker single-chip performance with brute-force architecture and advanced networking. The result? A cluster Huawei claims outperforms Nvidia’s flagship NVL72 on compute and memory, even if it gulps far more power and demands more manpower to maintain.
Source: SemiAnalysis, Nvidia, Huawei
A full CloudMatrix setup now delivers 300 PFLOPs of dense BF16 compute. This is nearly twice the performance of Nvidia’s GB200 NVL72. With over 3.6 times the total memory capacity and 2.1 times the bandwidth, Huawei isn’t just catching up. It’s building an AI system that can go toe-to-toe with Nvidia’s best.
And here’s where the state steps in again not just with chips, but with cheap juice.
Local governments in provinces like Gansu, Guizhou, and Inner Mongolia are now offering power subsidies that slash electricity bills by up to 50%, but only if you’re running domestic chips. That’s on top of cash incentives generous enough to cover a data centre’s operating costs for a year.
The logic is brutal but effective: reduce Chinese firms’ dependency on Nvidia and make up for the efficiency gap with fiscal firepower. Huawei’s chips may consume 30–50% more electricity than Nvidia’s, but if the power is cheap enough, it doesn’t matter.
Crowd gathers to admire Huawei’s Ascend-powered CloudMatrix 384 system at the 2025 World AI Conference in Shanghai.
Source: South China Morning Post, Xinhua
And the power is, in fact, cheap. Thanks to China’s centralised grid and abundant power in remote provinces, average industrial electricity costs in these subsidised regions hover around 5.6 cents/kWh — a steep discount to the 9.1 cents/kWh U.S. average. Add a surplus of engineers, and the equation tilts further in Beijing’s favour.
CloudMatrix clusters are now being delivered to data centres serving top-tier Chinese tech clients. They aren’t just Plan B — they’re a parallel track. Built differently, powered locally, and scaled with state backing.
The Western narrative still sees AI dominance through the lens of software and algorithms. But the deeper we go, the more this becomes a game of logistics, power grids, and vertically integrated industrial policy.
China’s AI build-out shows what happens when you align energy strategy, chip design, and capital deployment. The result isn’t the most beautiful AI system. It’s the most deployable one.
For all the talk of exponential models and general intelligence, the ceiling of progress may come down to simple things: copper, electricity, trained labour, and land.
We’ve said it before in The Case for Copper: in a rewired world, it’s not software that limits us—it’s the metals behind the curtain. And AI is now hitting that same wall. Every model, every data centre, every breakthrough depends on the silent metals that carries the current.
As we like to say at Heyokha: When the world scrambles for intelligence, don’t forget who owns the grid.
Tara Mulia
For more blogs like these, subscribe to our newsletter here!
Important information
This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.
Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.
Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.
Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.
Share
Share
Share

Washington is inching toward ending the longest government shutdown in U.S. history. Headlines will soon move on, analysts will breathe a temporary sigh of relief, and markets will pretend this was just another episode of political theatre.
But underneath that theatre sits a set of structural realities you can’t unsee — a deteriorating labour market, an accelerating debt spiral, policymakers quietly studying how to reprice national gold reserves, and a small Central Asian state launching the world’s first fully gold-backed, state-issued stablecoin.
Together, they reveal a simple truth:
When the old monetary order strains, the search for anchors begins.
Let’s walk through the signs.
With official government data frozen during the shutdown, investors have had to rely on private sources. And the latest Challenger, Gray & Christmas report landed like a brick.
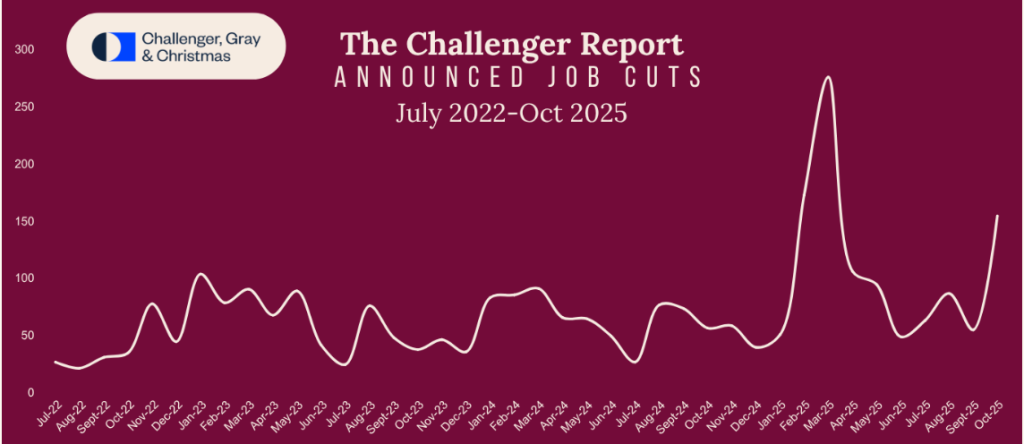
Source: Challenger
Two forces stand out:
1) Cost-cutting is back
Employers cited cost-cutting as the top reason for layoffs, responsible for:
After years of post-COVID labour hoarding: “don’t fire anyone, we won’t be able to hire them back”; CFOs have rediscovered spreadsheets.
2) AI is now officially on the layoff slips
Artificial intelligence was cited in:
Amazon alone has eliminated around 14,000 corporate roles as automation and restructuring accelerate.
This is the first real sign that AI is shifting from hype cycle to labour-displacing capital investment. This is something we’ve been expecting, but hadn’t yet seen at scale.
The twist?
We don’t fully know what’s happening in the broader labour market because the shutdown froze official data. When the government switches the lights back on, the picture may look very different from the soft-landing narrative investors still cling to.
Source: Peter G. Peterson Foundation
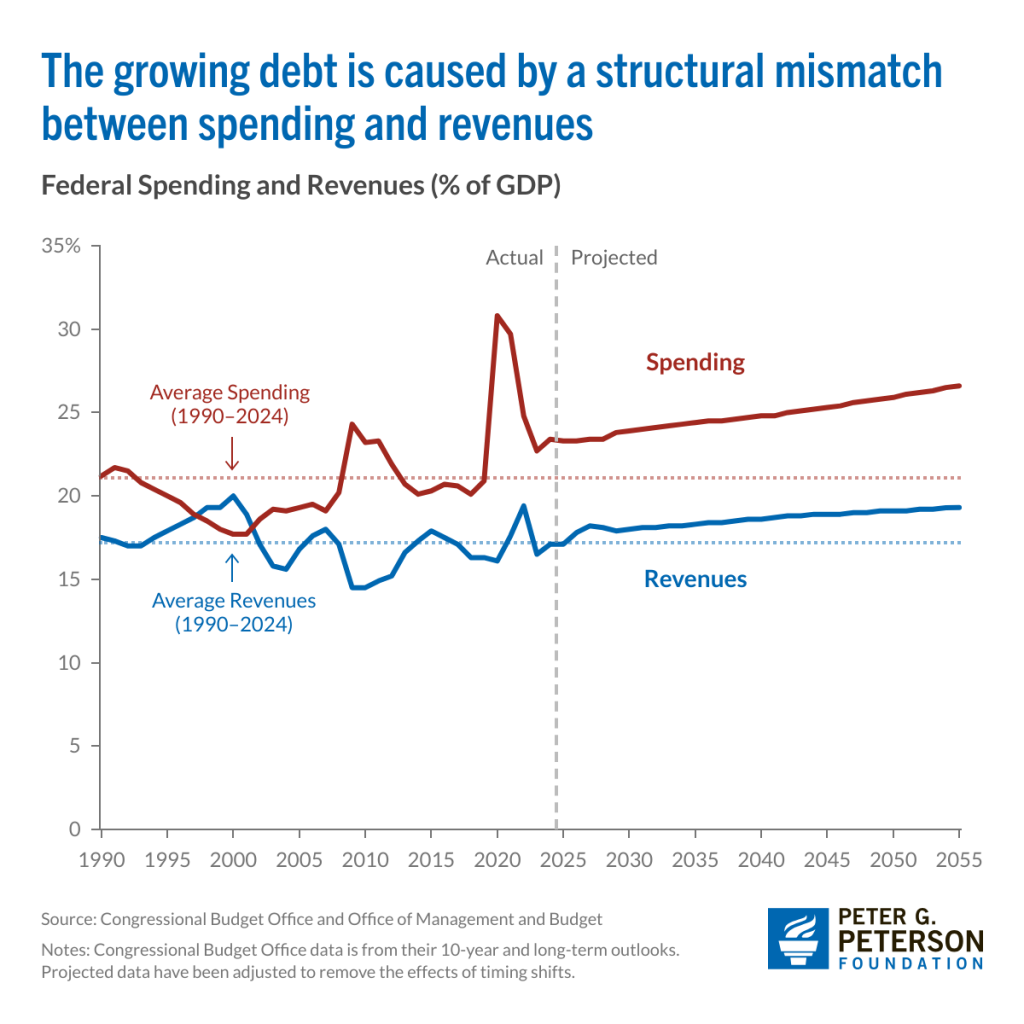
While Washington fights over weeks over extending spending, something far larger happened in the background:
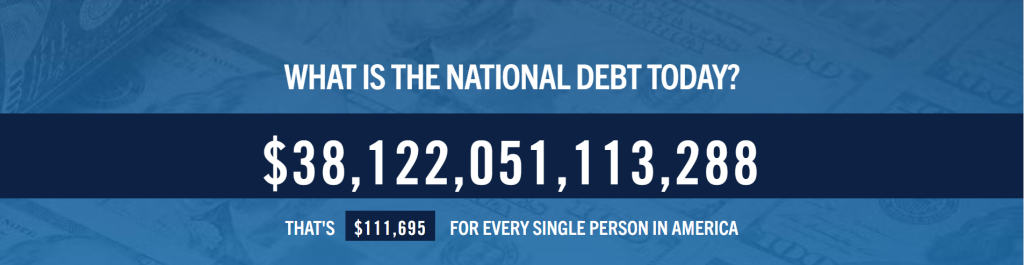
U.S. national debt just crossed US$38 trillion and that’s only two months after crossing US$37 trillion!
The pace of debt accumulation has doubled compared with the long-term trend.
To put the scale in perspective, the U.S. has added roughly US$1 trillion in just 60 days, is running a US$1.8 trillion deficit in FY2025, and is projected to accumulate US$22.7 trillion in additional deficits over the next decade.
Interest expense is now the fastest-growing line item in the federal budget: the country spent US$4 trillion on interest over the past ten years and is on track to spend US$14 trillion in the decade ahead on top of that. With borrowing costs compounding at this pace, interest is increasingly crowding out public investment from infrastructure and education to research, defense planning, and even private-sector capital formation.
Source: Peter G. Peterson Foundation
Shutdowns, ironically, make it worse:
This isn’t fiscal discipline.
It’s fiscal erosion layered on top of political dysfunction.
All three major credit rating agencies have now lowered the U.S. below their top rating citing unsustainable fiscal trajectories and political gridlock.
This is the backdrop for what comes next.
On August 1st, the Federal Reserve released a research note with a title that probably didn’t get enough attention:
“Official Reserve Revaluations: The International Experience.”
The note reviews how governments have used valuation gains on gold reserves to:
Countries cited:
Germany, Italy, Lebanon, Curaçao & Sint Maarten, and South Africa.
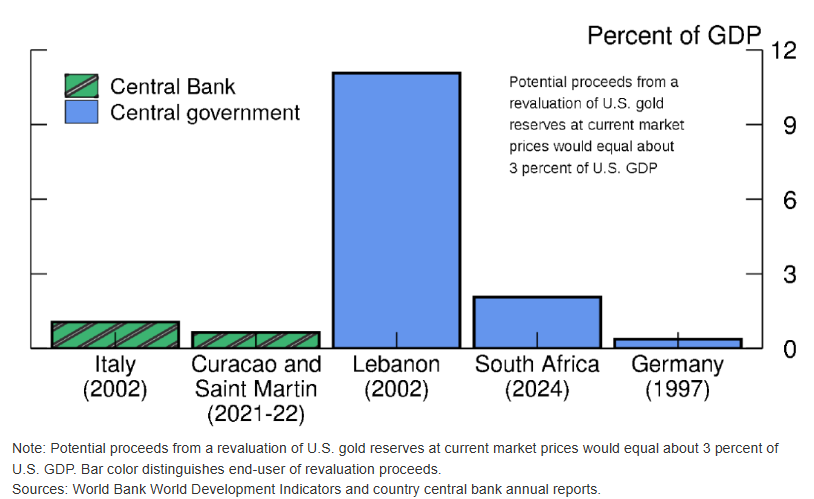
How much “extra money” countries got by revaluing their gold, and who got to use it.
Source: The Fed
But the real implication is for the United States.
The U.S. Treasury still values its gold at US$42.22 per ounce. (Set in 1973.)
It officially holds:
261.5 million troy ounces of gold (or so they say).
Book value at US$42.22 → around US$11 billion.
Now compare that to today’s gold price:
Gold is hovering around US$4,200 per ounce.
At market value, the U.S. hoard is worth:
261.5m × 4,200 ≈ US$1.1 trillion
That’s almost 100× the book value.
In other words: the U.S. has a trillion-dollar hidden fiscal asset.
And the mechanism to tap it is shockingly simple.
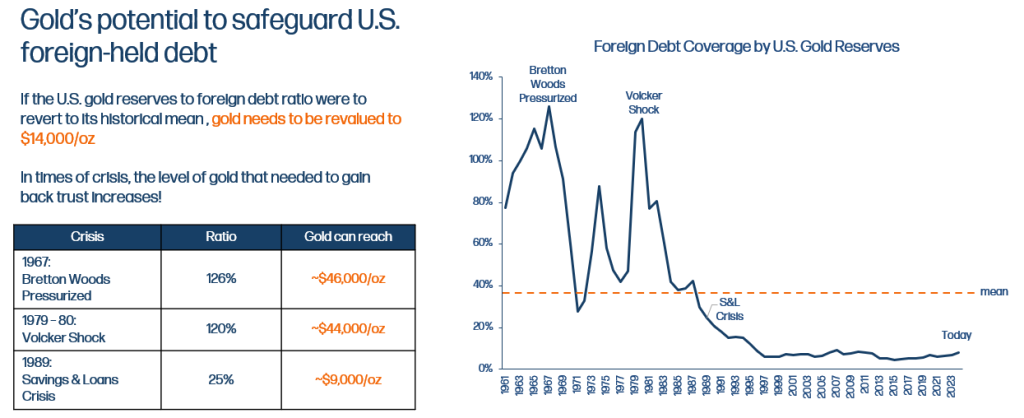
Source: Heyokha Research
How a gold revaluation works
The Treasury already issues gold certificates to the Fed at the outdated US$42.22 price.
A revaluation would:
A pure accounting maneuver.
But not a free one
A move like this:
Historically, gold revaluation only comes during:
The fact that the Fed is studying this now, as debt hits US$38 trillion and interest costs spiral, speaks volumes.
When a system starts looking at its gold like a pawnshop looks at a wedding ring, something deeper is happening.
While the U.S. quietly examines gold revaluation as a balance-sheet tool, a small Central Asian nation is doing something far more explicit.
Meet USDKG -> Kyrgyzstan’s state-issued, gold-backed stablecoin.
USDKG went live on October 31, 2025, with its public listing following in early November. It’s designed to be simple in form but radical in implication: a digital token pegged 1:1 to the U.S. dollar, fully backed by physical gold, custodied and audited by the Kyrgyz Ministry of Finance, and recorded on transparent blockchain rails.
In other words: an old-world anchor meeting new-world plumbing.
Initial issuance: 50.1 million tokens
Initial gold reserve: roughly US$500 million, scaling toward US$2 billion
Kyrgyzstan is now the first country in the world to issue a state-backed stablecoin fully collateralized by gold.
Why they’re doing it
USDKG is meant to:
For a region culturally anchored to gold, this offers a familiar foundation with modern infrastructure.
Risks
But symbolically?
It’s a milestone.
In one part of the world, policymakers are quietly discussing revaluing gold to fill fiscal holes.
In another, a government is explicitly tokenizing gold to build a new monetary instrument.
Put the pieces together:
These are not isolated events.
They’re signals of a monetary order under pressure and of societies reaching for anchors.
Corporates seek anchors in automation.
Governments seek anchors in asset revaluations.
Emerging markets seek anchors in tokenized gold.
For investors, the takeaway isn’t that the dollar collapses tomorrow or that gold-stablecoins replace SWIFT.
The message is subtler and more important:
In a regime where labour weakens, debt accelerates, and policymakers test non-traditional monetary levers, real assets and pricing power become the central pillars of portfolio resilience.
The shutdown may end.
The headlines will move on.
But the deeper story of a system inching toward a fiscal and monetary reset is just the beginning.
Tara Mulia
For more blogs like these, subscribe to our newsletter here!
Important information
This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.
Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.
Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.
Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.
Share
Washington is inching toward ending the longest government shutdown in U.S. history. Headlines will soon move on, analysts will breathe a temporary sigh of relief, and markets will pretend this was just another episode of political theatre.
But underneath that theatre sits a set of structural realities you can’t unsee — a deteriorating labour market, an accelerating debt spiral, policymakers quietly studying how to reprice national gold reserves, and a small Central Asian state launching the world’s first fully gold-backed, state-issued stablecoin.
Together, they reveal a simple truth:
When the old monetary order strains, the search for anchors begins.
Let’s walk through the signs.
With official government data frozen during the shutdown, investors have had to rely on private sources. And the latest Challenger, Gray & Christmas report landed like a brick.
Source: Challenger
Two forces stand out:
1) Cost-cutting is back
Employers cited cost-cutting as the top reason for layoffs, responsible for:
After years of post-COVID labour hoarding: “don’t fire anyone, we won’t be able to hire them back”; CFOs have rediscovered spreadsheets.
2) AI is now officially on the layoff slips
Artificial intelligence was cited in:
Amazon alone has eliminated around 14,000 corporate roles as automation and restructuring accelerate.
This is the first real sign that AI is shifting from hype cycle to labour-displacing capital investment. This is something we’ve been expecting, but hadn’t yet seen at scale.
The twist?
We don’t fully know what’s happening in the broader labour market because the shutdown froze official data. When the government switches the lights back on, the picture may look very different from the soft-landing narrative investors still cling to.
Source: Peter G. Peterson Foundation
While Washington fights over weeks over extending spending, something far larger happened in the background:
U.S. national debt just crossed US$38 trillion and that’s only two months after crossing US$37 trillion!
The pace of debt accumulation has doubled compared with the long-term trend.
To put the scale in perspective, the U.S. has added roughly US$1 trillion in just 60 days, is running a US$1.8 trillion deficit in FY2025, and is projected to accumulate US$22.7 trillion in additional deficits over the next decade.
Interest expense is now the fastest-growing line item in the federal budget: the country spent US$4 trillion on interest over the past ten years and is on track to spend US$14 trillion in the decade ahead on top of that. With borrowing costs compounding at this pace, interest is increasingly crowding out public investment from infrastructure and education to research, defense planning, and even private-sector capital formation.
Source: Peter G. Peterson Foundation
Shutdowns, ironically, make it worse:
This isn’t fiscal discipline.
It’s fiscal erosion layered on top of political dysfunction.
All three major credit rating agencies have now lowered the U.S. below their top rating citing unsustainable fiscal trajectories and political gridlock.
This is the backdrop for what comes next.
On August 1st, the Federal Reserve released a research note with a title that probably didn’t get enough attention:
“Official Reserve Revaluations: The International Experience.”
The note reviews how governments have used valuation gains on gold reserves to:
Countries cited:
Germany, Italy, Lebanon, Curaçao & Sint Maarten, and South Africa.
How much “extra money” countries got by revaluing their gold, and who got to use it.
Source: The Fed
But the real implication is for the United States.
The U.S. Treasury still values its gold at US$42.22 per ounce. (Set in 1973.)
It officially holds:
261.5 million troy ounces of gold (or so they say).
Book value at US$42.22 → around US$11 billion.
Now compare that to today’s gold price:
Gold is hovering around US$4,200 per ounce.
At market value, the U.S. hoard is worth:
261.5m × 4,200 ≈ US$1.1 trillion
That’s almost 100× the book value.
In other words: the U.S. has a trillion-dollar hidden fiscal asset.
And the mechanism to tap it is shockingly simple.
Source: Heyokha Research
How a gold revaluation works
The Treasury already issues gold certificates to the Fed at the outdated US$42.22 price.
A revaluation would:
A pure accounting maneuver.
But not a free one
A move like this:
Historically, gold revaluation only comes during:
The fact that the Fed is studying this now, as debt hits US$38 trillion and interest costs spiral, speaks volumes.
When a system starts looking at its gold like a pawnshop looks at a wedding ring, something deeper is happening.
While the U.S. quietly examines gold revaluation as a balance-sheet tool, a small Central Asian nation is doing something far more explicit.
Meet USDKG -> Kyrgyzstan’s state-issued, gold-backed stablecoin.
USDKG went live on October 31, 2025, with its public listing following in early November. It’s designed to be simple in form but radical in implication: a digital token pegged 1:1 to the U.S. dollar, fully backed by physical gold, custodied and audited by the Kyrgyz Ministry of Finance, and recorded on transparent blockchain rails.
In other words: an old-world anchor meeting new-world plumbing.
Initial issuance: 50.1 million tokens
Initial gold reserve: roughly US$500 million, scaling toward US$2 billion
Kyrgyzstan is now the first country in the world to issue a state-backed stablecoin fully collateralized by gold.
Why they’re doing it
USDKG is meant to:
For a region culturally anchored to gold, this offers a familiar foundation with modern infrastructure.
Risks
But symbolically?
It’s a milestone.
In one part of the world, policymakers are quietly discussing revaluing gold to fill fiscal holes.
In another, a government is explicitly tokenizing gold to build a new monetary instrument.
Put the pieces together:
These are not isolated events.
They’re signals of a monetary order under pressure and of societies reaching for anchors.
Corporates seek anchors in automation.
Governments seek anchors in asset revaluations.
Emerging markets seek anchors in tokenized gold.
For investors, the takeaway isn’t that the dollar collapses tomorrow or that gold-stablecoins replace SWIFT.
The message is subtler and more important:
In a regime where labour weakens, debt accelerates, and policymakers test non-traditional monetary levers, real assets and pricing power become the central pillars of portfolio resilience.
The shutdown may end.
The headlines will move on.
But the deeper story of a system inching toward a fiscal and monetary reset is just the beginning.
Tara Mulia
For more blogs like these, subscribe to our newsletter here!
Important information
This article is published by Heyokha Brothers Limited (“Heyokha”), a corporation licensed by the Securities and Futures Commission of Hong Kong (CE No. BOS569). It is provided for general information and discussion purposes only. It reflects the authors’ views and observations at the date of publication, and these may change without notice.
Nothing in this article is investment, legal, tax or other professional advice, investment research, or a recommendation, offer or solicitation to buy or sell any security, fund or other investment product. It is not directed at any person in any jurisdiction where its publication or availability would be unlawful. Any companies, securities or assets mentioned are for illustration only and are not a recommendation.
Information from third-party sources is believed to be reliable, but it has not been independently verified. No representation or warranty is given as to its accuracy or completeness. Forward-looking statements are inherently uncertain, and actual outcomes may differ materially. Investment involves risk, the value of investments can go down as well as up, and past performance is not indicative of future results. Heyokha, its directors and employees, and funds it manages may hold positions in assets mentioned.
Readers should seek independent professional advice before making any investment decision. This article has not been reviewed by the Securities and Futures Commission.
Share
Share
Share
Share
Share
Share
Share
Share
Share
Share
Share
Sign up to receive insights, updates, and perspectives directly from Heyokha
Sign up to receive insights, updates, and perspectives directly from Heyokha
We drive our mission with an exceptional culture through applying a growth mindset where holistic and on the ground research is at our core.
You must read the following information before proceeding. By accessing this website and any pages thereof, you acknowledge that you have read the following information and accept the terms and conditions set out below and agree to be bound by such terms and conditions. If you do not agree to such terms and conditions, please do not access this website or any pages thereof.
The website has been prepared by Heyokha Brothers Limited and is solely intended for informational purposes and should not be construed as an inducement to purchase or sell any security, product, service, or investment. The Site does not solicit an offer to buy or sell any financial instrument or enter into any agreement. It is important to note that the opinions expressed on the Site are not considered investment advice, and it is recommended that individuals seek independent advice as needed to address their specific objectives, financial situation, or needs. It is the responsibility of the persons who access this website to observe all applicable laws and regulations.
The Site offers general information exclusively and does not consider the individual circumstances of any person. The data, opinions, and estimates presented on the Site are current as of the publication date and are subject to changes without notice. Additionally, it is possible that such information may become obsolete with time.
The content presented on this website is exclusively intended for authorized intermediaries and qualified investors within Hong Kong, such as institutional investors, professional investors, and accredited investors (as defined under the SFO). It is not intended for retail investors or individuals located outside of Hong Kong.
The products and services mentioned on this website may or may not be authorized or registered for distribution in a particular jurisdiction and may not be suitable for all investor types. It is important to note that this website is not intended to constitute an offer or solicitation, nor is it directed toward individuals if the provider of the information is prohibited by any law of any jurisdiction from making the information available. Moreover, the website is not intended for any use that would violate local laws or regulations. The provider of the information is not permitted to promote any products or services mentioned on this website in jurisdictions where such promotion would be prohibited.
If you are not a qualified investor or licensed intermediary in Hong Kong, you should not proceed any further.
The information provided on this Website is for informational purposes only and should not be considered as investment advice or a recommendation to buy, sell, hold, or transact in any investment. It is strongly recommended that individuals seek professional investment advice before making any investment decisions.
The information presented on this Website does not consider the investment objectives, specific needs, or financial situations of any investor. It is important to note that nothing on this Website is intended to constitute financial, legal, accounting, or tax advice.
Before making any investment decision, individuals should carefully consider whether an investment aligns with their investment objectives, specific needs, and financial situation. This should also include informing oneself of any potential tax implications, legal requirements, foreign exchange restrictions, or exchange control requirements that may be relevant to an investment based on the laws of one’s citizenship, residence, or domicile. If there is any doubt regarding the information on this Website, it is recommended that individuals seek independent professional financial advice.
It is important to note that any opinion, comment, article, financial analysis, market forecast, market commentary, or other information published on the Website is not binding on Heyokha or its affiliates, and they are not responsible for the information, opinions, or ideas presented.
Users are solely responsible for protecting and backing up their data and equipment, as well as taking reasonable precautions against any computer virus or other destructive elements. Additionally, users must ensure that their access to the Site is adequately secured against unauthorized access.
Users are prohibited from using the Site for any unlawful, defamatory, offensive, abusive, indecent, menacing, or threatening purposes, or in any way that infringes upon intellectual property rights or confidentiality obligations. Furthermore, users may not use the Site to cause annoyance, inconvenience, or anxiety to others, or in any way that violates any applicable laws or regulations.
Users must comply with any terms notified to them by third-party suppliers of data or services to the Site. This may include entering into a direct agreement with such third parties in respect of their use of the dat
This website may contain Third Party Content or links to websites maintained by third parties that are not affiliated with Heyokha. Heyokha does not participate in the preparation, adoption, or editing of such third-party materials and does not endorse or approve such content, either explicitly or implicitly. Any opinions or recommendations expressed on third party materials are solely those of the independent providers and not of Heyokha. Heyokha is not responsible for any errors or omissions relating to specific information provided by any third party.
Although Heyokha aims to provide accurate and timely information to users, neither Heyokha nor the Third-Party Content providers guarantee on the accuracy, timeliness, completeness, usefulness, or any other aspect of the information presented. Heyokha is not responsible or liable for any content, including advertising, products, or other materials on or available from third party sites. Users access and use Third Party content is at their own risk, and it is provided for informational purposes only. Both Heyokha and the Third-Party shall not be liable for any loss or damage arising from users’ reliance upon such information.
The content of this website is subject to copyright and other intellectual property laws. All trademarks, service marks, logos, and brand features displayed on the website are owned by their respective owners, except as explicitly noted. Users may use the information on this website and reproduce it for personal reference only. However, reproduction, distribution, transmission, incorporation in any other database, document, or material, and sale or distribution of any part of the contents of the website is strictly prohibited. Users may download or print individual sections of the website for personal use and information only, provided they are legally entitled to access the material and retain all copyright and other proprietary notices.
Any unauthorized use of the content, trademarks, service marks, or logos displayed on the website may violate copyright, trademark, or other intellectual property laws, as well as laws of privacy and publicity and communications. Any reference or link to any specific commercial product, process, or service by trade name, trademark, manufacturer, or otherwise, does not necessarily constitute or imply its endorsement, recommendation, or favouring by our company.
We provide such references or links solely for the convenience of our users and to provide additional information. Our company is not responsible for the accuracy, legality, or content of any external website or resource linked to or referenced from our website. Users are solely responsible for complying with the terms and conditions of any external websites or resources.
In order to enhance user experience and simplify future visits, this website may utilize cookies to track your activity. However, if you do not want to store cookies on your device, you can disable them by adjusting your browser’s security settings.
Please read our Privacy Statement before providing Heyokha with any personal information on this website. By providing any personal information on this website, you will be deemed to have read and accepted our Privacy Statement.
The information contained on the website is accurate only as of the date of publication and does not constitute investment advice or recommendations. While certain tools available on the website may provide general investment or financial analyses based upon personalized input, such results are for information purposes only, and users should refer to the assumptions and limitations relevant to the use of such tools as set out on the website. Users are solely responsible for determining whether any investment, security or strategy, or any other product or service is appropriate or suitable for them based on their investment objectives and personal and financial situation. Users should consult their independent professional advisers if they have any questions. Any person considering an investment should seek independent advice on the suitability or otherwise of the particular investment.
Disclaimer of Liability Heyokha makes no warranty as to the accuracy, completeness, security, and confidentiality of information available through the website. Heyokha, its affiliates, directors, officers, or employees accept no liability for any errors or omissions relating to information available through the website or for any damages, losses or expenses arising in connection with the website, whether direct or indirect, arising from the use of the website or its contents. Heyokha also reserves the right to modify, suspend, or discontinue the website at any time without notice. Heyokha shall not be liable for any such modification, suspension, or discontinuance.
Pursuant to the Personal Data (Privacy) Ordinance (the ‘Ordinance’), Heyokha Brothers Limited is fully committed to safeguarding the privacy and security of personal information in compliance with all relevant laws and regulations. This statement outlines how we collect, use, and protect personal information provided to us.
We collect and maintain personal information, in a manner consistent with all relevant laws and regulations. We take necessary measures to ensure that personal information is correct and up to date. Personal information will only be used for the purpose of utilization and will not be disclosed to third parties (except our related parties e.g.: Administrators) without consent from the individual, except for justifiable grounds as required by laws and regulations.
We may collect various types of personal data from or about you, including:
The Company may automatically collect information about you from computer or internet browser through the use of cookies, pixel tags, and other similar technologies to enhance the user experience on its websites. Third parties may be used to collect personal data and information indirectly through monitoring activities conducted by the Company or on its behalf.
Company does not knowingly collect personal data from anyone under the age of 18 and does not seek to collect or process sensitive information unless required or permitted by law and with express consent.
We may use your personal data for the purposes it was provided and in connection with our services as described below:
We provide thorough training to our officers and employees to prevent the leakage or inappropriate use of personal information and provide information on a need-to-know basis. Managers in charge for controls and inspections are appointed, and appropriate control systems are established to ensure the privacy and security of personal information.
In the event that personal information is provided to an external contractor (e.g.: Administrator), we take responsibility for ensuring that the external contractor has proper systems in place to protect the privacy of personal information.
Personal information held by us relating to an individual will be kept confidential but may be provided to third parties the following purpose:
Disclosure, correction and termination of usage shall be carried out upon request of an individual in accordance with relevant laws and regulations.
Personal information collected will be retained for no longer than is necessary for the fulfilment of the purposes for which it was collected as per applicable laws and regulations.
Under relevant laws and regulations, any individual has the right to request access to any of the personal data that we hold by submitting a written request. Individuals are also entitled to request to correct, cancel or delete any of the personal data we hold if they believe such information is inaccurate, out of date or we no longer have a legitimate interest or lawful justification to retain or process.
Heyokha Brothers Limited is the issuer of this website and holds Type 4 (advising on securities) and Type 9 (asset management) licenses issued by the Securities and Futures Commission in Hong Kong.
The information provided on this website has been prepared solely for licensed intermediaries and qualified investors in Hong Kong, including professional investors, institutional investors, and accredited investors (as defined under the Securities and Futures Ordinance). The information provided on this website is for informational purposes only and should not be construed as investment advice, nor an offer to sell or a solicitation of an offer to buy any security, investment product, or service.
Investment involves risk and investors may lose their entire investment. Investors are advised to seek professional advice before making any investment decisions. Past performance is not indicative of future performance and the value of investments may fluctuate. Please refer to the offering document(s) for details, including the investment objectives, risk factors, and fees and charges.
Heyokha Brothers Limited reserves the right to amend, update, or remove any information on this website at any time without notice. By accessing and using this website, you agree to be bound by the above terms and conditions.
We drive our mission with an exceptional culture through applying a growth mindset where holistic and on the ground research is at our core.
You must read the following information before proceeding. By accessing this website and any pages thereof, you acknowledge that you have read the following information and accept the terms and conditions set out below and agree to be bound by such terms and conditions. If you do not agree to such terms and conditions, please do not access this website or any pages thereof.
The website has been prepared by Heyokha Brothers Limited and is solely intended for informational purposes and should not be construed as an inducement to purchase or sell any security, product, service, or investment. The Site does not solicit an offer to buy or sell any financial instrument or enter into any agreement. It is important to note that the opinions expressed on the Site are not considered investment advice, and it is recommended that individuals seek independent advice as needed to address their specific objectives, financial situation, or needs. It is the responsibility of the persons who access this website to observe all applicable laws and regulations.
The Site offers general information exclusively and does not consider the individual circumstances of any person. The data, opinions, and estimates presented on the Site are current as of the publication date and are subject to changes without notice. Additionally, it is possible that such information may become obsolete with time.
The content presented on this website is exclusively intended for authorized intermediaries and qualified investors within Hong Kong, such as institutional investors, professional investors, and accredited investors (as defined under the SFO). It is not intended for retail investors or individuals located outside of Hong Kong.
The products and services mentioned on this website may or may not be authorized or registered for distribution in a particular jurisdiction and may not be suitable for all investor types. It is important to note that this website is not intended to constitute an offer or solicitation, nor is it directed toward individuals if the provider of the information is prohibited by any law of any jurisdiction from making the information available. Moreover, the website is not intended for any use that would violate local laws or regulations. The provider of the information is not permitted to promote any products or services mentioned on this website in jurisdictions where such promotion would be prohibited.
If you are not a qualified investor or licensed intermediary in Hong Kong, you should not proceed any further.
The information provided on this Website is for informational purposes only and should not be considered as investment advice or a recommendation to buy, sell, hold, or transact in any investment. It is strongly recommended that individuals seek professional investment advice before making any investment decisions.
The information presented on this Website does not consider the investment objectives, specific needs, or financial situations of any investor. It is important to note that nothing on this Website is intended to constitute financial, legal, accounting, or tax advice.
Before making any investment decision, individuals should carefully consider whether an investment aligns with their investment objectives, specific needs, and financial situation. This should also include informing oneself of any potential tax implications, legal requirements, foreign exchange restrictions, or exchange control requirements that may be relevant to an investment based on the laws of one’s citizenship, residence, or domicile. If there is any doubt regarding the information on this Website, it is recommended that individuals seek independent professional financial advice.
It is important to note that any opinion, comment, article, financial analysis, market forecast, market commentary, or other information published on the Website is not binding on Heyokha or its affiliates, and they are not responsible for the information, opinions, or ideas presented.
Users are solely responsible for protecting and backing up their data and equipment, as well as taking reasonable precautions against any computer virus or other destructive elements. Additionally, users must ensure that their access to the Site is adequately secured against unauthorized access.
Users are prohibited from using the Site for any unlawful, defamatory, offensive, abusive, indecent, menacing, or threatening purposes, or in any way that infringes upon intellectual property rights or confidentiality obligations. Furthermore, users may not use the Site to cause annoyance, inconvenience, or anxiety to others, or in any way that violates any applicable laws or regulations.
Users must comply with any terms notified to them by third-party suppliers of data or services to the Site. This may include entering into a direct agreement with such third parties in respect of their use of the dat
This website may contain Third Party Content or links to websites maintained by third parties that are not affiliated with Heyokha. Heyokha does not participate in the preparation, adoption, or editing of such third-party materials and does not endorse or approve such content, either explicitly or implicitly. Any opinions or recommendations expressed on third party materials are solely those of the independent providers and not of Heyokha. Heyokha is not responsible for any errors or omissions relating to specific information provided by any third party.
Although Heyokha aims to provide accurate and timely information to users, neither Heyokha nor the Third-Party Content providers guarantee on the accuracy, timeliness, completeness, usefulness, or any other aspect of the information presented. Heyokha is not responsible or liable for any content, including advertising, products, or other materials on or available from third party sites. Users access and use Third Party content is at their own risk, and it is provided for informational purposes only. Both Heyokha and the Third-Party shall not be liable for any loss or damage arising from users’ reliance upon such information.
The content of this website is subject to copyright and other intellectual property laws. All trademarks, service marks, logos, and brand features displayed on the website are owned by their respective owners, except as explicitly noted. Users may use the information on this website and reproduce it for personal reference only. However, reproduction, distribution, transmission, incorporation in any other database, document, or material, and sale or distribution of any part of the contents of the website is strictly prohibited. Users may download or print individual sections of the website for personal use and information only, provided they are legally entitled to access the material and retain all copyright and other proprietary notices.
Any unauthorized use of the content, trademarks, service marks, or logos displayed on the website may violate copyright, trademark, or other intellectual property laws, as well as laws of privacy and publicity and communications. Any reference or link to any specific commercial product, process, or service by trade name, trademark, manufacturer, or otherwise, does not necessarily constitute or imply its endorsement, recommendation, or favouring by our company.
We provide such references or links solely for the convenience of our users and to provide additional information. Our company is not responsible for the accuracy, legality, or content of any external website or resource linked to or referenced from our website. Users are solely responsible for complying with the terms and conditions of any external websites or resources.
In order to enhance user experience and simplify future visits, this website may utilize cookies to track your activity. However, if you do not want to store cookies on your device, you can disable them by adjusting your browser’s security settings.
Please read our Privacy Statement before providing Heyokha with any personal information on this website. By providing any personal information on this website, you will be deemed to have read and accepted our Privacy Statement.
The information contained on the website is accurate only as of the date of publication and does not constitute investment advice or recommendations. While certain tools available on the website may provide general investment or financial analyses based upon personalized input, such results are for information purposes only, and users should refer to the assumptions and limitations relevant to the use of such tools as set out on the website. Users are solely responsible for determining whether any investment, security or strategy, or any other product or service is appropriate or suitable for them based on their investment objectives and personal and financial situation. Users should consult their independent professional advisers if they have any questions. Any person considering an investment should seek independent advice on the suitability or otherwise of the particular investment.
Disclaimer of Liability Heyokha makes no warranty as to the accuracy, completeness, security, and confidentiality of information available through the website. Heyokha, its affiliates, directors, officers, or employees accept no liability for any errors or omissions relating to information available through the website or for any damages, losses or expenses arising in connection with the website, whether direct or indirect, arising from the use of the website or its contents. Heyokha also reserves the right to modify, suspend, or discontinue the website at any time without notice. Heyokha shall not be liable for any such modification, suspension, or discontinuance.
Pursuant to the Personal Data (Privacy) Ordinance (the ‘Ordinance’), Heyokha Brothers Limited is fully committed to safeguarding the privacy and security of personal information in compliance with all relevant laws and regulations. This statement outlines how we collect, use, and protect personal information provided to us.
We collect and maintain personal information, in a manner consistent with all relevant laws and regulations. We take necessary measures to ensure that personal information is correct and up to date. Personal information will only be used for the purpose of utilization and will not be disclosed to third parties (except our related parties e.g.: Administrators) without consent from the individual, except for justifiable grounds as required by laws and regulations.
We may collect various types of personal data from or about you, including:
The Company may automatically collect information about you from computer or internet browser through the use of cookies, pixel tags, and other similar technologies to enhance the user experience on its websites. Third parties may be used to collect personal data and information indirectly through monitoring activities conducted by the Company or on its behalf.
Company does not knowingly collect personal data from anyone under the age of 18 and does not seek to collect or process sensitive information unless required or permitted by law and with express consent.
We may use your personal data for the purposes it was provided and in connection with our services as described below:
We provide thorough training to our officers and employees to prevent the leakage or inappropriate use of personal information and provide information on a need-to-know basis. Managers in charge for controls and inspections are appointed, and appropriate control systems are established to ensure the privacy and security of personal information.
In the event that personal information is provided to an external contractor (e.g.: Administrator), we take responsibility for ensuring that the external contractor has proper systems in place to protect the privacy of personal information.
Personal information held by us relating to an individual will be kept confidential but may be provided to third parties the following purpose:
Disclosure, correction and termination of usage shall be carried out upon request of an individual in accordance with relevant laws and regulations.
Personal information collected will be retained for no longer than is necessary for the fulfilment of the purposes for which it was collected as per applicable laws and regulations.
Under relevant laws and regulations, any individual has the right to request access to any of the personal data that we hold by submitting a written request. Individuals are also entitled to request to correct, cancel or delete any of the personal data we hold if they believe such information is inaccurate, out of date or we no longer have a legitimate interest or lawful justification to retain or process.
Heyokha Brothers Limited is the issuer of this website and holds Type 4 (advising on securities) and Type 9 (asset management) licenses issued by the Securities and Futures Commission in Hong Kong.
The information provided on this website has been prepared solely for licensed intermediaries and qualified investors in Hong Kong, including professional investors, institutional investors, and accredited investors (as defined under the Securities and Futures Ordinance). The information provided on this website is for informational purposes only and should not be construed as investment advice, nor an offer to sell or a solicitation of an offer to buy any security, investment product, or service.
Investment involves risk and investors may lose their entire investment. Investors are advised to seek professional advice before making any investment decisions. Past performance is not indicative of future performance and the value of investments may fluctuate. Please refer to the offering document(s) for details, including the investment objectives, risk factors, and fees and charges.
Heyokha Brothers Limited reserves the right to amend, update, or remove any information on this website at any time without notice. By accessing and using this website, you agree to be bound by the above terms and conditions.
You will now gain access to our latest insights, updates, and carefully selected stories, designed to keep you informed and ahead of the curve.